Buying from a Private Seller in Poland: New PCC Threshold from 3 November 2026

Buying a laptop, phone, or car from a private seller may seem straightforward: you agree on the price, sign a contract, make the payment, and collect the item. In Poland, however, the buyer may also need to account for PCC.
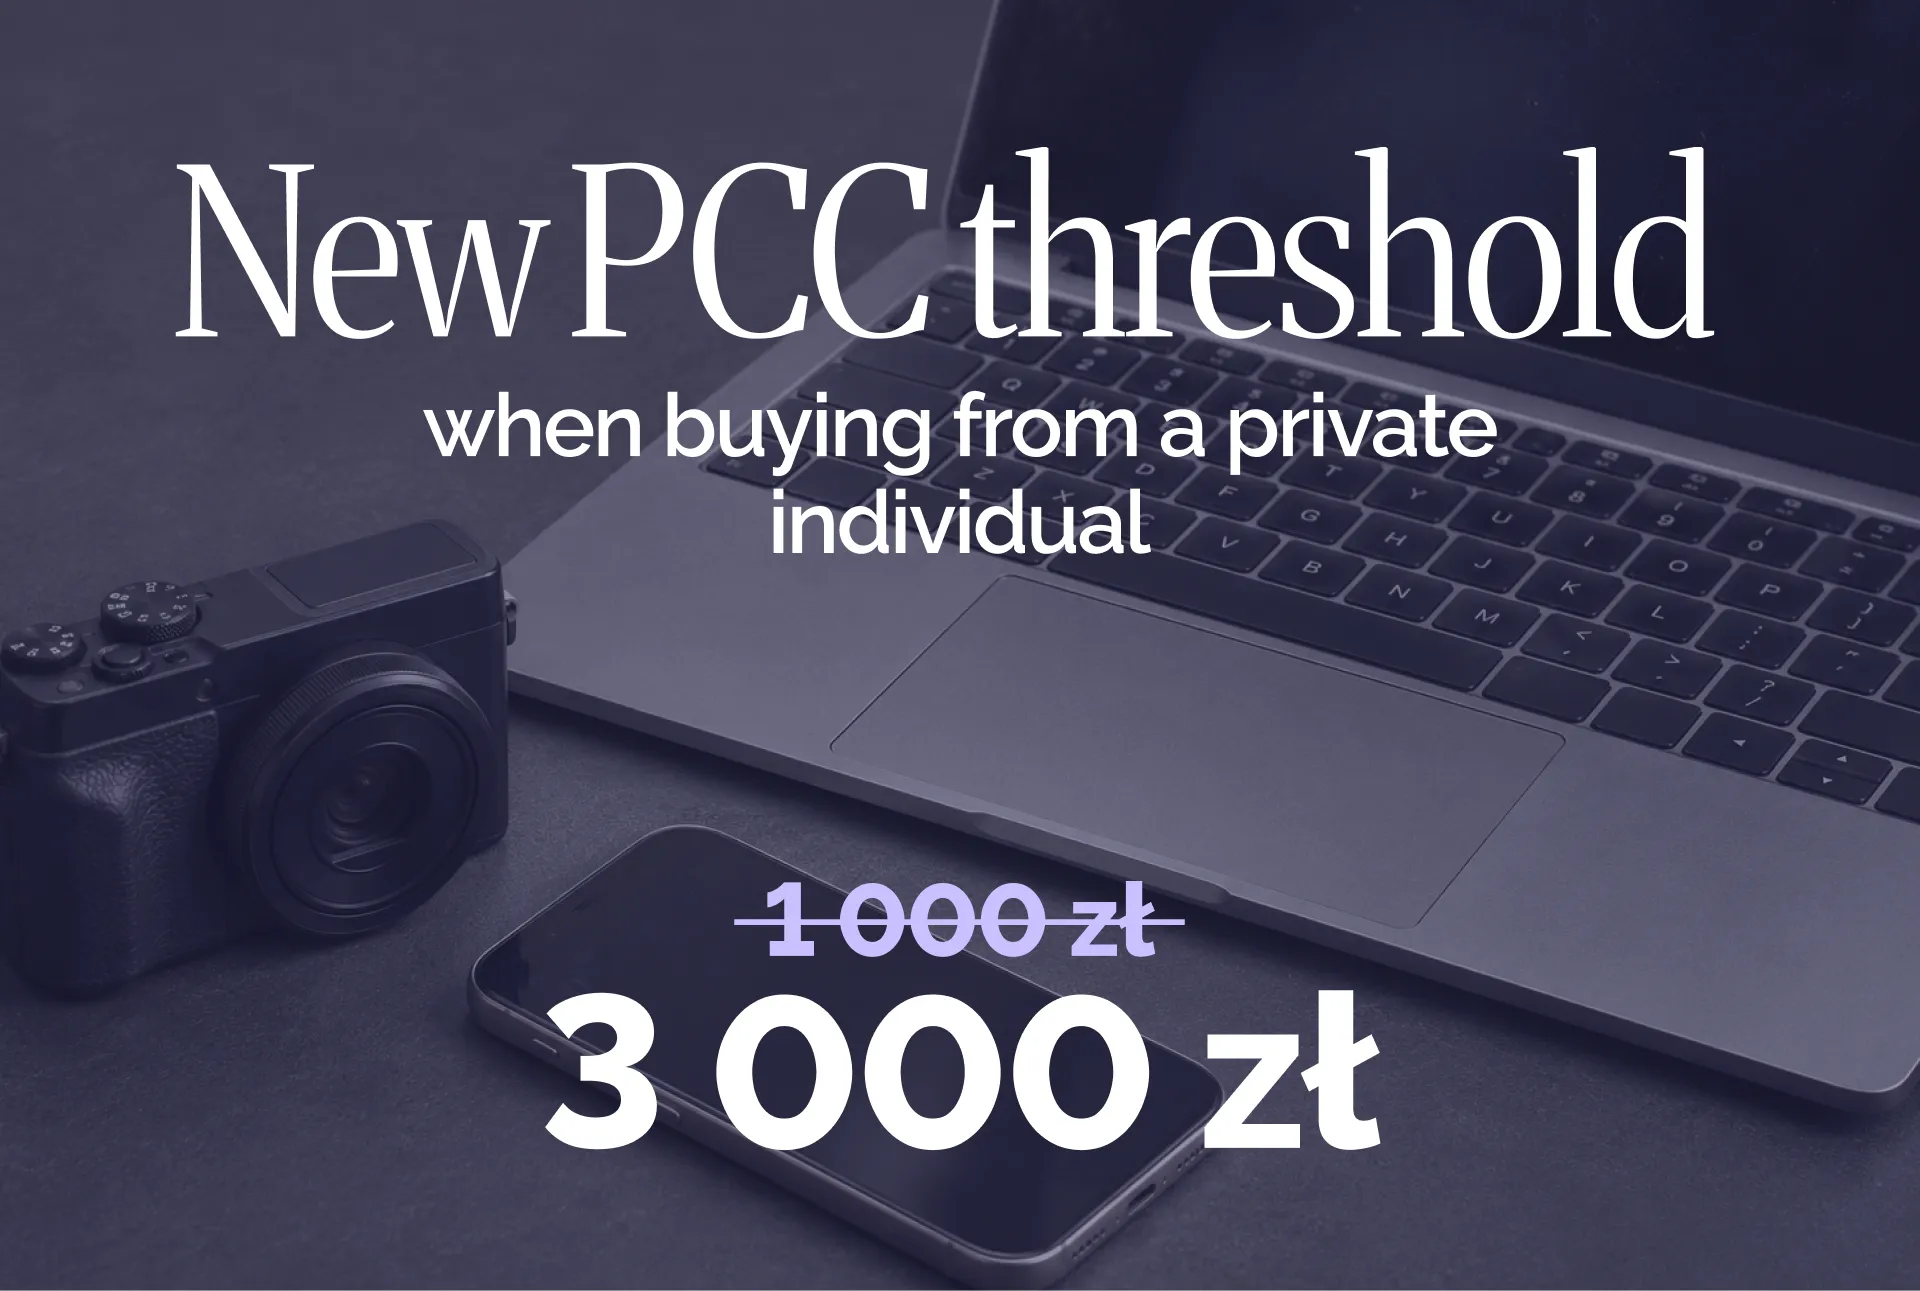
Since 3 November 2026, fewer purchases have been subject to this tax. The exemption threshold for the sale of movable property has increased from PLN 1,000 to PLN 3,000.
When Does PCC Apply to a Purchase?
PCC is the Polish Tax on Civil Law Transactions (podatek od czynności cywilnoprawnych). It applies to certain transactions concluded under civil law agreements.
In the case of purchases, PCC most commonly concerns a contract for the sale of movable property. This may include a car, computer, phone, bicycle, furniture, household appliances, tools, or business equipment.
The obligation usually arises when an item is purchased from another private individual and the sale is not subject to VAT. Examples include a car found through a classified advertisement, a laptop purchased on OLX, or furniture bought directly from its previous owner.
PCC is a one-off tax paid by the buyer.
A standard purchase from a shop or business, documented by an invoice, is generally not subject to PCC. Such sales are usually subject to VAT or exempt from VAT under the relevant rules. The new threshold is therefore most relevant to sales agreements concluded between private individuals.
The New Threshold from 3 November
Until 2 November 2026, the PCC exemption applied when the market value of the item did not exceed PLN 1,000. The threshold is now PLN 3,000.
Until 2 November 2026: exemption up to PLN 1,000
From 3 November 2026: exemption up to PLN 3,000
Above PLN 3,000: PCC is 2% of the full market value
If an item is worth exactly PLN 3,000, the buyer does not have to pay PCC or submit a PCC-3 form.
Once the threshold is exceeded, the tax is calculated on the item’s full market value, not only on the amount above PLN 3,000. For example, PCC on a laptop worth PLN 3,500 is PLN 70:
PLN 3,500 × 2% = PLN 70
The previous PLN 1,000 threshold still applies to contracts concluded no later than 2 November 2026. What matters is the date on which the contract was signed, rather than the date of payment or the date on which the item was handed over.
The change applies specifically to the sale of movable property. It does not alter the PCC rules for real estate, loans, company agreements, or other types of transactions.
The Contract Price Is Not Always Decisive
PCC is calculated based on the item’s market value. This may differ from the price stated in the contract.
For example, if a car with a market value of approximately PLN 20,000 is sold for PLN 15,000 and its condition does not justify the difference, the tax office may question the declared amount and ask the buyer to correct the tax base.
The market value is assessed using factors such as the make and model, year of manufacture, technical condition, level of wear, and prices of comparable items.
If the lower price is due to damage or significant wear, it is worth keeping the original listing, photographs, or messages exchanged with the seller. These can help explain why the purchase price was below the usual market level.
How to File and Pay PCC
If the market value of the purchase exceeds PLN 3,000 and the transaction is subject to PCC, the buyer has 14 days from the date of the contract to:
- calculate the tax at the 2% rate;
- submit the PCC-3 form;
- pay the tax to the appropriate tax office account.
The form can be submitted online through e-Urząd Skarbowy or the e-Deklaracje system. There is no need to wait for a notice from the tax office — the buyer is responsible for calculating the tax and meeting the deadline.
If the value of the item does not exceed PLN 3,000 and the exemption applies, no PCC-3 form is required.
Purchases for a Sole Proprietorship
The same rules apply when a business owner purchases a car, equipment, tools, or other assets from a private individual for a Polish sole proprietorship, known as a JDG.
Using the item for business purposes does not in itself remove the PCC obligation. If its market value exceeds PLN 3,000 and the sale is not subject to VAT, the buyer may need to submit a PCC-3 form and pay the tax.
The sales agreement and proof of payment should be provided to the accountant. If PCC has been paid, the accountant will also need the submitted form and payment confirmation. How the purchase is recorded will depend on the type and value of the asset.
If you are buying equipment or other assets for your JDG and are unsure whether PCC applies, ELP Office can review the documents and explain what steps are required.
Legal basis: Act of 18 September 2026, Journal of Laws 2026, item 1354
This material is provided for informational purposes only and does not constitute individual tax or legal advice.