
Get a Free Consultation
Fill out the form below, and we will get back to you shortly to answer your questions.
Fill out the form below, and we will get back to you shortly to answer your questions.

The main restriction concerns JDG owners from countries outside the European Union, the European Economic Area and Switzerland.
If such an entrepreneur does not have a permanent place of residence in Poland, they generally cannot:
A business address registered in CEIDG or a temporary residence registration does not replace the entrepreneur’s permanent place of residence.
In practice, this means that such a JDG owner can hire a Polish citizen or a foreign national who already has the right to work without any additional procedure on the employer’s side. If one of the procedures listed above is required, completing the employment formalities will most likely not be possible.
Different rules apply to entrepreneurs from the EU, EEA and Switzerland, so their status should be assessed separately.
Additional work authorisation is generally not required for citizens of Poland, the EU, the EEA and Switzerland.
Among citizens of other countries, the right to work without a permit may apply, for example, to:
This is not a complete list. In each case, you should check the exact basis on which the person is staying and working in Poland and whether their documents will remain valid on the date they start work.
There is an additional point to consider when hiring students. A student ID card alone does not prove that a person has the right to work without a permit.
Since 1 July 2026, the exemption applies if the person:
Before signing the contract, it is advisable to request a current certificate from the university confirming the form of study. Part-time, evening or other non-full-time studies do not in themselves exempt the student from the work authorisation procedure.
A notification procedure is often used when hiring Ukrainian citizens.
If the person benefits from temporary protection and has active PESEL UKR status, the employer must submit a notification through praca.gov.pl. The notification must be submitted within seven days of the employee’s start date.
Student status does not remove the obligation to submit the notification. The person therefore cannot be hired solely on the basis of a certificate from their university.
The notification procedure also temporarily applies to Ukrainian citizens who do not benefit from temporary protection but are staying in Poland legally on another basis. The transitional period for these individuals remains in effect until 4 March 2029.
For example, suppose the JDG owner is a Belarusian citizen holding a temporary residence permit, while the future employee is a Ukrainian citizen with PESEL UKR status. A notification is required for the employee to work legally. If the entrepreneur does not have a permanent place of residence in Poland and therefore cannot submit the notification to the relevant district labour office (powiatowy urząd pracy), the employment cannot be completed legally.
Start with two questions: what status does the JDG owner have, and on what basis is the future employee allowed to work in Poland?
If the entrepreneur is a citizen of a country outside the EU, EEA or Switzerland, you should check the basis of their stay and whether they have a permanent place of residence in Poland.
For the future employee, you should verify:
Before the employee starts work, you must obtain documents confirming their legal stay and right to work and retain copies of those documents.
A residence card, student ID or verbal assurance from the employee is not sufficient on its own. If there is any uncertainty about the person’s right to work, it is better to verify it before signing the contract rather than after they have started working.
If you run a JDG in Poland and plan to hire a foreign national, ELP Office can help you review the documents and determine which steps need to be completed before the employee starts work.
This material is provided for informational purposes only and does not constitute individual legal advice.
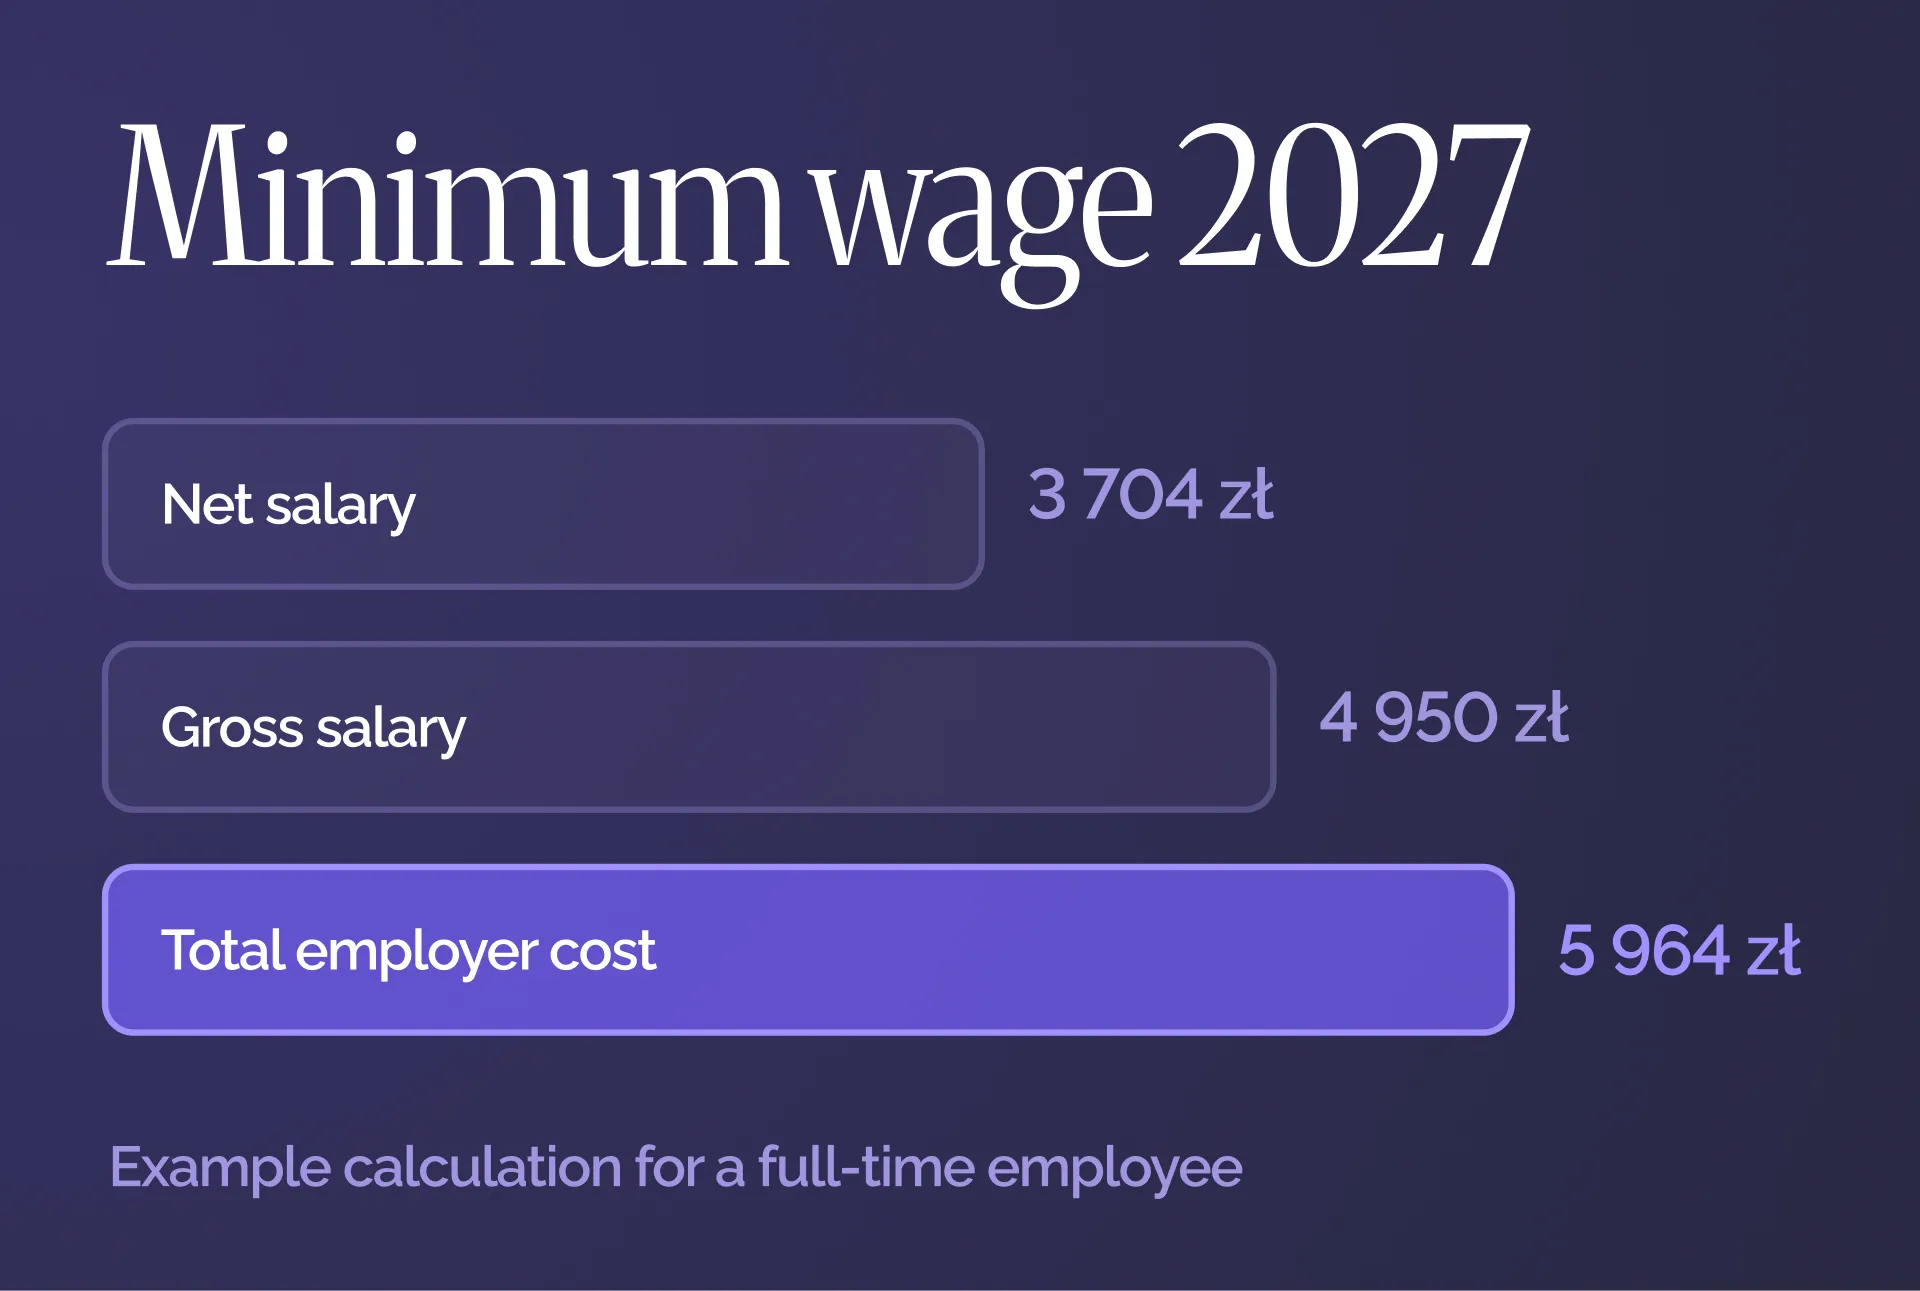
Only one increase is planned for 2027, effective from 1 January. The approved regulation does not provide for a second increase in July.
The amount of PLN 4,950 gross applies to employees working full-time under an employment contract (umowa o pracę).
For part-time employees, the minimum wage is calculated proportionally to their working time.
The same rules apply to Polish citizens and foreign nationals working in Poland. An employee’s nationality does not allow an employer to set their salary below the statutory minimum.
The minimum wage does not necessarily have to be equal to the basic salary specified in the employment contract.
When determining whether the statutory minimum has been met, the total value of all salary components that may legally be included in the minimum wage is taken into account. These may include certain bonuses and allowances.
The following payments are not included in the minimum wage:
Employers should therefore review not only the employee’s total payment but also the structure of their remuneration.
The net amount depends on the employee’s age, tax reliefs, submission of the PIT-2 form, participation in PPK, tax-deductible costs and other individual circumstances.
Under a standard calculation for an employee over the age of 26 who:
a salary of PLN 4,950 gross will amount to approximately PLN 3,703.93 net.
For comparison, with the 2026 minimum wage of PLN 4,806 gross, the standard net payment is approximately PLN 3,605.85.
This means that, under a standard calculation, the employee will receive approximately PLN 98 net more per month.
This is an estimated calculation. The actual payment may differ depending on the employee’s individual circumstances.
The employer’s costs are not limited to the employee’s gross salary. The employer also finances its share of ZUS contributions, as well as contributions to the Labour Fund and the Guaranteed Employee Benefits Fund.
Assuming a standard accident insurance rate of 1.67% and excluding PPK, the estimated calculation is as follows:
The total cost of employing one person receiving the minimum wage will increase by approximately PLN 173 per month, or around PLN 2,077 per year.
Actual costs may differ, for example, due to a different accident insurance rate, the employee’s participation in PPK or the employer’s exemption from certain contributions.
From 1 January 2027, the minimum hourly rate for mandate contracts (umowa zlecenie) and certain service agreements will amount to:
PLN 32.30 gross per hour.
This is a gross, not net, amount. The amount received by the contractor depends, among other things, on their age, student status, other social insurance titles and applicable tax reliefs.
The minimum hourly rate applies not only when an hourly payment is explicitly stated in the contract. If the parties agree on a monthly or fixed amount, the payment divided by the number of hours worked must also not be lower than PLN 32.30 gross per hour.
A mandate contract must specify how the number of hours worked will be confirmed. This may include:
If the contract is concluded for a period longer than one month, remuneration calculated in accordance with the minimum hourly rate must be paid at least once a month.
The minimum hourly rate may also apply to certain sole proprietors if they perform the services personally and do not employ workers or engage other contractors.
Exceptions apply to certain contracts. For example, the minimum hourly rate may not apply if the contractor independently decides where and when the service is provided and receives remuneration based exclusively on commission. All statutory conditions must be met simultaneously for the exception to apply.
Employers and clients engaging contractors should take the following steps in advance:
If a contract specifies a fixed amount below the new statutory minimum, a written amendment to the remuneration terms will generally be required.
If the contract instead provides for payment of the current statutory minimum wage without specifying a fixed amount, the salary will change automatically together with the rate established by law. Nevertheless, the company’s payroll system and documentation should still be reviewed.
The minimum wage affects more than employee salaries. It also determines certain contributions and limits applicable to business owners.
Business owners using preferential social insurance contributions during their first 24 months calculate them based on an amount not lower than 30% of the minimum wage.
In 2027, the minimum contribution base will amount to:
PLN 4,950 × 30% = PLN 1,485.
At the currently applicable rates, the estimated amount of social insurance contributions, including voluntary sickness insurance, will be approximately PLN 469.85 per month, excluding the health insurance contribution.
The final contribution amounts for 2027 should be checked again after ZUS publishes its official tables.
The minimum contribution base of PLN 1,485 will also be relevant when determining the lower contribution threshold under the Mały ZUS Plus scheme.
Standard ZUS social insurance contributions without reliefs are calculated using a different basis — the projected average salary. Their amount therefore cannot be determined solely on the basis of the new minimum wage.
Under the rules applicable on the publication date of this article, the minimum health insurance contribution for business owners taxed under the progressive tax scale or flat-rate income tax is calculated as 9% of the minimum wage.
If the rules remain unchanged, from the beginning of the new contribution year in February 2027, the minimum health insurance contribution will amount to:
PLN 4,950 × 9% = PLN 445.50 per month.
For businesses using the lump-sum tax on registered revenue (ryczałt), the health insurance contribution is calculated according to different rules and depends on annual revenue and the average salary in the enterprise sector.
The quarterly revenue limit for unregistered business activity (działalność nierejestrowana) is equal to 225% of the minimum wage.
With a minimum wage of PLN 4,950, the limit in 2027 will amount to:
PLN 11,137.50 in revenue per quarter.
Once the applicable limit is exceeded, the business must be registered in CEIDG within the statutory deadline.
The increase in the minimum wage will also affect other calculations, including:
For example, the maximum severance payment calculated as 15 times the minimum wage will amount to PLN 74,250 in 2027.
The exact night work allowance depends on the number of working hours in a particular month and must therefore be calculated separately for each month.
No. The new amount establishes the minimum level of remuneration but does not require employers to increase every salary in the company automatically.
However, employers should review their internal remuneration system if other rates, bonuses or allowances are linked to the minimum wage.
It is a gross rate. The net amount depends on the contractor’s social insurance contributions and tax status.
For example, the calculation will differ for a student under the age of 26 and for a person whose mandate contract is their only title to social insurance.
Yes, but after dividing it by the actual number of hours worked, the remuneration cannot be lower than the statutory minimum hourly rate.
No. The approved regulation introduces the new amounts from 1 January 2027 and does not provide for a second increase during the year.
Yes. A foreign national legally employed in Poland is entitled to the minimum wage on the same terms as a Polish citizen.
In addition, the salary specified in documents related to the employment of a foreign national cannot violate the applicable minimum remuneration requirements.
Although the increase amounts to only 3%, it will affect more than the amount paid directly to employees. Employers must also account for ZUS contributions, hourly rates under mandate contracts and limits linked to the minimum wage.
If you employ staff or work with contractors under mandate contracts, ELP Office can help you verify the calculations, prepare a payroll budget and correctly account for remuneration and contributions in 2027.
Contact us to prepare your company for the new rates in advance.
This material is provided for informational purposes only and does not constitute individual legal, tax or accounting advice. We recommend consulting an appropriate specialist regarding your specific circumstances.
The document’s full name is Certificate of Foreign Status of Beneficial Owner for United States Tax Withholding and Reporting (Individuals).
W-8BEN is intended for individuals and is used to certify their foreign status to a U.S. payer or financial institution.
Where applicable to a particular type of income, a properly completed form also allows the individual to claim benefits provided under an international tax treaty.
Important: you do not submit Form W-8BEN directly to the IRS. It should be provided to the organization that requested it, such as a U.S. client, broker, bank, or payment platform.
The form is commonly requested from people who live in Poland and receive payments connected with the United States. This may include freelancers and owners of sole proprietorships, known in Poland as JDG, who work with U.S. clients; authors and digital content creators; recipients of royalties; investors holding U.S. securities; and users of certain international platforms.
However, the reason for completing the form will depend on the type of income received.
Form W-8BEN is not intended for Polish limited liability companies, such as a sp. z o.o., or other legal entities. Foreign companies in similar situations generally use Form W-8BEN-E.
Not necessarily. If an entrepreneur lives and works in Poland and provides services to a U.S. client from Poland, the fact that the client is based in the United States does not usually mean that 30% U.S. tax must be withheld from the payment.
However, the U.S. client may still request Form W-8BEN to confirm that the contractor is a foreign beneficial owner of the income.
The rules may be different if the work is physically performed in the United States or if the payment concerns another type of income, such as dividends or royalties. In such cases, the type of income, tax residency, and the provisions of the tax treaty between Poland and the United States must be considered.
There is therefore no universal rule that “W-8BEN reduces the tax rate from 30% to 15%.” The applicable rate and tax treatment depend on the specific circumstances.
The form consists of three parts: identification of the beneficial owner, a claim for tax treaty benefits, and certification of the information provided.
You can download the form from the official IRS website: https://www.irs.gov/pub/irs-pdf/fw8ben.pdf
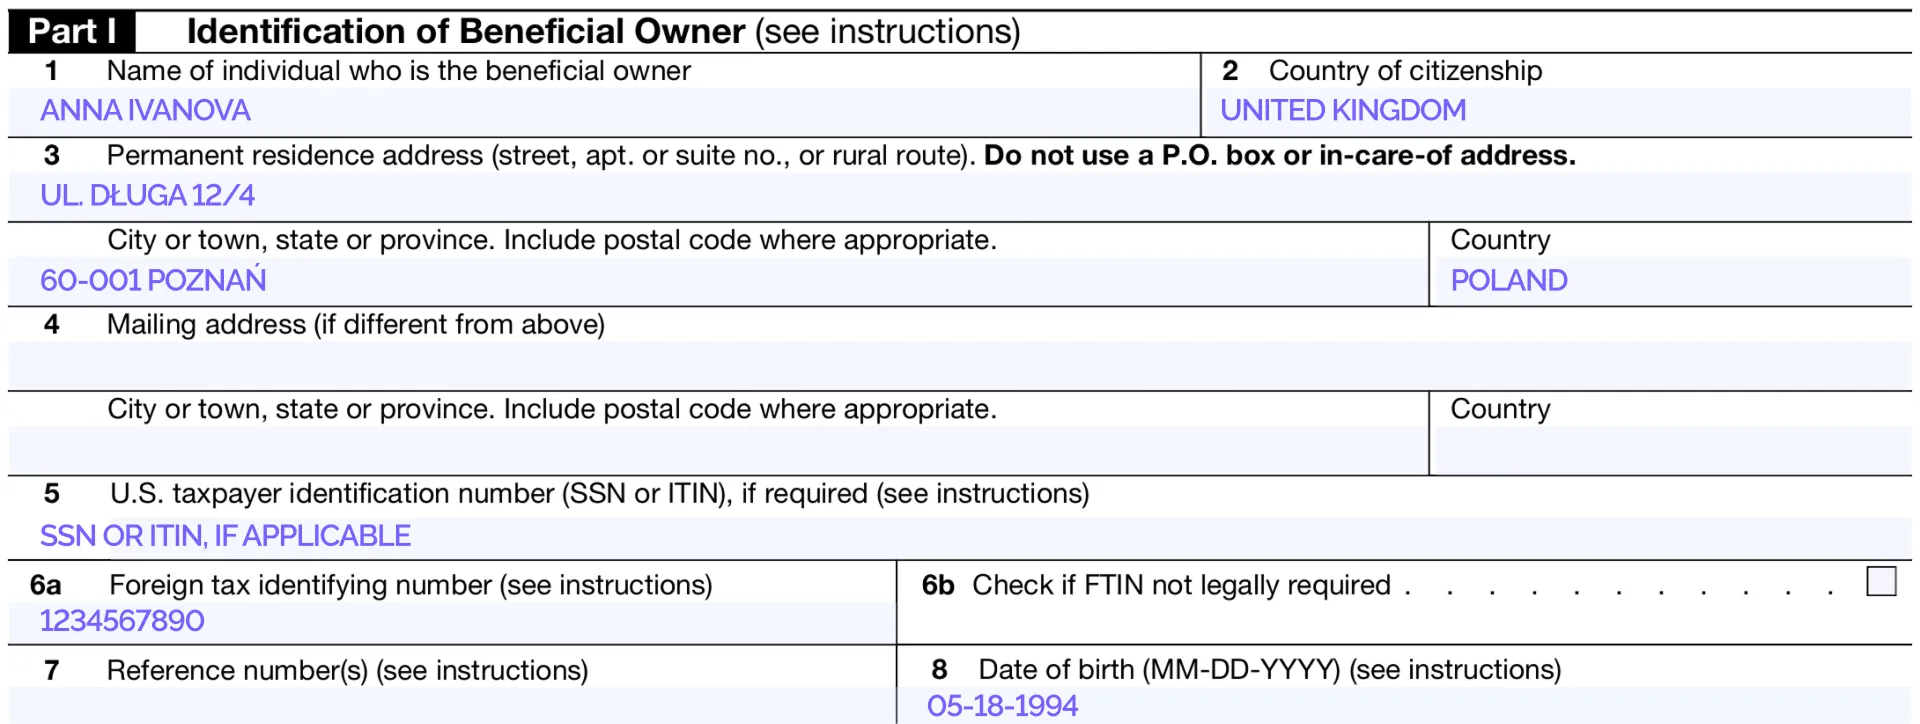
Line 1 — Name of individual who is the beneficial owner
Enter your first and last name.
Line 2 — Country of citizenship
Enter your country of citizenship.
Line 3 — Permanent residence address
Enter your permanent residence address in the country where you are a tax resident. Do not use a P.O. box or an address used only for receiving correspondence.
Line 4 — Mailing address
Complete this field if your mailing address is different from the address entered in Line 3.
Line 5 — U.S. taxpayer identification number
Enter your U.S. SSN or ITIN if you have one and it is required in your situation.
In many typical cases, a Polish entrepreneur working from Poland does not need to obtain an ITIN specifically for this purpose. However, the requirements depend on the type of income and the tax treaty benefit being claimed.
Line 6a — Foreign tax identifying number
Enter your foreign tax identification number, or FTIN.
In Poland, the relevant identifier may be a NIP or PESEL number. An owner of a JDG should use their NIP. PESEL is primarily used as a tax identifier by individuals who do not conduct business activity and do not fall into another category of taxpayers required to use NIP.
Line 6b — FTIN not legally required
Check this box if the law of your country of tax residence does not require you to have a foreign tax identification number. If you have a Polish NIP or PESEL number, this box is generally left unchecked.
Line 7 — Reference number
This field is optional. You may enter an account number, client number, or another identifier if requested by the client or platform.
Line 8 — Date of birth
Enter your date of birth in MM-DD-YYYY format. For example, May 18, 1994 should be entered as 05-18-1994.
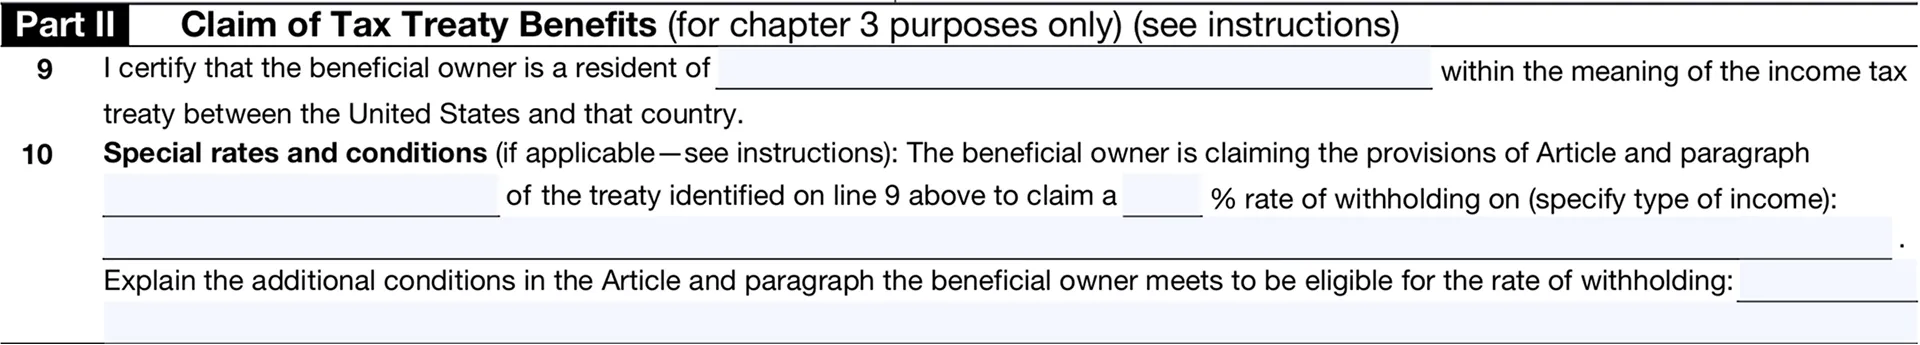
Complete this part if you are claiming benefits under a tax treaty between the United States and your country of tax residence.
Line 9 — enter the country in which you are a tax resident for the purposes of the treaty. If you are a tax resident of Poland, enter Poland.
Line 10 is not always required. Complete it if claiming a particular benefit requires you to specify the relevant tax treaty article, type of income, applicable rate, or fulfillment of additional conditions.
Do not copy information into Line 10 from someone else’s example. The content of this field depends on the type of income and the specific treaty benefit you are claiming.
If you are not claiming tax treaty benefits, you may leave Part II blank. Form W-8BEN can still be used to certify your foreign status. The IRS explicitly states that the form should be provided to the payer regardless of whether the individual is claiming a reduced rate of withholding or an exemption.
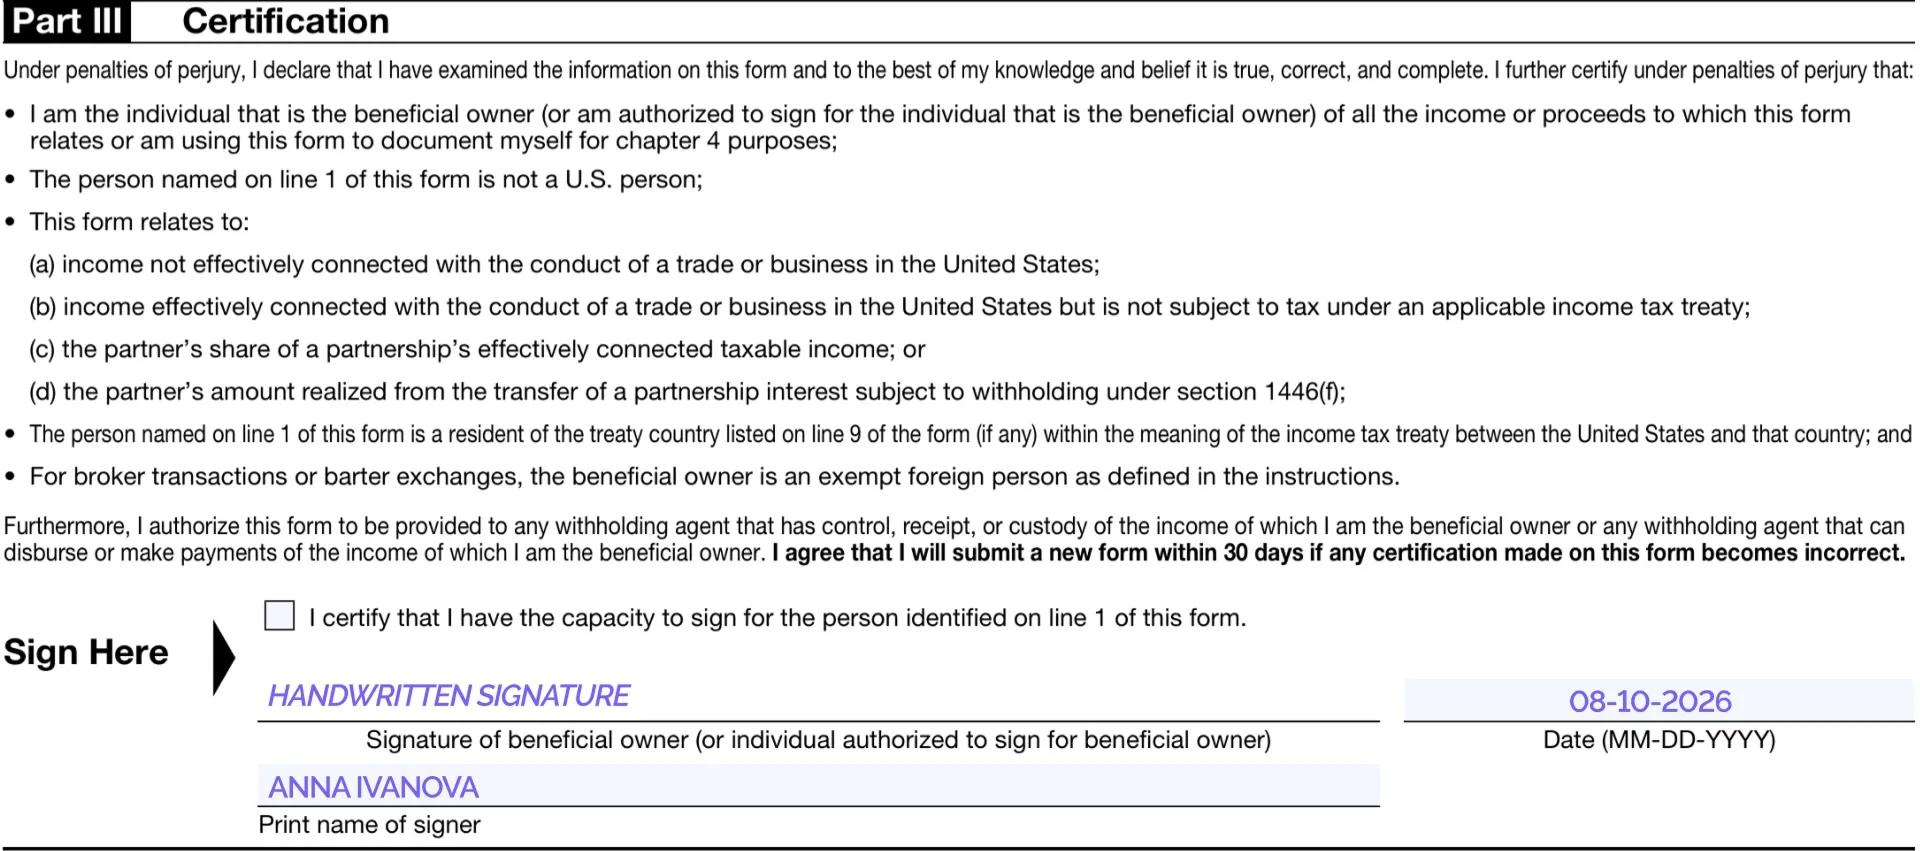
In the final part, you certify that the information provided on the form is correct and complete.
If you are completing Form W-8BEN yourself, you must provide:
Signature of beneficial owner — sign the form. If you are completing a paper form, provide a handwritten signature.
Date — enter the date in MM-DD-YYYY format.
Print name of signer — print the first and last name of the person signing the form.
If the form is signed by an authorized representative, that person must have the appropriate authority and check the box stating, “I certify that I have the capacity to sign…”. Where required, a power of attorney or a copy of it should be attached to the form.
Important: Form W-8BEN may be signed electronically if the organization receiving the form accepts electronic signatures. Simply typing a name in the Signature field is not sufficient. The electronic signature must make it possible to confirm that the document was genuinely signed by an authorized person.
Form W-8BEN is generally valid from the date it is signed until December 31 of the third calendar year following the year in which it was signed.
For example, if the form is signed in September 2026, it will generally remain valid until December 31, 2029.
If your circumstances change and the information provided on the form becomes incorrect, you must submit a new Form W-8BEN within 30 days. This may be necessary, for example, if your tax residency changes.
One of the most common mistakes is assuming that having a U.S. client automatically means that the payment is U.S.-source income. For services, the IRS generally considers where the work is physically performed.
Another mistake is entering a PESEL number as the Foreign TIN despite operating a JDG. For a Polish entrepreneur, the relevant tax identification number is generally NIP.
Citizenship and tax residency are also commonly confused. Line 2 asks for citizenship, while eligibility for treaty benefits in Part II depends on tax residency.
Another mistake is using Form W-8BEN for a sp. z o.o. or another company that is a legal entity. Form W-8BEN-E is intended for foreign legal entities.
Finally, do not copy a tax treaty article or withholding rate from someone else’s example. Dividends, royalties, and payments for services are subject to different tax rules.
Form W-8BEN primarily concerns U.S. withholding and reporting rules. It does not replace tax reporting in Poland.
If you are a Polish tax resident or operate a JDG in Poland, income received from a foreign client must be properly recorded in your Polish accounts and taxed according to your chosen form of taxation and the nature of the transaction.
If tax was withheld abroad, you must also determine how the rules for eliminating double taxation apply.
Form W-8BEN should therefore not be treated as a “tax return.” It is a document that helps the U.S. payer correctly determine your status and the applicable withholding rules.
A request to complete the form is standard practice and does not mean that you have a tax problem.
Before completing it, check three things: where you are a tax resident, what type of income you receive, and where the work is physically performed.
If you operate a JDG in Poland and are unsure which tax identification number to provide, whether you should complete Part II, or how to account for payments from a U.S. client in your Polish bookkeeping, ELP Office can review your situation and help you handle the accounting correctly.
This material is provided for informational purposes only and does not constitute individual legal, tax, or accounting advice. We recommend consulting an appropriate specialist regarding your particular circumstances.
Wakacje składkowe allows an entrepreneur to receive an exemption from paying their own social contributions for one selected month of the year.
During that month, the entrepreneur:
The exempted contributions are paid from the state budget. Therefore, the month covered by wakacje składkowe is taken into account when future pension and social insurance rights are calculated.
Applications have been accepted since 1 November 2024. The first exemption was available for December 2024. As of July 2026, the main eligibility rules remain largely unchanged. Most updates have concerned the technical structure of the RWS form and the information required for de minimis aid.
Wakacje składkowe should not be confused with zawieszenie działalności. When using the relief, the business continues to operate. When business activity is suspended, the entrepreneur temporarily stops normal commercial activity.
The relief is primarily intended for entrepreneurs operating a jednoosobowa działalność gospodarcza and registered in CEIDG.
A partner in a spółka cywilna may also use the relief, but the application concerns the partner’s personal contributions and must be submitted through their individual payer account.
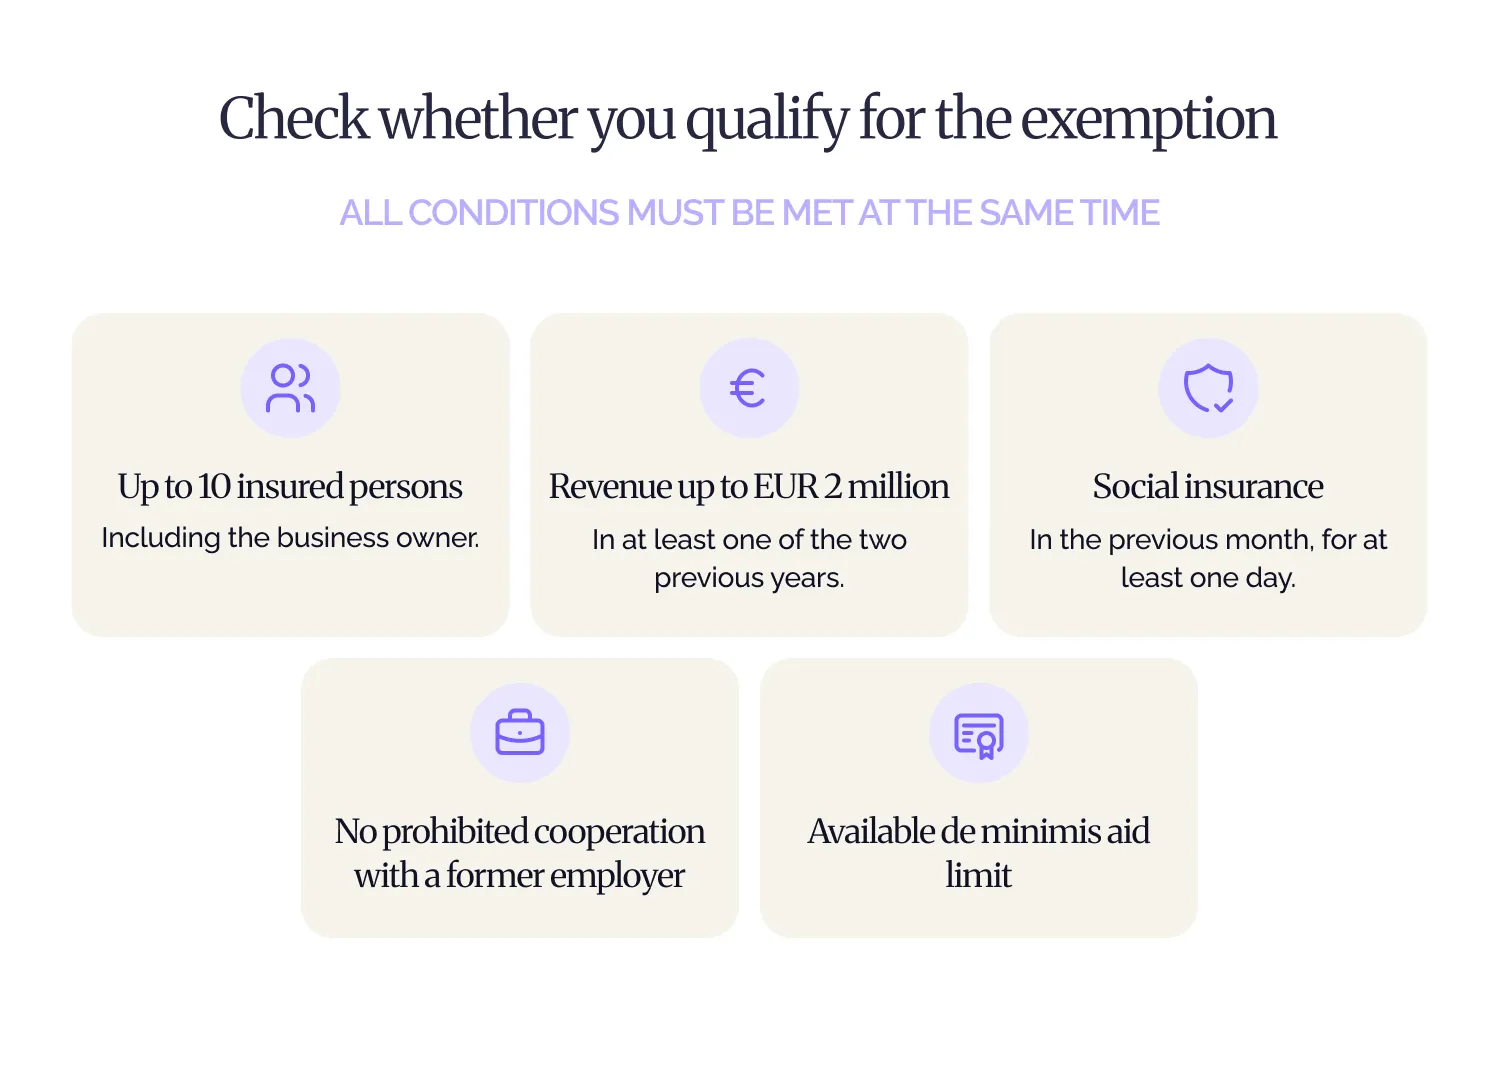
Several conditions must be met at the same time.
In the month preceding the month in which the application is submitted, the entrepreneur must have no more than 10 insured persons registered with ZUS.
The entrepreneur is included in this limit. In a standard situation, this means the entrepreneur and no more than nine other insured persons.
The calculation may include:
A person registered for at least one day during the relevant month may be included. The calculation is not based only on the situation on the final day of the month.
For example, a person working under a short-term umowa zlecenie may still count toward the limit.
Students and pupils under the age of 26 working under an umowa zlecenie who are not subject to ZUS insurance are not included. Other exceptions may also apply, so borderline cases should be checked individually.
The entrepreneur must meet the annual revenue requirement.
The relief is available if, in at least one of the two calendar years preceding the year of the application:
For an application submitted in 2026, the relevant years are 2024 and 2025. It is sufficient to meet the condition in one of those years.
The relief may be unavailable if the entrepreneur provides services to a former employer and performs the same duties that were previously performed under an employment contract in the year the business activity began or in the preceding year.
The cooperation is assessed for:
The actual nature of the work is important, not only the title of the position or the wording of the contract.
Therefore, when moving from an umowa o pracę to B2B cooperation with the same employer, the previous duties should be carefully compared with the current scope of services.
The entrepreneur must have been subject to pension, disability and accident insurance for at least one day in the month preceding the RWS application.
There is no separate minimum period for operating a JDG. However, a newly established business may not always be able to use the relief immediately.
For example, if the JDG was registered on 1 May, the entrepreneur was subject to social insurance in May and submitted the RWS application in June, July may be selected as the exemption month, provided that all other requirements are met.
Wakacje składkowe constitutes de minimis state aid. Before submitting the application, the entrepreneur should verify that the available de minimis aid limit has not been exhausted.
The exemption will not be granted if the entrepreneur:
The relief is not available during ulga na start because the entrepreneur is not subject to the required social insurance during that period.
It may become available after moving to preferencyjne składki or another contribution scheme, provided that the remaining requirements are met.
The exemption applies only to the entrepreneur’s own social contributions.
It may cover pension, disability and accident insurance contributions, as well as voluntary sickness insurance and contributions to Fundusz Pracy and Fundusz Solidarnościowy where applicable.
Voluntary sickness insurance is covered only if the entrepreneur was subject to this insurance for at least one day both in the month of submitting the RWS application and in the preceding month.
The most important limitation is that składka zdrowotna is not covered by wakacje składkowe. It must still be calculated and paid under the standard rules.
Contributions for employees and other insured persons, taxes and previous ZUS arrears also remain payable.

The amount saved depends on the entrepreneur’s social contribution scheme.
Based on the 2026 rates, the estimated exemption amount is shown in the table below.
Składka zdrowotna must be paid separately.
The minimum monthly health contribution for the period from February 2026 to January 2027 is PLN 432.54 where the applicable taxation method and calculation base do not result in a higher amount.
The actual saving will therefore differ between entrepreneurs. It depends on:
The entrepreneur may select one exemption month in each calendar year.
The RWS application must be submitted in the month immediately preceding the selected exemption month.
For example:
The application cannot be submitted retroactively or several months in advance.
For example, to receive the exemption for August, the entrepreneur must submit the application in July. An application submitted in August may only concern September.
This is one of the most important rules. ZUS may leave an application without consideration if it is submitted outside the permitted month.
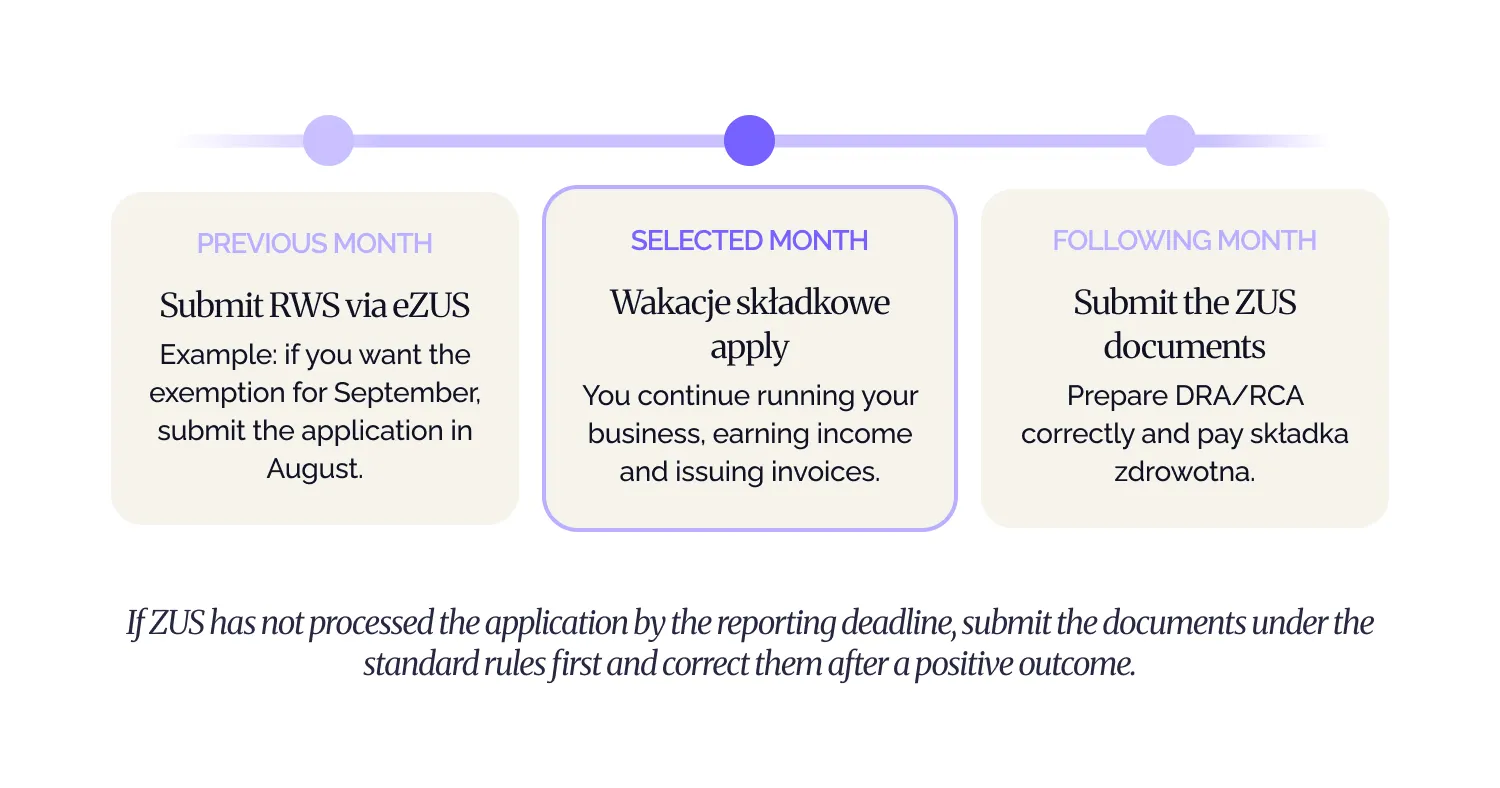
The application must be submitted electronically through the konto płatnika in eZUS.
Before starting, prepare information about any de minimis aid received during the previous three years and check your main PKD code. Official certificates will only be required if you choose to confirm the aid through zaświadczenia.
Log in to eZUS and go to Konto płatnika.
The application must be submitted from the payer profile.
A wspólnik spółki cywilnej submits RWS through their individual konto płatnika, not through the company’s profile.
In the side menu, select Katalog usług.
Then find:
Złóż wniosek o zwolnienie z obowiązku opłacenia składek za wskazany miesiąc (RWS)
Select Przejdź do usługi to open the application.
For the first application, select Wniosek.
The entrepreneur’s details will be loaded automatically. Check them and complete any required fields that are missing.
Until ZUS reviews the application, it may be corrected or withdrawn using:
In the Treść wniosku section, the system automatically displays the month following the month in which the application is submitted.
For example, if the RWS form is completed in August, it will concern September.
The month cannot be changed manually.
On this screen, two matters must be confirmed.
First, confirm that the revenue requirement is met: in at least one of the two preceding calendar years, revenue did not exceed the equivalent of EUR 2 million, or no business revenue was received.
Second, indicate whether de minimis aid was received during the previous three years.
If no aid was received, select:
Nie korzystałem z pomocy publicznej de minimis
If aid was received, select:
Korzystałem z pomocy publicznej de minimis
Then select how the aid will be confirmed:
Select the actual size of the enterprise. For many small JDG businesses, the appropriate option will be mikroprzedsiębiorstwo.
Next, choose the classification version in the Wersja PKD field:
Then select the main activity code corresponding to the information registered in CEIDG.
Until 31 December 2026, the application allows PKD 2007 or PKD 2025. After that date, PKD 2025 will be required.
The form will also ask additional questions concerning:
For a standard JDG that is not linked to other companies, has not undergone a reorganisation and does not operate in these sectors, the usual answer is NIE.
If TAK is selected, the form will request additional information.
If Zaświadczenia was selected in the de minimis section, attach the official certificates confirming the aid received.
If Oświadczenie was selected, the relevant information is completed directly in the application and separate certificates are not required.
At the Podsumowanie stage, open Widok danych dokumentów.
Check:
If an error is found, return to the previous section and correct it.
Select Podpisz i wyślij, choose one of the available signature methods and submit the application.
After submission, the application status and new ZUS messages can be checked in Sprawy płatnika.
A notification about a new document may also be sent to the email address or telephone number registered in eZUS.
Until ZUS reviews the application, it may be supplemented, corrected or withdrawn through the RWS form.
The selected exemption month cannot be changed. In that situation, the application must be withdrawn and a new one submitted within the permitted period.
Once the application has been reviewed, it can no longer be corrected or withdrawn through this procedure.
If ZUS grants the exemption in full, a separate administrative decision may not be issued. Information about the relief will appear in eZUS.
ZUS will issue an administrative decision if it:
Wakacje składkowe exempts the entrepreneur from their own social contributions for the selected month, but it does not remove the obligation to submit settlement documents.
For the exemption month, the entrepreneur must correctly prepare ZUS DRA and, where required, ZUS RCA.
Składka zdrowotna remains payable.
If ZUS has not reviewed the RWS application by the reporting deadline, the entrepreneur should not omit the declaration. The documents should first be submitted under the standard rules and then corrected after the exemption is granted.
It is advisable to inform the accountant in advance about the month selected for wakacje składkowe. This makes it easier to submit the application on time and settle the reporting period correctly.
Wakacje składkowe does not create a break in social insurance.
The contributions for the exemption month are financed by the state and are taken into account when future pension and disability benefits are calculated.
Continuity of social insurance rights is also maintained, provided that the general eligibility requirements for the relevant benefits are met.
This is different from ulga na start, during which social contributions are not paid and the corresponding social insurance rights do not arise.
The social contributions, Fundusz Pracy and Fundusz Solidarnościowy amounts covered by the exemption are not subject to PIT.
At the same time, they cannot be treated as a tax-deductible expense because the entrepreneur did not pay them from their own funds.
Składka zdrowotna is calculated and treated under the standard rules applicable to the entrepreneur’s chosen taxation method.
Wakacje składkowe may be combined with:
The entrepreneur must still meet the general wakacje składkowe requirements.
The relief is not available during ulga na start because the entrepreneur is not subject to the required social insurance during that period.
RWS may only be submitted in the month directly preceding the exemption month. It cannot be submitted retroactively or two months in advance.
Entrepreneurs sometimes count only permanent employees or check the situation only on the last day of the month.
However, a person insured for even one day may be included in the limit.
Składka zdrowotna, employee contributions and taxes remain payable.
Incomplete or incorrect information may result in a request for additional documents, refusal of the relief or its later cancellation.
If ZUS has not reviewed the application by the reporting deadline, the documents must be submitted under the standard rules and corrected later.
Dobrowolne ubezpieczenie chorobowe is covered only if the entrepreneur was subject to it for at least one day in both the month of application and the preceding month.
ZUS assesses the duties actually performed, not only the wording of the contract.
If ZUS later determines that the requirements were not met, the exemption may be cancelled. The entrepreneur may then have to pay the contributions together with interest.
No. During wakacje składkowe, the entrepreneur may continue working, earning income and issuing invoices.
Yes. The exemption does not cover the health contribution.
No. The relief only applies to the entrepreneur’s own contributions.
Yes, provided that the general conditions are met. The saving will be lower because the social contributions are already reduced.
Yes, if the entrepreneur meets both the wakacje składkowe requirements and the requirements of Mały ZUS Plus.
No. During ulga na start, the entrepreneur is not subject to the social insurance required for wakacje składkowe.
No. RWS must be submitted in the month preceding the selected exemption month.
Yes. A separate RWS application must be submitted for the selected month in each calendar year.
Yes, but only until ZUS reviews the application.
No. The exempted contributions are financed by the state, so continuity of social insurance is maintained.
Wakacje składkowe allows an entrepreneur to reduce the cost of their own social contributions once per year without suspending business activity.
However, it is not an automatic “month without ZUS”. To use the relief, the entrepreneur must:
Particular attention should be paid to the application deadline, the insured-person limit and cooperation with a former employer. An error in any of these areas may result in refusal or later cancellation of the relief.
Planning to use wakacje składkowe? ELP Office specialists can help verify the conditions, prepare the RWS application and correctly reflect the exemption in ZUS settlements.
This material is for informational purposes only and does not constitute individual legal, tax, or accounting advice. For guidance concerning your specific situation, we recommend consulting a qualified professional.
e-Doręczenia is the electronic equivalent of a registered letter with proof of delivery. The system can be used to submit applications, receive decisions from public authorities, and retain official proof that documents have been sent and delivered.
An e-Doręczenia address cannot be replaced with a standard company email address. It is a unique technical address registered in the official Electronic Address Database — Baza Adresów Elektronicznych, or BAE.
It may look like this:
AE:PL-12345-67890-ABCDE-12
The address makes it possible to identify the sender and recipient and confirm the date and time when correspondence was transmitted.
Personal and business correspondence use separate addresses. Therefore, even if someone already has a personal e-Doręczenia inbox, they must create a separate business address for their activity registered in CEIDG.
ePUAP has not disappeared completely. However, since 1 January 2026, e-Doręczenia has been the main channel for official electronic correspondence. Other communication methods may still be used where special regulations or a specific electronic service allow them.
The registration deadline depends on the register in which the business is entered and the date of registration.
Sole traders registered in CEIDG before the end of 2024 must therefore activate their address no later than 30 September 2026.
However, it is not always possible to wait until that date. If an entrepreneur changes their CEIDG details after 30 June 2025, the information required to create an e-Doręczenia address becomes a mandatory part of the application.
This may apply, for example, when:
The e-Doręczenia system applies the principle of deemed delivery — fikcja doręczenia.
If correspondence from a public authority is delivered to the inbox of a company or entrepreneur but is not received earlier, it is considered legally delivered on the day following the end of the 14-day period calculated from the date of receipt indicated in the delivery confirmation.
That date is treated as the official date of service. Deadlines for responding, submitting documents, or filing an appeal are calculated according to the rules applicable to the relevant procedure.
As a rule, the absence of an email notification, the owner’s holiday, or irregular inbox checks do not suspend statutory deadlines.
The e-Doręczenia Act does not impose a separate automatic fine solely for failing to have an address. The main risk is missing legally significant correspondence and the deadlines connected with it.
If the recipient does not have an active e-Doręczenia address, a public authority may, where permitted by law, use the Public Hybrid Service — Publiczna Usługa Hybrydowa, or PUH.
The document is transferred electronically to the operator, printed, and delivered to the recipient in paper form.
Once the address has been activated, it is particularly important to monitor incoming messages regularly. Missing a deadline may mean that the entrepreneur does not have enough time to submit documents, respond to a request, or appeal a decision.
In tax proceedings, an authority may impose a kara porządkowa, or procedural fine, in the circumstances listed in Article 262 of the Polish Tax Ordinance. In 2026, the maximum amount is PLN 3,800.
This is not a fine for simply having or not having an e-Doręczenia inbox. It may be imposed for a specific procedural violation, such as failing to comply with a properly delivered request where tax law allows such a penalty.
For a sole trader registered in CEIDG, creating an e-Doręczenia address usually takes little time. Most information is retrieved automatically, and the application can be signed using Profil Zaufany.
The process is similar to creating a personal e-Doręczenia inbox. However, the applicant must select registration of an address specifically for business activity.
Important: a personal e-Doręczenia address and a sole trader’s business address are two separate addresses. Official correspondence relating to an activity registered in CEIDG requires a separate business address.
You will need:
A sole trader may manage the inbox personally. An accountant or another user can be added later, after the address has been activated.
Log in to Konto Przedsiębiorcy on Biznes.gov.pl and open the service for creating an e-Doręczenia address.

On the start screen, click:
Złóż wniosek — Submit an application.

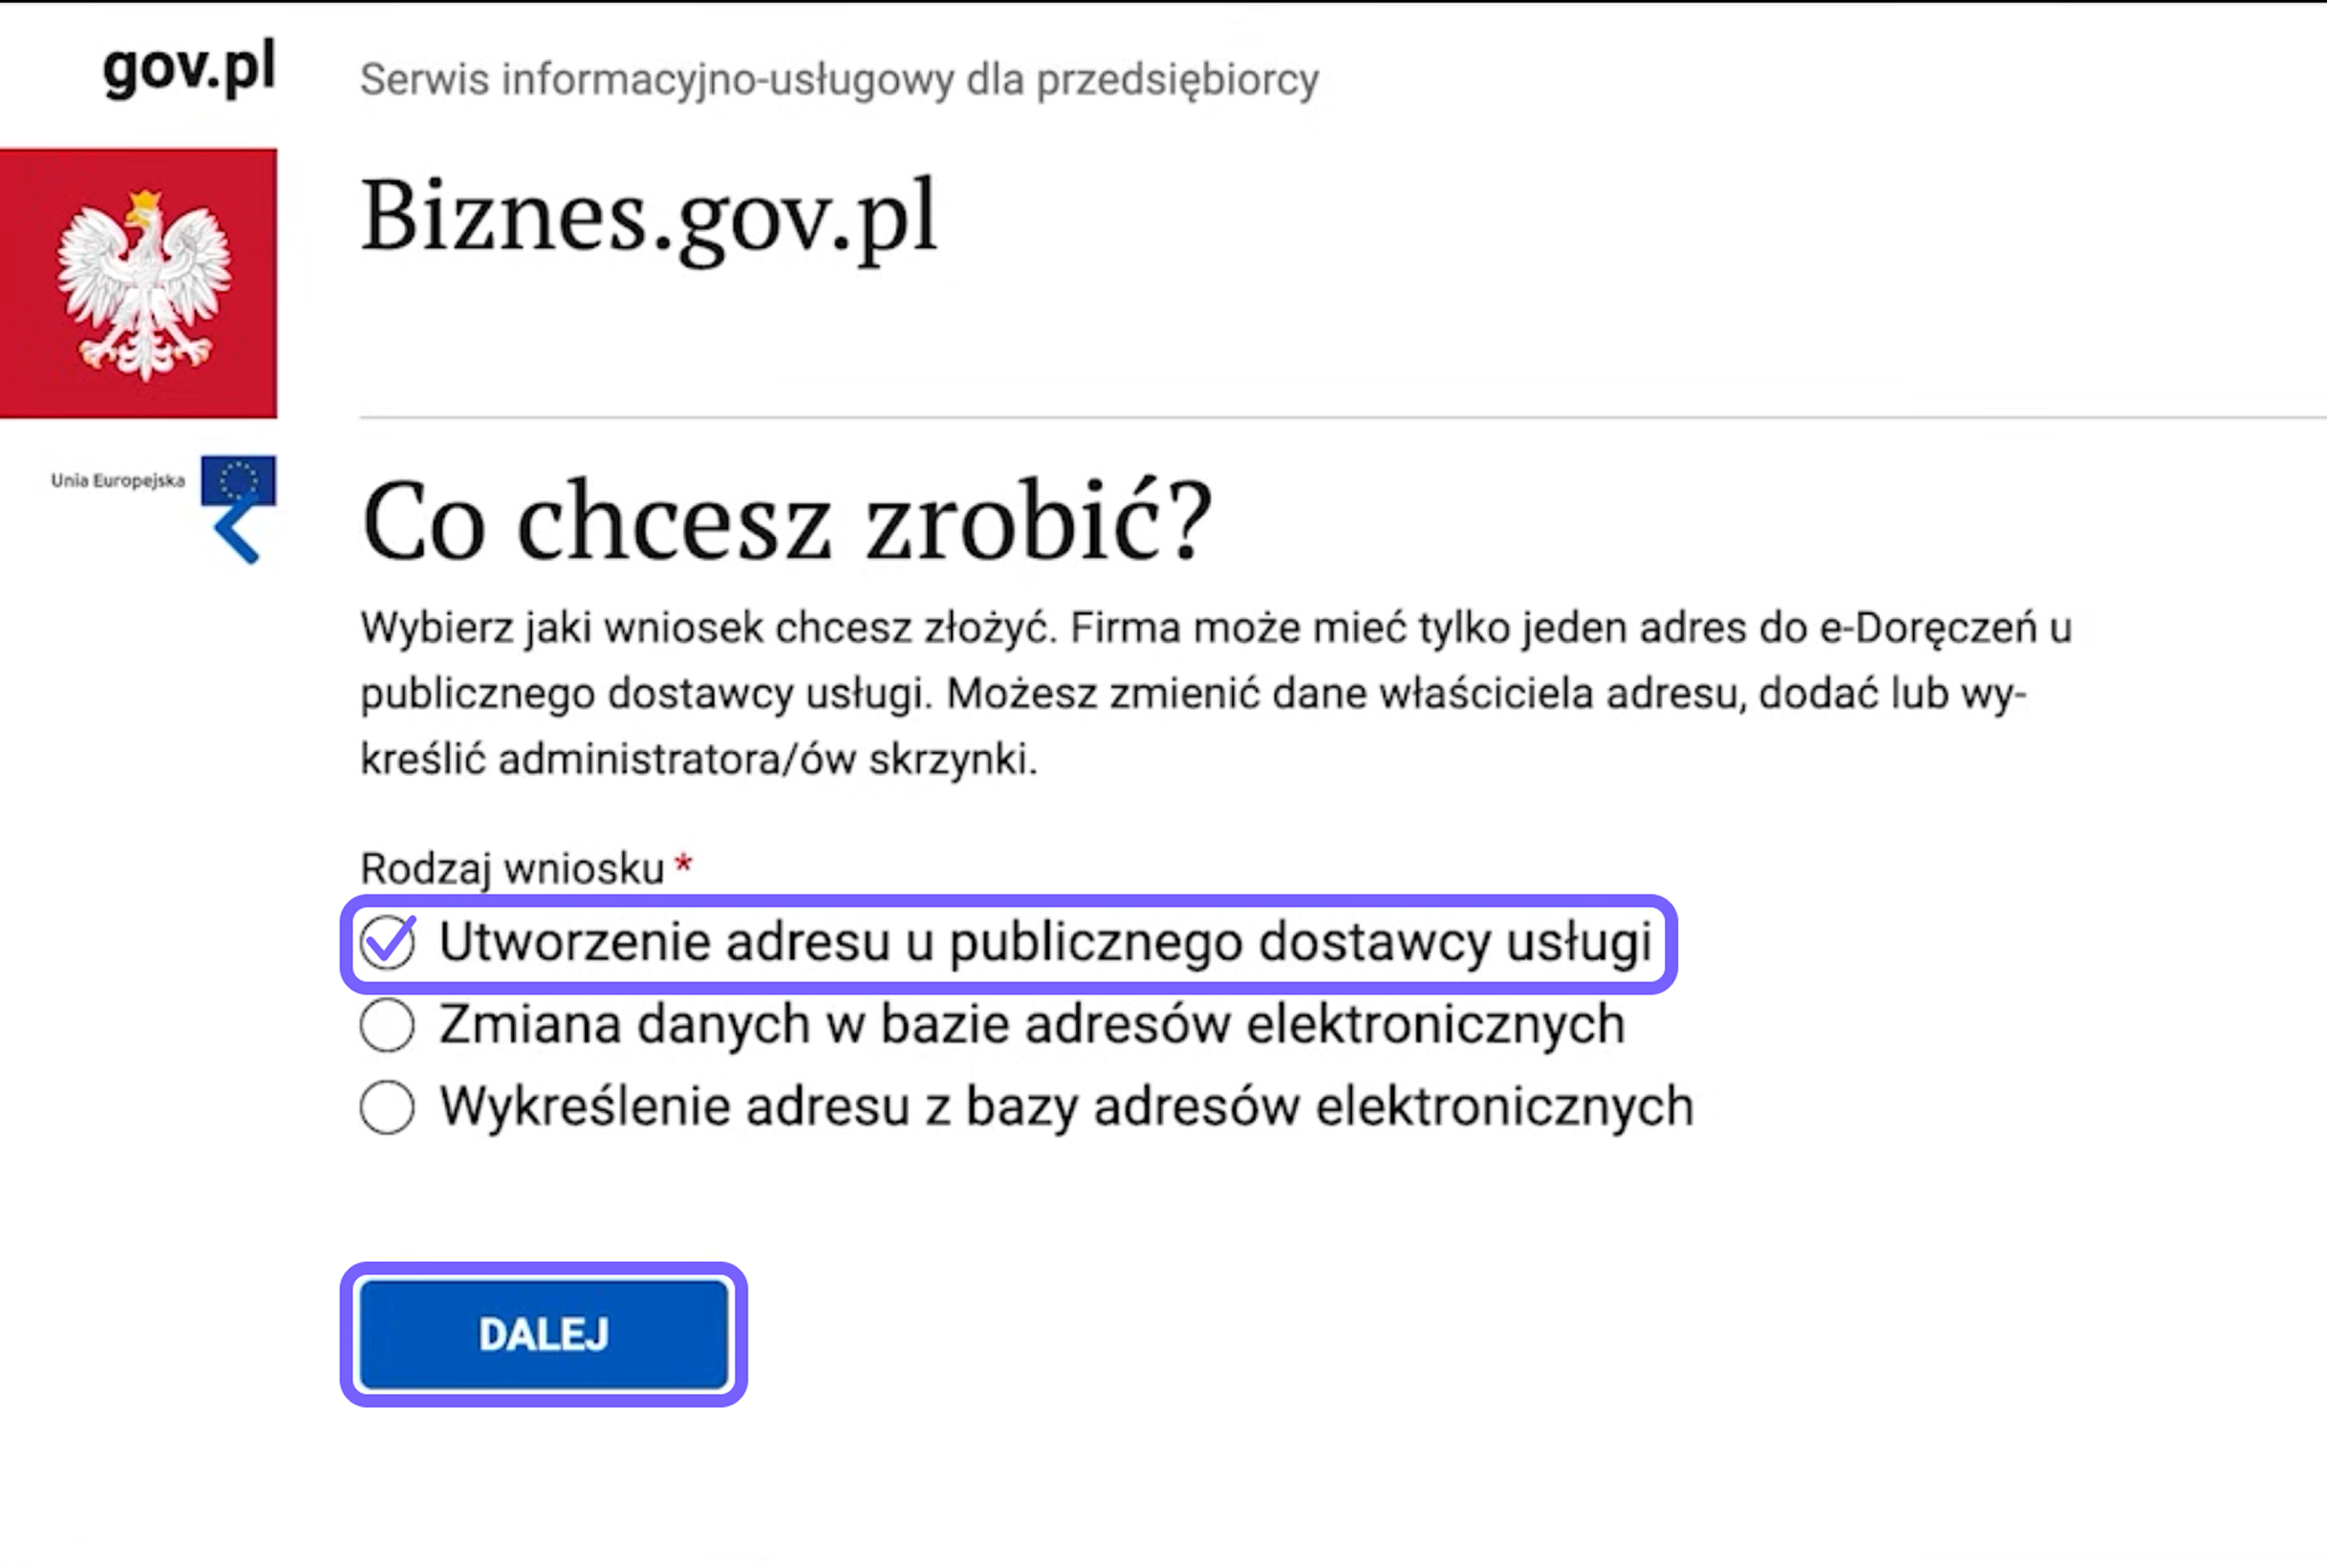
The system will ask how you want to create the address. Select:
Utworzenie adresu u publicznego dostawcy usługi — Create an address with the public service provider.
This is the free option intended for official correspondence with public authorities.
Click Dalej — Next.
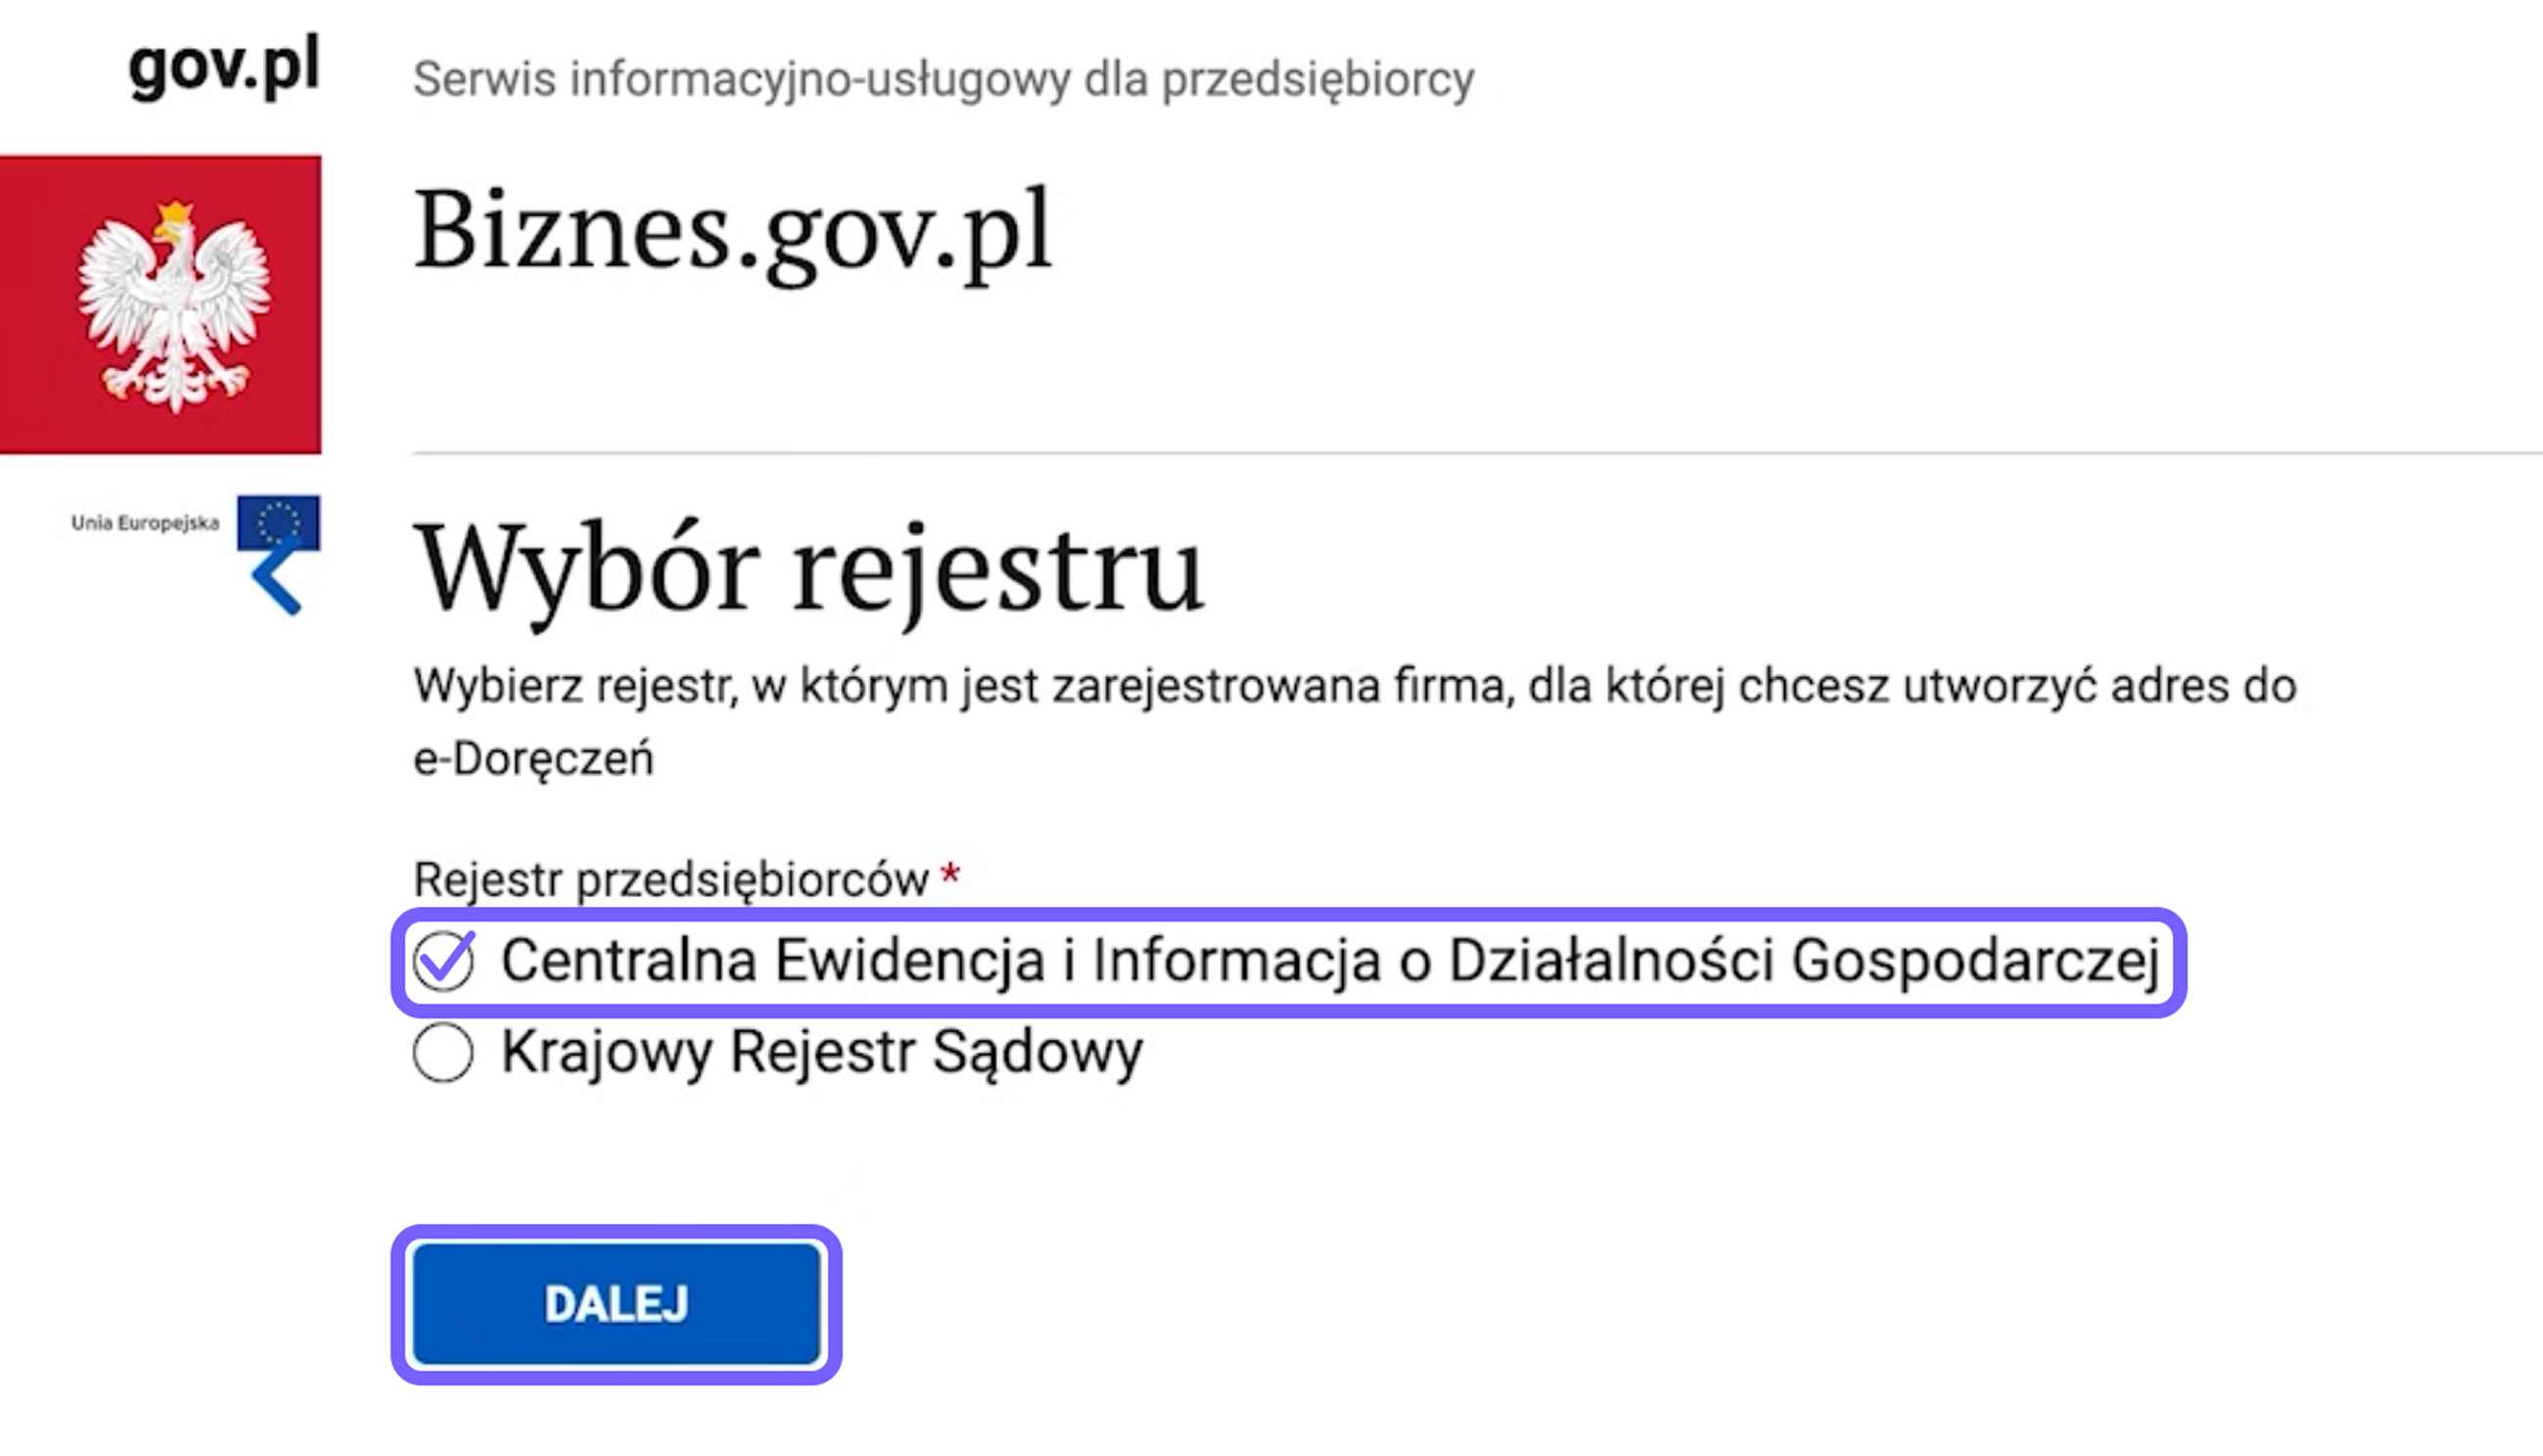
On the next screen, select:
Centralna Ewidencja i Informacja o Działalności Gospodarczej — Central Register and Information on Economic Activity, CEIDG.
This option is intended for sole traders operating as a jednoosobowa działalność gospodarcza, or JDG.
Click Dalej — Next.
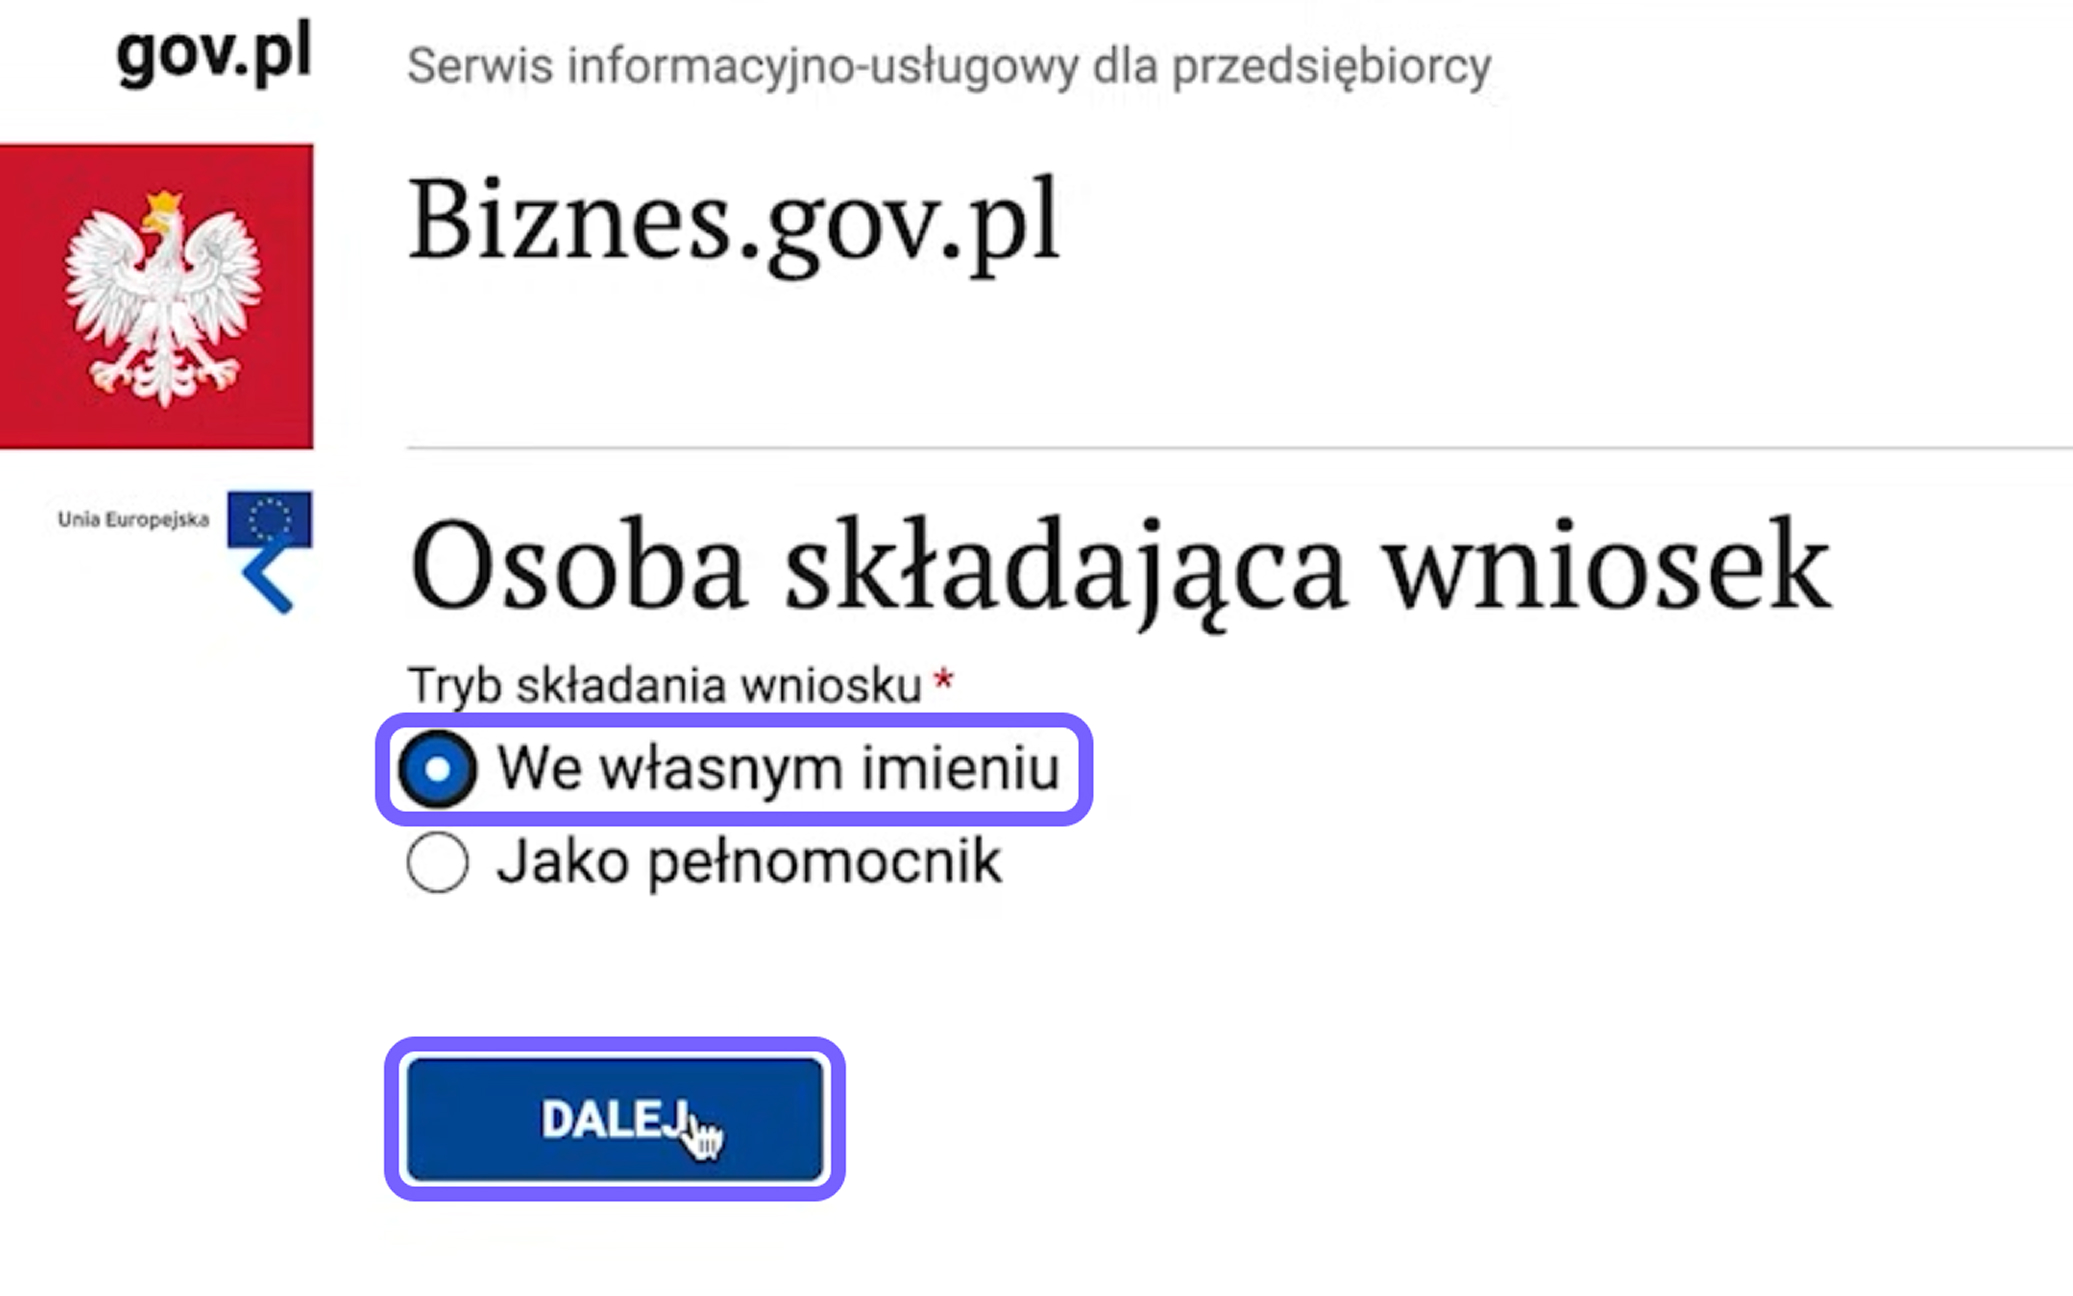
When creating an address for your own business activity, select:
We własnym imieniu — On my own behalf.
Then click Dalej — Next.
If the application is being submitted by an authorised representative, the process and required documents may be different.
Some information will be retrieved automatically from CEIDG. Check that the entrepreneur’s details are correct and complete any missing fields.
In particular, verify:
Technical notifications will be sent to the email address provided, including information about the application status and instructions for activating the inbox.
A regular email address does not replace e-Doręczenia. It is used only for notifications.
After checking the information, click Dalej — Next.
The system will ask whether you want to appoint an inbox administrator.
If the entrepreneur intends to manage the inbox personally, they may select the option without appointing a separate administrator.
If another person will manage access and settings, their details must be provided. The administrator may, among other things:
A separate administrator is not mandatory for a standard JDG. An accountant can be added as a user after the inbox has been activated.
Click Dalej — Next.
Read the terms governing the service and confirm your acceptance.
Select the relevant box next to Regulamin — Terms and Conditions, then click Dalej — Next.
The next screen will display the required declarations — oświadczenia.
Read them and select the necessary boxes to confirm that the information provided is correct.
Then click Dalej — Next.
The system will automatically display the authority responsible for processing the application.
Check the information and click Dalej — Next. In most cases, you do not need to search for or select the authority manually.
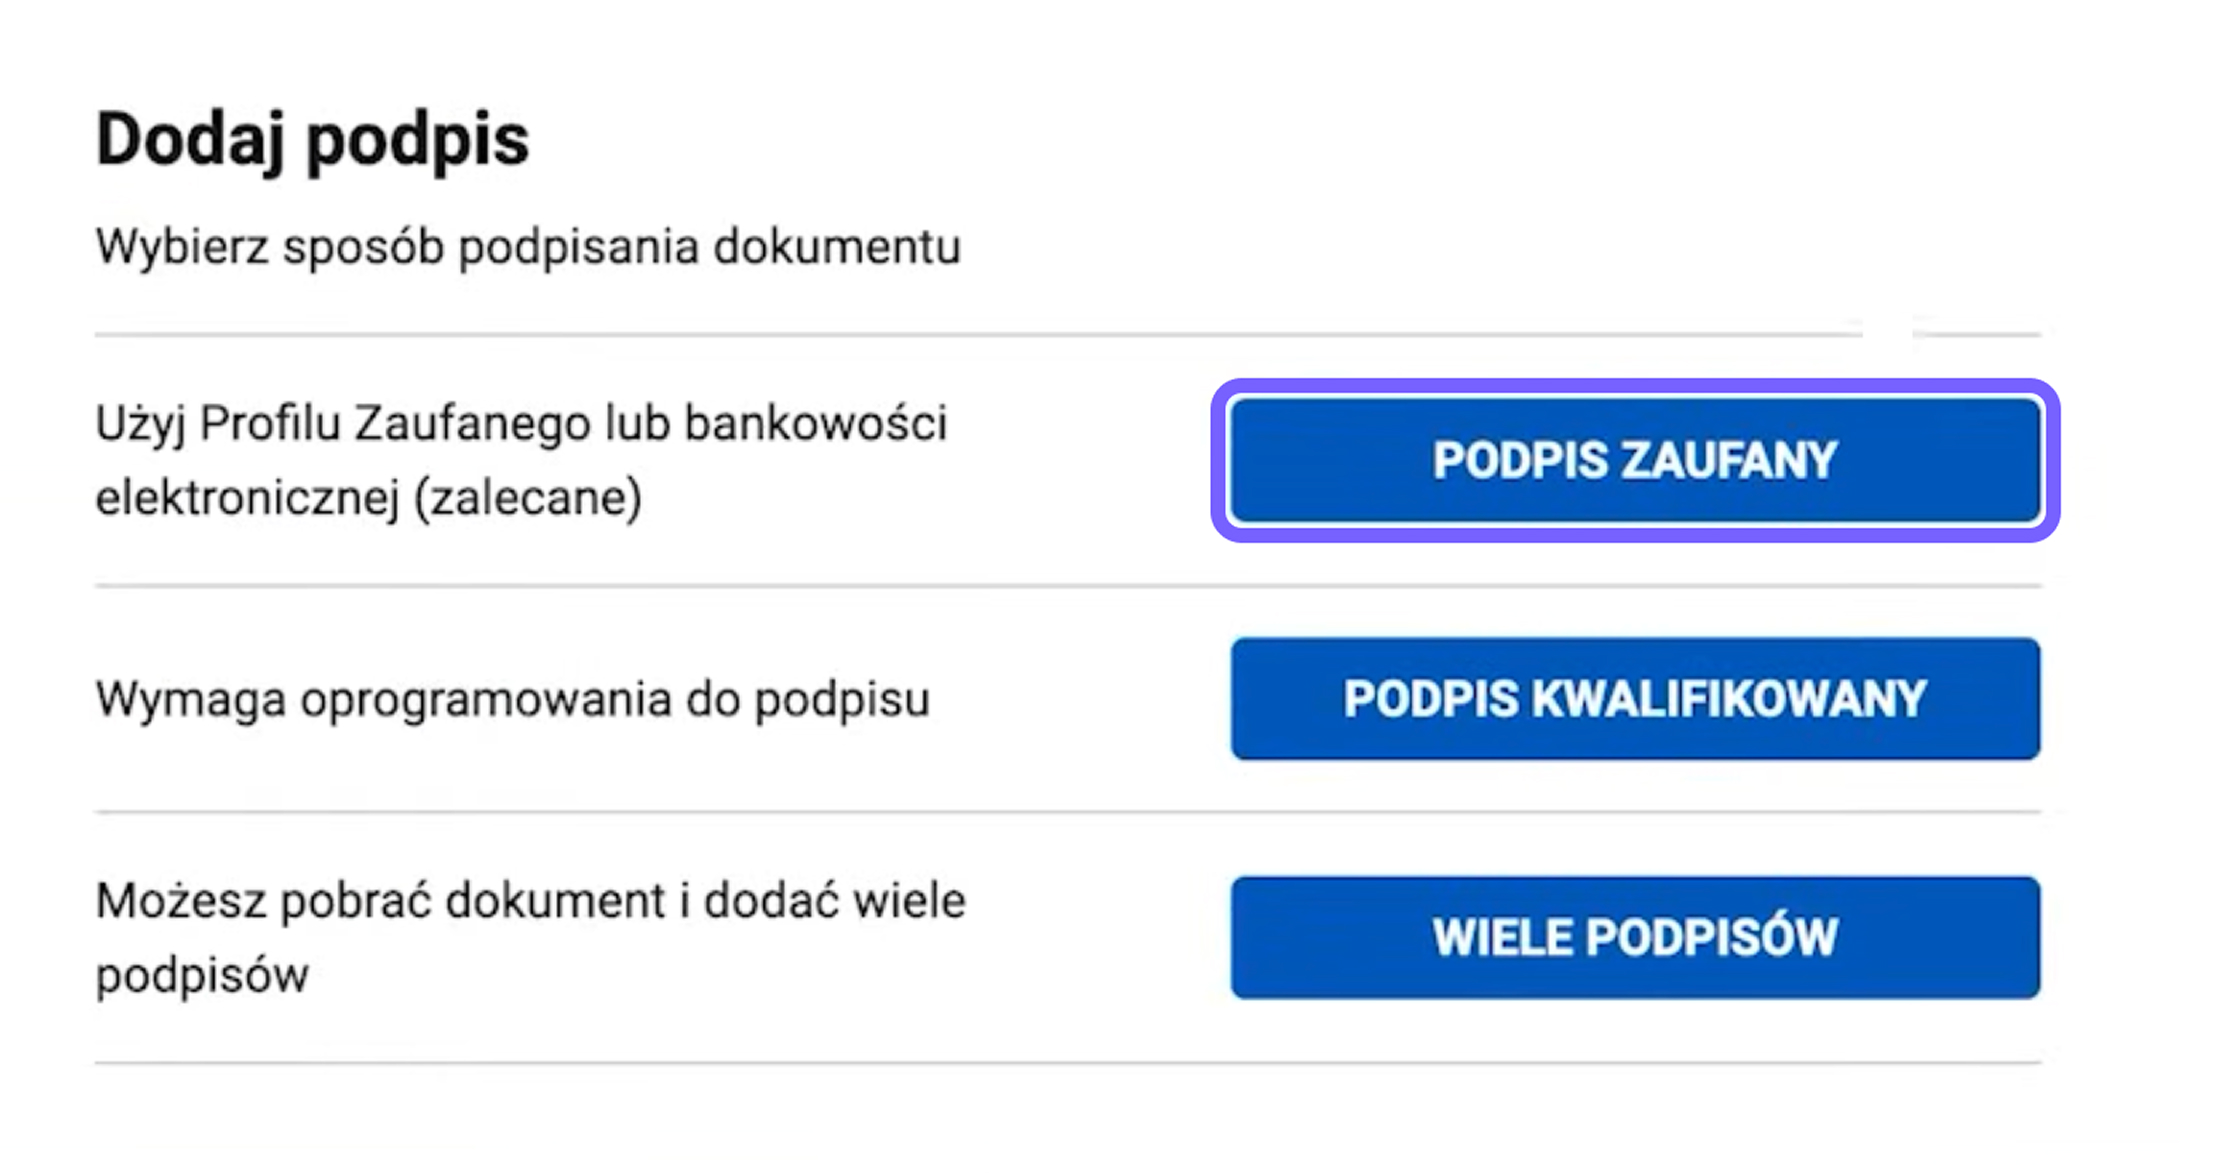
After reviewing the application, select your electronic signature method.
When using Profil Zaufany, click:
Podpis zaufany — Trusted signature
and then:
Podpisz podpisem zaufanym — Sign with a trusted signature.
The system will redirect you to the identity confirmation page. Log in and confirm the signature.
After returning to the application, make sure that the signature has been added.
After signing, click Wyślij — Send.
A submission confirmation will appear on the screen. The document will also be available in the entrepreneur’s account.
It is advisable to save the confirmation or application reference number until the registration process has been completed.

Once the application has been processed, an email confirming the creation of the e-Doręczenia address will be sent to the address provided earlier.
The email will explain what must be done to activate the inbox.
Important: submitting the application does not mean that the inbox is already active. You must follow the instructions in the email and complete the activation process.
Follow the instructions in the email or log in again to Konto Przedsiębiorcy on Biznes.gov.pl.
Then:
After activation, the address will be entered into the Electronic Address Database, BAE. From that point, public authorities will be able to send official correspondence to it.
After logging in for the first time, it is advisable to:
Do not rely only on notifications sent to a regular email account. The responsible person should also log in to the e-Doręczenia inbox regularly.
A business owner or sole trader does not have to process every incoming message personally. Access can be granted to an accountant, lawyer, or another responsible employee.
Only the inbox administrator can add users and manage their permissions.
The system includes several standard roles:
The administrator can also create additional roles with a selected set of permissions.
To add an accountant, the administrator should:
The invitation is valid for 14 days. Once it has been accepted, the user’s status changes to active, and they receive access to the inbox according to the assigned role.
Access is always granted to a specific individual. If an employee leaves the company or cooperation with an accounting firm ends, their permissions must be withdrawn.
Businesses may also appoint several administrators to reduce operational risk. This helps preserve access to inbox management if the main administrator is absent or no longer works with the organisation.
After activating the inbox, it is advisable to establish an internal procedure for handling official correspondence.
A basic procedure may include:
The inbox provided by the public service provider has a guaranteed capacity of 3 GB for non-public entities. A received message remains available in the system for 180 days from the date of delivery.
Messages, attachments, and proof of sending and receipt should therefore be saved regularly in the company’s internal archive.
For a standard message sent to no more than 15 recipients, the maximum total size, including attachments, is 500 MB.
Creating an address and using the public inbox to communicate with public authorities is free of charge for the entrepreneur.
Sending documents from a company or individual to a public authority through the public PURDE service costs PLN 0. The public authority covers the cost of correspondence it sends.
Legally valid correspondence between companies uses paid e-Doręczenia services. It may be provided by a qualified service provider or as an additional service offered by the selected operator.
Availability and pricing depend on the provider’s terms.
Yes. An email address can be added in the settings to receive notifications about new messages.
However, a regular email account is used only for notifications. The official document must be opened in the e-Doręczenia inbox.
No. A separate business address must be created for activity registered in CEIDG.
Yes. Inbox storage is limited, and some documents may be needed several years later.
It is advisable to save the message together with proof of sending and receipt.
An accountant can be granted access and the necessary permissions. However, the business owner remains responsible for controlling who has access and how deadlines are monitored within the business.
Entrepreneurs registered in CEIDG before the end of 2024 do not have to wait until September 2026. The inbox can be created earlier, giving the business time to test the system and establish a clear procedure for handling correspondence.
Before implementation, check:
The ELP Office team will help you understand the necessary steps, arrange access for the responsible accountant, and establish a clear process for handling official correspondence.
This material is provided for informational purposes only. Individual legal and tax matters should be discussed with a qualified specialist.

While salaried employees are automatically insured against all risks, for a sole proprietor (JDG), sickness insurance (dobrowolne ubezpieczenie chorobowe) is strictly voluntary. The entrepreneur must independently submit an application to ZUS to be included in this insurance system. It is these contributions that give you the right to receive maternity and paternity benefits.
Even if you paid minimum contributions, the state will back you up. The Kosiniakowe rule applies: if, after all calculations, the benefit of the insured entrepreneur is below 1,000 PLN net per month, ZUS automatically guarantees a top-up to this amount.
Example: If you paid contributions from the preferential base (Preferencyjny ZUS) for a short time, the calculated benefit amount may be low (e.g., 350 PLN net). In this case, ZUS automatically compensates the difference (650 PLN) from the state budget. This state top-up is completely exempt from income tax (PIT).
Important clarification: This rule applies only to maternity and parental leave and does not apply to paternity leave (urlop ojcowski). You also need to consider taxes: ZUS first calculates the base amount, deducts the tax advance (PIT), and only if the net amount is less than 1,000 PLN does it compensate the difference.
To maximize financial benefits and time with the child, parents can flexibly combine three types of leave. The state system works as a single mechanism: even if one parent is employed (Umowa o pracę) and the other runs a JDG, you can still share the total quotas between yourselves.
Let's take a closer look at each one.
Maternity leave is the first and mandatory stage of support. Its basic duration depends on the number of children born:
Recommendation: Although the law allows you to start maternity leave 6 weeks before childbirth, financially, this is not the most advantageous decision. It is much more effective to take regular pregnancy sick leave (Zwolnienie lekarskie — code B) prior to the birth. It is paid at a rate of 100% of the base, and all your legal 20 weeks of maternity leave will be preserved for use after the baby is born!
Payouts are calculated based on your ZUS base for the last 12 months. You have two paths, and the choice depends on how quickly you submit your application to ZUS. To understand the real numbers, it is important to know the current ZUS bases for 2026:
It is from these amounts that the payout percentages will be calculated depending on the strategy you choose:
The right to take parental leave (urlop rodzicielski) arises immediately after the end of maternity leave (or from the moment of the child's birth if the mother does not have insurance). This is a logical continuation of support, but with one fundamental difference: this leave is intended for both parents.
The basic total duration of this leave for the birth of one child in 2026 is 41 weeks (for twins — 43 weeks). According to Work-Life Balance rules, neither parent can claim this entire duration for themselves.
Leave Architecture:
The mechanics of this leave give entrepreneurs maximum flexibility in planning their time and finances. The following accommodating conditions apply to JDG payers:
Benefit Amount: The payout amount during parental leave directly depends on the strategy you chose when submitting documents right after childbirth (detailed in the section above).
Returning to the 9 weeks strictly reserved for the father. If the father is also an entrepreneur, the following payout rules apply to him:
Addition: If the mother is insured with ZUS but for some reason did not use her share of the parental leave, the father can claim the main portion for himself (up to 32 weeks). This requires a written statement (oświadczenie) from the mother. Important: If the spouse does not have insurance and receives state aid for mothers (świadczenie rodzicielskie) through MOPS or Urząd, the entrepreneur father will not be able to claim these shared 32 weeks from ZUS. However, his personal non-transferable quota of 9 weeks remains securely his under any circumstances!
This is a separate entitlement, independent of the mother's maternity leave. Entrepreneur fathers have the right to 14 calendar days of leave, financed at 100% of the father's individual ZUS base.
Key features:
Here we have consolidated all the bureaucratic steps required to properly formalize your payouts.
When transitioning into any of the listed leaves, the state assumes the payment of your social contributions (pension and disability). However, ZUS does not update this data automatically! You must independently update your status within 7 days from the start date of the specific leave. During the benefit period, the entrepreneur is only obligated to pay health insurance (ubezpieczenie zdrowotne).
What to do in ZUS (via the PUE/eZUS platform):
Legal contribution optimization: Typically, when switching to zdrowotne via the ZZA form, the standard code 05 10 00 is used. But if your benefit is small and the state tops it up to 1,000 PLN under the Kosiniakowe rule, use the special code 05 80 00 (or 05 81 00). This grants you the legal right to skip paying even the health insurance.
What documents to submit for the benefit:
Regardless of who is taking the leave or what kind of leave it is, you will always need:
Additionally, append the following depending on the specific leave you are applying for:
After the leave concludes, the procedure must be repeated in reverse: you need to deregister from zdrowotne (ZWUA) once again and submit form ZUS ZUA to restore your full insurance package. During this process, you have the legal right to proportionally reduce your social contributions for the month in which you were on leave (for instance, for those 14 days of paternity leave).
When you commence maternity leave, your voluntary sickness insurance is canceled automatically. Therefore, when submitting the ZUA form upon returning to work, you are strictly obliged to check the box again to confirm your desire to rejoin the voluntary sickness insurance scheme (dobrowolne ubezpieczenie chorobowe) within 7 days. If you neglect to check this box, your continuity of insurance will be broken, and you will forfeit the right to paid sick leave (L4) in the future.
When mapping out maternity leaves, do not overlook the current support mechanism available for micro-entrepreneurs. Once per calendar year, you have the right to select one month of complete exemption from paying social contributions. In 2026, for Duży ZUS payers, this translates to savings of 1,926.76 PLN for the month.
You cannot utilize these contribution holidays during the same month you receive maternity benefits. However, it serves as an ideal strategic asset that can be activated immediately before heading into maternity leave or directly after returning to work. Furthermore, an entrepreneur father can take his 14 days of paternity leave in one month and the contribution holidays in a subsequent month, thereby maximizing the overall financial support extracted from the state.
Disclaimer: This article is for informational purposes only and relies on current ZUS data for 2026. Every entrepreneur's situation is unique, and legal interpretations may evolve. For precise benefit calculations and tailored tax strategy planning, we strongly recommend booking an individual consultation with an accountant.

The new rules come into force on July 8, 2026. It is important to note that the law was sent to the Constitutional Tribunal for review, but this does not suspend its application. Starting in July, inspectors will begin working according to the new protocols.
The state has established a 12-month transition period. Companies that voluntarily bring their contracts into compliance with the actual nature of work within a year will be able to avoid liability for violations.
Before the adoption of the new amendments, a PIP inspector, upon discovering during an inspection that a person was working on an umowa zlecenie (civil law contract) but was actually performing the duties of a full-time employee, could only file a lawsuit in a labor court.
Court proceedings lasted for years.
Now the procedure becomes two-step and fast:
Main change: the decision comes into force immediately regarding registration in the ZUS system and payment of taxes.
Now, it is not the inspector who goes to court to prove the employer's guilt, but the employer who is forced to go to court to challenge the already made PIP decision.

The era of random "complaint-based" inspections is a thing of the past. The reform introduces a system of automatic data exchange between three state authorities:
This means a transition to a model of digital supervision. Algorithms will be able to automatically identify companies whose payouts on B2B contracts or umowy zlecenie suspiciously resemble the fixed salary of a full-time employee.
In addition, the possibility of remote inspections is introduced, which significantly increases the coverage of the inspectorate.
The inspectorate will look not at the name of the document, but at the actual working conditions (according to Art. 22 of the Labor Code of the Republic of Poland).
Your contract is at risk if the following are present:
The reform significantly increases financial pressure on violators. Fines for key articles are almost doubled:
In addition to fines, the PIP decision automatically obliges the employer to additionally charge all ZUS contributions and taxes for the entire period of the recognized employment relationship.
The state effectively transfers part of the judicial functions to the administrative sphere, lowering the level of procedural guarantees for businesses.
In these conditions, the only way to avoid huge fines is a preventive audit.
ELPOFFICE specialists will help you:
Contact us for a consultation so that your business in Poland remains safe under the protection of professionals.
This material is for informational purposes only and does not constitute individual legal, tax, or accounting advice. For guidance concerning your specific situation, we recommend consulting a qualified professional.

Poland actively supports families, and for foreigners, this is a great way to reduce the amount of tax payable.
For programmers and engineers, Poland remains one of the most beneficial jurisdictions in Europe.
Mechanical tax payment in Poland is a guaranteed overpayment. Maximum benefit is achieved only through a clever combination of reliefs (e.g., IP Box + IKZE + Ulga na dziecko).
However, the right to a deduction exists only when it is supported by flawless documents and correct calculations.
Not sure which reliefs are right for your business model? The specialists at ELPOFFICE will audit your situation, select optimal tax preferences, and help safely apply them in your annual PIT declaration.
This material is for informational purposes only and does not constitute individual legal, tax, or accounting advice. For guidance concerning your specific situation, we recommend consulting a qualified professional.

This is the first thing you need to check. If you don't have the "correct" passport or legal status, the choice may already be made for you.
This is a privilege. In 2026, only foreigners with unrestricted access to the labor market can open a JDG. You can open a JDG if you are:
Note: Holders of standard work visas or "work-based" residence permits generally cannot open a JDG. For you, the path to business lies through a Sp. z o.o.
Available to all foreigners without exception. It doesn't matter if you have a residence permit, a visa, or if you are outside of Poland. You can open a company remotely using only your passport.
The procedures differ significantly in terms of formalities: while a JDG is registered via notification, a company requires drafting articles of association and entry into the court register.
The registration of a sole proprietorship in Poland is highly digitized.
Registering a company is a more formal procedure. You have two options:
Option A: S24 System (Online)
Option B: Via a Notary (Traditional)
Important regarding Capital: To open a Sp. z o.o., a minimum share capital of 5,000 PLN is required. You don't necessarily have to deposit it into the account at the moment of registration (a board declaration is sufficient), but this money must actually be allocated for the firm's needs.
This is a critical factor. The difference is fundamental: are you risking everything you own, or only the money invested in the business?
In a sole proprietorship, there is no legal boundary between you and your business. You are the firm.
The company is a separate legal entity. It lives its own financial life and is responsible for its own obligations.
The legal status of funds is a major differentiator. To whom does the money belong: you personally or the organization?
All funds entering the entrepreneur's account are your private property.
Funds in the company’s bank account belong to the legal entity, not the founders.
The business form directly impacts the complexity of reporting and available tax regimes.
Sole proprietors use simplified accounting (KPiR — Revenue and Expense Ledger).
Legal entities are required to maintain full accounting (Pełna księgowość). This is a complex process involving balance sheets and profit/loss statements.
The size and necessity of insurance contributions are key financial factors for your 2026 budget.
The entrepreneur is responsible for paying ZUS contributions. The system provides a grace period for new businesses:
The obligation to pay ZUS depends on the number of shareholders.
Every business case is unique. ELP Office specialists will help analyze your situation, calculate the tax burden for both options, and choose the optimal strategy.
This material is for informational purposes only and does not constitute individual legal, tax, or accounting advice. For guidance concerning your specific situation, we recommend consulting a qualified professional.

