Comparison of the minimum wage in 2026 and 2027
Only one increase is planned for 2027, effective from 1 January. The approved regulation does not provide for a second increase in July.
Who is covered by the new minimum wage
The amount of PLN 4,950 gross applies to employees working full-time under an employment contract (umowa o pracę).
For part-time employees, the minimum wage is calculated proportionally to their working time.
| Working time |
Minimum wage in 2027 |
| Full-time |
4,950 PLN gross |
| 3/4 time |
3,712.50 PLN gross |
| 1/2 time |
2,475 PLN gross |
| 1/4 time |
1,237.50 PLN gross |
The same rules apply to Polish citizens and foreign nationals working in Poland. An employee’s nationality does not allow an employer to set their salary below the statutory minimum.
The minimum wage does not always mean only the basic salary
The minimum wage does not necessarily have to be equal to the basic salary specified in the employment contract.
When determining whether the statutory minimum has been met, the total value of all salary components that may legally be included in the minimum wage is taken into account. These may include certain bonuses and allowances.
The following payments are not included in the minimum wage:
- overtime pay;
- night work allowance;
- length-of-service allowance;
- allowance for work in special conditions;
- jubilee award;
- severance pay related to retirement or entitlement to a disability pension.
Employers should therefore review not only the employee’s total payment but also the structure of their remuneration.
How much will the employee receive net?
The net amount depends on the employee’s age, tax reliefs, submission of the PIT-2 form, participation in PPK, tax-deductible costs and other individual circumstances.
Under a standard calculation for an employee over the age of 26 who:
- has submitted PIT-2;
- applies standard tax-deductible costs;
- does not participate in PPK;
- does not use any additional tax reliefs,
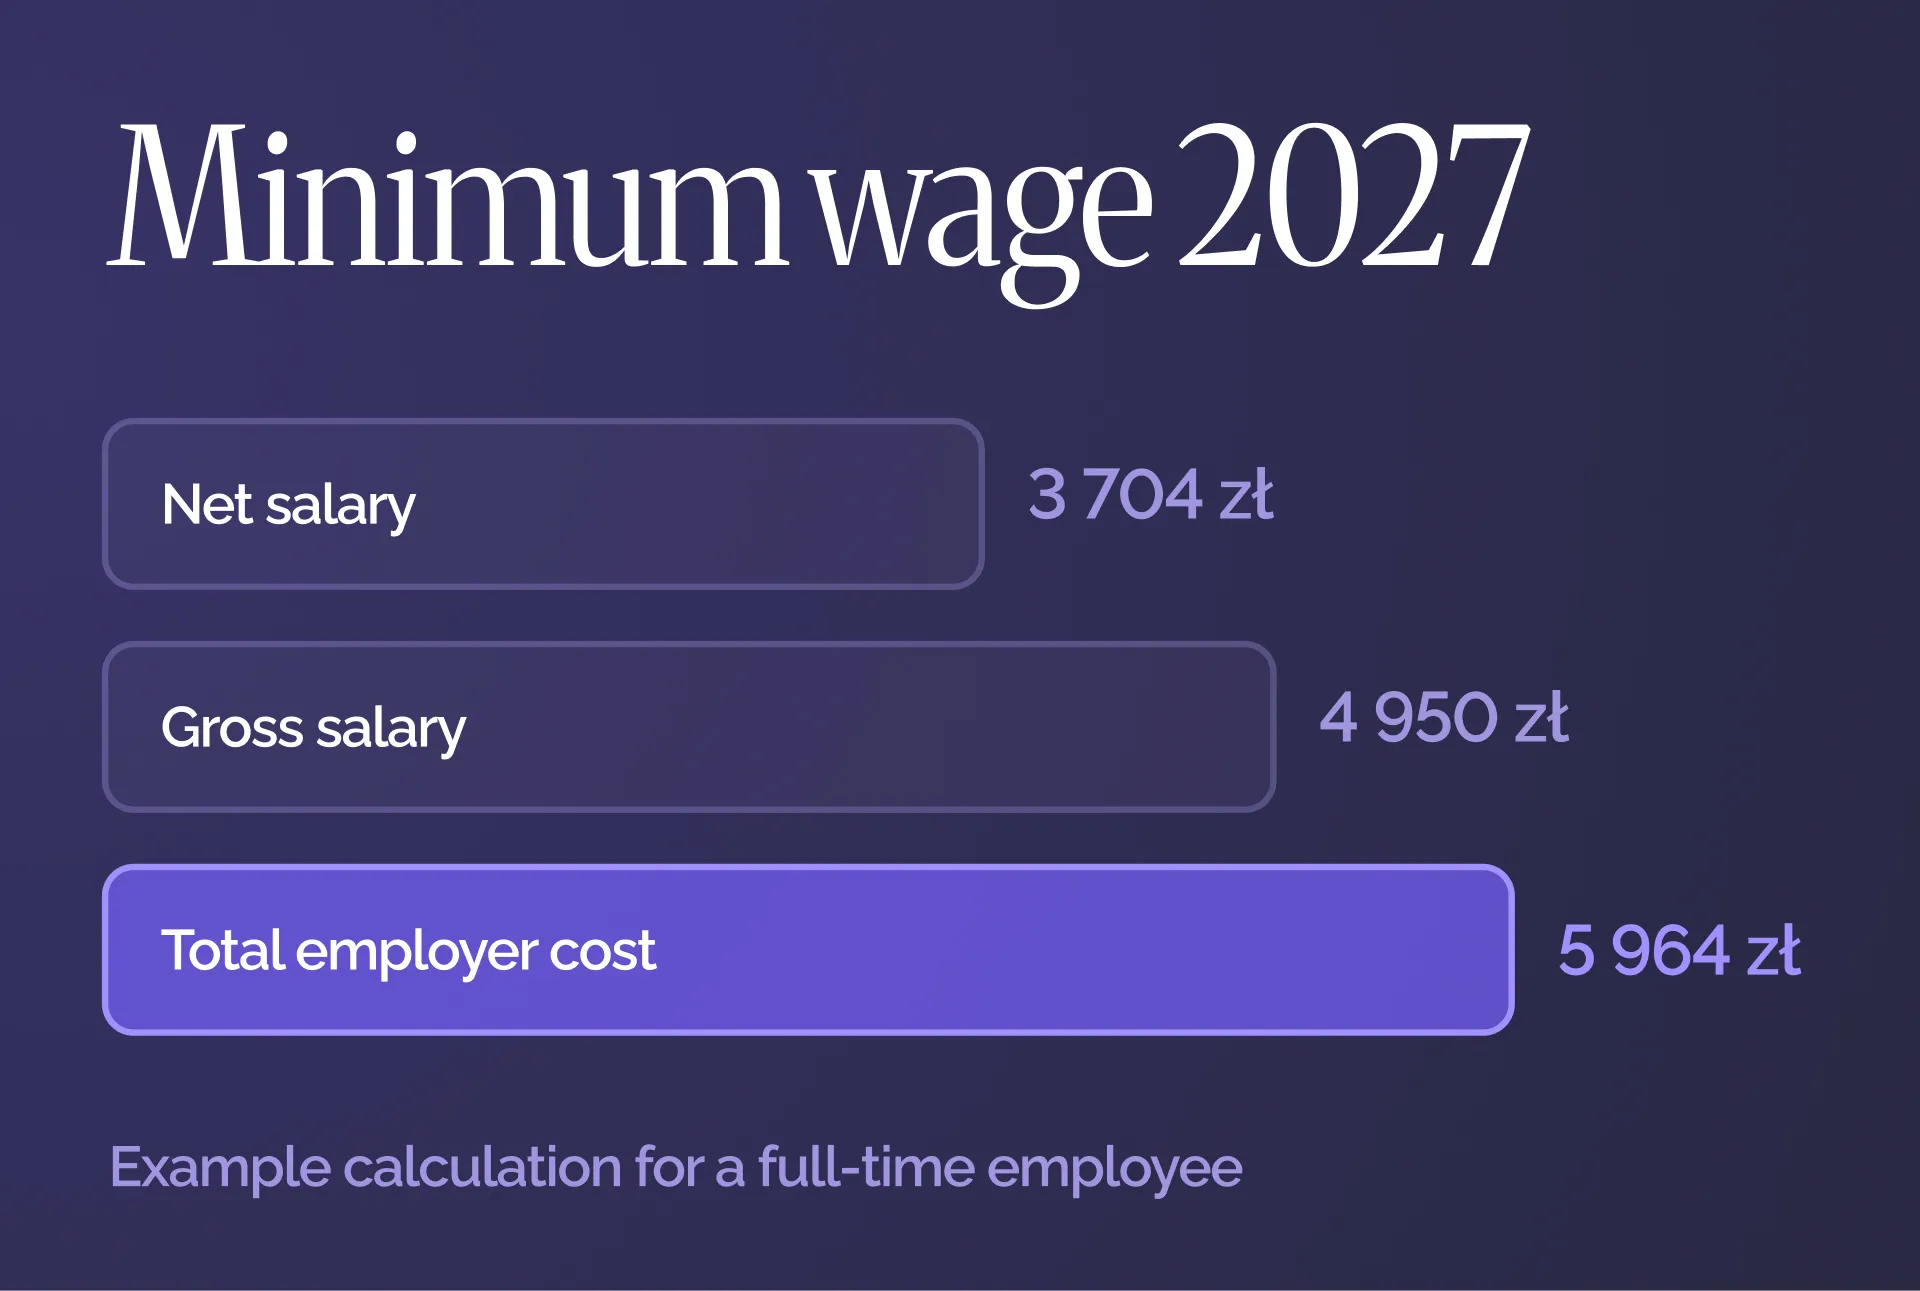
a salary of PLN 4,950 gross will amount to approximately PLN 3,703.93 net.
For comparison, with the 2026 minimum wage of PLN 4,806 gross, the standard net payment is approximately PLN 3,605.85.
This means that, under a standard calculation, the employee will receive approximately PLN 98 net more per month.
This is an estimated calculation. The actual payment may differ depending on the employee’s individual circumstances.
How much will an employee cost the employer?
The employer’s costs are not limited to the employee’s gross salary. The employer also finances its share of ZUS contributions, as well as contributions to the Labour Fund and the Guaranteed Employee Benefits Fund.
Assuming a standard accident insurance rate of 1.67% and excluding PPK, the estimated calculation is as follows:
The total cost of employing one person receiving the minimum wage will increase by approximately PLN 173 per month, or around PLN 2,077 per year.
Actual costs may differ, for example, due to a different accident insurance rate, the employee’s participation in PPK or the employer’s exemption from certain contributions.
Minimum hourly rate under a mandate contract in 2027
From 1 January 2027, the minimum hourly rate for mandate contracts (umowa zlecenie) and certain service agreements will amount to:
PLN 32.30 gross per hour.
This is a gross, not net, amount. The amount received by the contractor depends, among other things, on their age, student status, other social insurance titles and applicable tax reliefs.
The minimum hourly rate applies not only when an hourly payment is explicitly stated in the contract. If the parties agree on a monthly or fixed amount, the payment divided by the number of hours worked must also not be lower than PLN 32.30 gross per hour.
A mandate contract must specify how the number of hours worked will be confirmed. This may include:
- an electronic time record;
- a timesheet;
- a contractor’s report;
- another method specified in the contract.
If the contract is concluded for a period longer than one month, remuneration calculated in accordance with the minimum hourly rate must be paid at least once a month.
The minimum hourly rate may also apply to certain sole proprietors if they perform the services personally and do not employ workers or engage other contractors.
Exceptions apply to certain contracts. For example, the minimum hourly rate may not apply if the contractor independently decides where and when the service is provided and receives remuneration based exclusively on commission. All statutory conditions must be met simultaneously for the exception to apply.
What employers should check before 1 January 2027
Employers and clients engaging contractors should take the following steps in advance:
- Identify employees whose current salary is lower than PLN 4,950 gross.
- Review mandate contracts and other agreements covered by the minimum hourly rate.
- Check whether working hours under mandate contracts are recorded correctly.
- Prepare written amendments to contracts where necessary.
- Update payroll system settings and HR documentation.
- Include the increased costs in the company’s 2027 budget.
- Check which bonuses and allowances may be included in the minimum wage and which must be paid separately.
- Provide updated information to the accountant or payroll and HR specialist.
If a contract specifies a fixed amount below the new statutory minimum, a written amendment to the remuneration terms will generally be required.
If the contract instead provides for payment of the current statutory minimum wage without specifying a fixed amount, the salary will change automatically together with the rate established by law. Nevertheless, the company’s payroll system and documentation should still be reviewed.
How the increase will affect business owners
The minimum wage affects more than employee salaries. It also determines certain contributions and limits applicable to business owners.
Preferential ZUS contributions
Business owners using preferential social insurance contributions during their first 24 months calculate them based on an amount not lower than 30% of the minimum wage.
In 2027, the minimum contribution base will amount to:
PLN 4,950 × 30% = PLN 1,485.
At the currently applicable rates, the estimated amount of social insurance contributions, including voluntary sickness insurance, will be approximately PLN 469.85 per month, excluding the health insurance contribution.
The final contribution amounts for 2027 should be checked again after ZUS publishes its official tables.
The minimum contribution base of PLN 1,485 will also be relevant when determining the lower contribution threshold under the Mały ZUS Plus scheme.
Standard ZUS social insurance contributions without reliefs are calculated using a different basis — the projected average salary. Their amount therefore cannot be determined solely on the basis of the new minimum wage.
Minimum health insurance contribution
Under the rules applicable on the publication date of this article, the minimum health insurance contribution for business owners taxed under the progressive tax scale or flat-rate income tax is calculated as 9% of the minimum wage.
If the rules remain unchanged, from the beginning of the new contribution year in February 2027, the minimum health insurance contribution will amount to:
PLN 4,950 × 9% = PLN 445.50 per month.
For businesses using the lump-sum tax on registered revenue (ryczałt), the health insurance contribution is calculated according to different rules and depends on annual revenue and the average salary in the enterprise sector.
Unregistered business activity
The quarterly revenue limit for unregistered business activity (działalność nierejestrowana) is equal to 225% of the minimum wage.
With a minimum wage of PLN 4,950, the limit in 2027 will amount to:
PLN 11,137.50 in revenue per quarter.
Once the applicable limit is exceeded, the business must be registered in CEIDG within the statutory deadline.
What other amounts will change together with the minimum wage?
The increase in the minimum wage will also affect other calculations, including:
- the night work allowance;
- the portion of salary protected from certain deductions;
- minimum compensation in certain employment law disputes;
- the lower threshold for certain insurance contributions;
- the maximum severance payment in the event of termination for reasons not attributable to the employee.
For example, the maximum severance payment calculated as 15 times the minimum wage will amount to PLN 74,250 in 2027.
The exact night work allowance depends on the number of working hours in a particular month and must therefore be calculated separately for each month.
Frequently asked questions
Does an employee’s salary need to be increased if they already earn more than PLN 4,950 gross?
No. The new amount establishes the minimum level of remuneration but does not require employers to increase every salary in the company automatically.
However, employers should review their internal remuneration system if other rates, bonuses or allowances are linked to the minimum wage.
Is the PLN 32.30 rate under a mandate contract gross or net?
It is a gross rate. The net amount depends on the contractor’s social insurance contributions and tax status.
For example, the calculation will differ for a student under the age of 26 and for a person whose mandate contract is their only title to social insurance.
Can a fixed monthly amount be paid under a mandate contract?
Yes, but after dividing it by the actual number of hours worked, the remuneration cannot be lower than the statutory minimum hourly rate.
Will there be another increase in July 2027?
No. The approved regulation introduces the new amounts from 1 January 2027 and does not provide for a second increase during the year.
Does the minimum wage also apply to foreign nationals?
Yes. A foreign national legally employed in Poland is entitled to the minimum wage on the same terms as a Polish citizen.
In addition, the salary specified in documents related to the employment of a foreign national cannot violate the applicable minimum remuneration requirements.
Prepare for the new rates in advance
Although the increase amounts to only 3%, it will affect more than the amount paid directly to employees. Employers must also account for ZUS contributions, hourly rates under mandate contracts and limits linked to the minimum wage.
If you employ staff or work with contractors under mandate contracts, ELP Office can help you verify the calculations, prepare a payroll budget and correctly account for remuneration and contributions in 2027.
Contact us to prepare your company for the new rates in advance.
This material is provided for informational purposes only and does not constitute individual legal, tax or accounting advice. We recommend consulting an appropriate specialist regarding your specific circumstances.