Running a Business
Minimum wage in Poland in 2027: new rates and employer costs
Comparison of the minimum wage in 2026 and 2027
Only one increase is planned for 2027, effective from 1 January. The approved regulation does not provide for a second increase in July.
Who is covered by the new minimum wage
The amount of PLN 4,950 gross applies to employees working full-time under an employment contract (umowa o pracę).
For part-time employees, the minimum wage is calculated proportionally to their working time.
The same rules apply to Polish citizens and foreign nationals working in Poland. An employee’s nationality does not allow an employer to set their salary below the statutory minimum.
The minimum wage does not always mean only the basic salary
The minimum wage does not necessarily have to be equal to the basic salary specified in the employment contract.
When determining whether the statutory minimum has been met, the total value of all salary components that may legally be included in the minimum wage is taken into account. These may include certain bonuses and allowances.
The following payments are not included in the minimum wage:
- overtime pay;
- night work allowance;
- length-of-service allowance;
- allowance for work in special conditions;
- jubilee award;
- severance pay related to retirement or entitlement to a disability pension.
Employers should therefore review not only the employee’s total payment but also the structure of their remuneration.
How much will the employee receive net?
The net amount depends on the employee’s age, tax reliefs, submission of the PIT-2 form, participation in PPK, tax-deductible costs and other individual circumstances.
Under a standard calculation for an employee over the age of 26 who:
- has submitted PIT-2;
- applies standard tax-deductible costs;
- does not participate in PPK;
- does not use any additional tax reliefs,
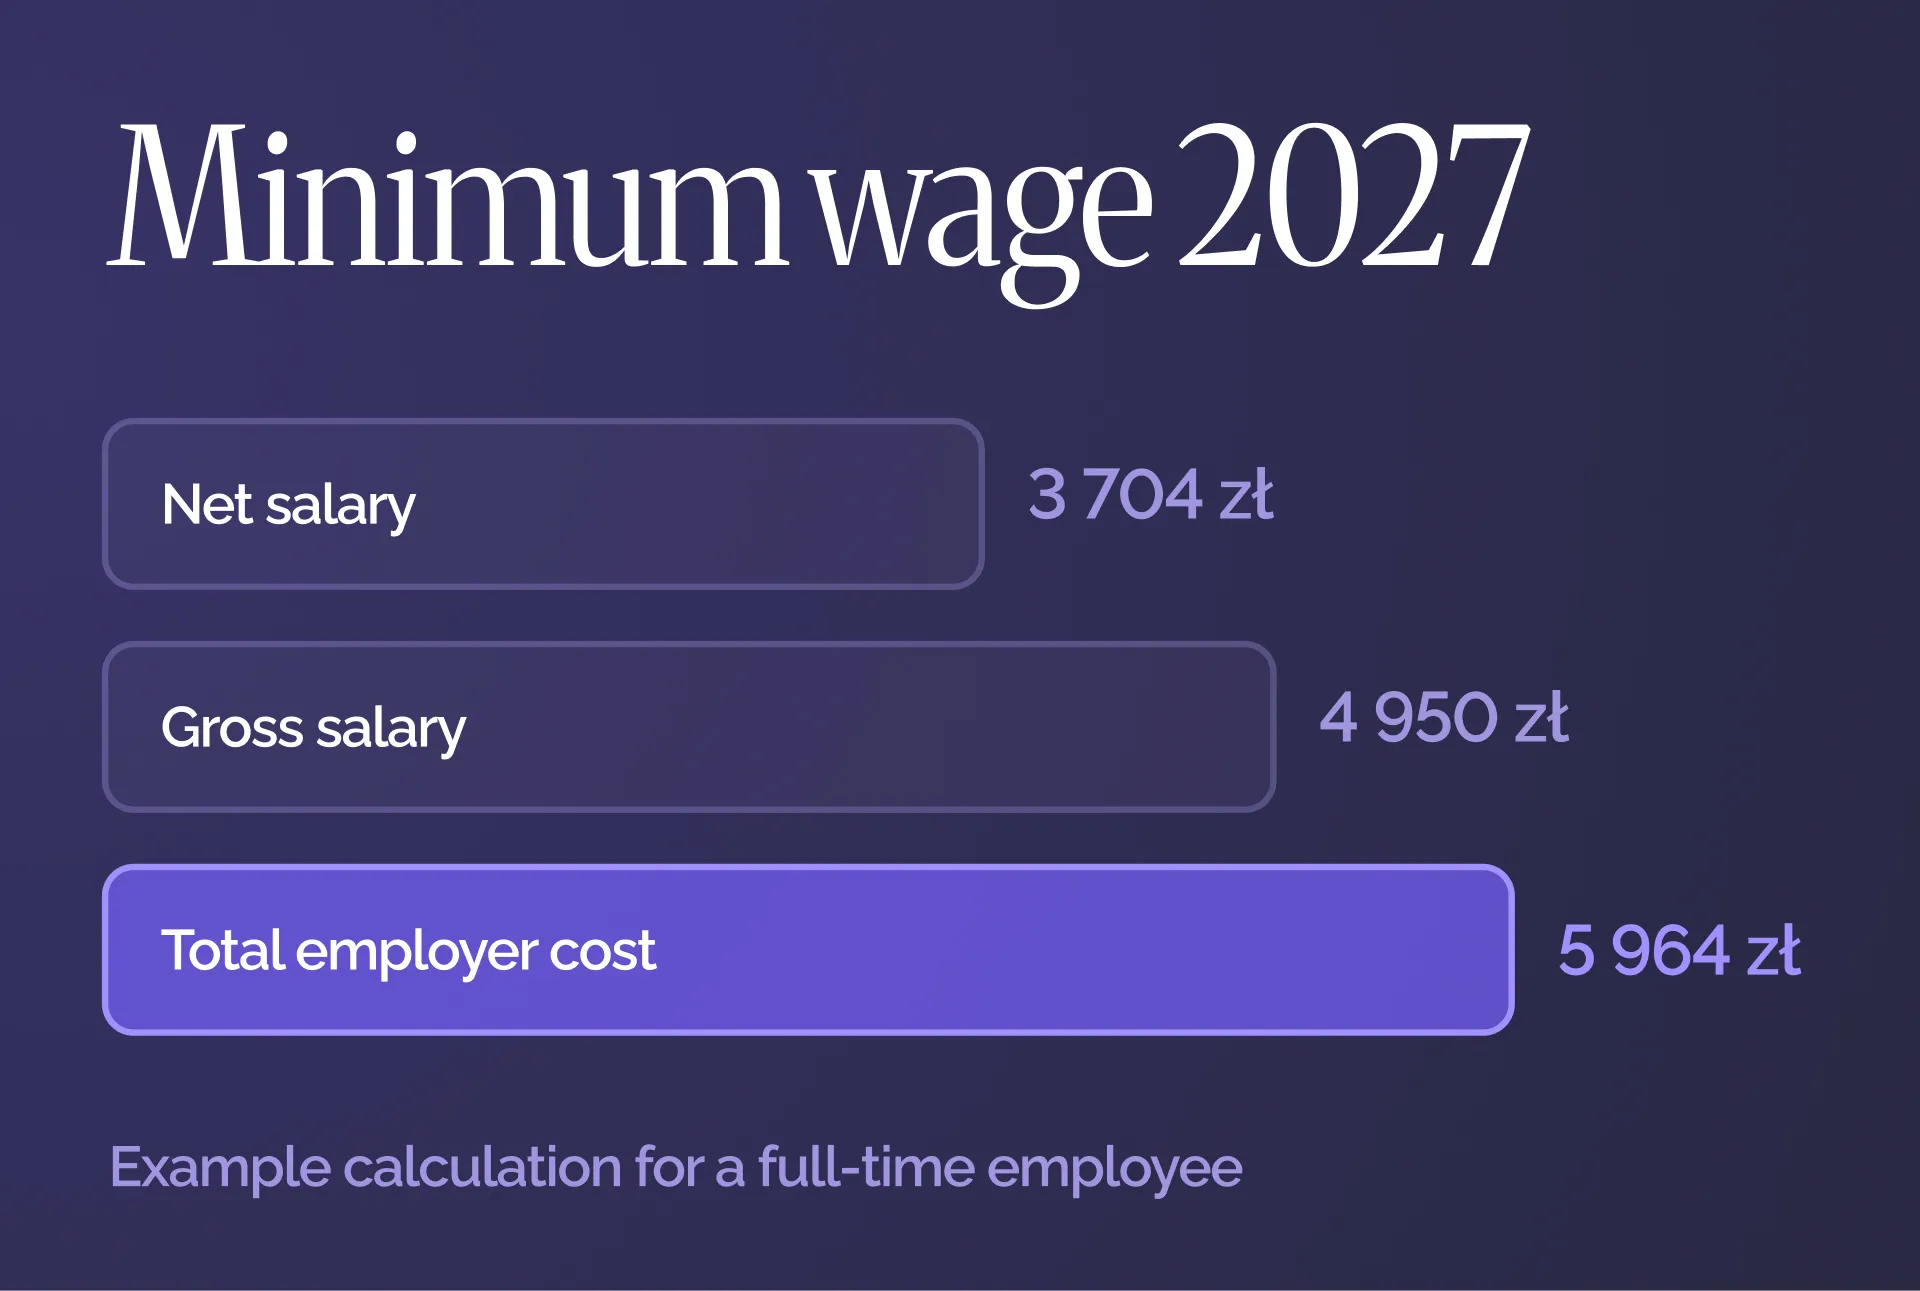
a salary of PLN 4,950 gross will amount to approximately PLN 3,703.93 net.
For comparison, with the 2026 minimum wage of PLN 4,806 gross, the standard net payment is approximately PLN 3,605.85.
This means that, under a standard calculation, the employee will receive approximately PLN 98 net more per month.
This is an estimated calculation. The actual payment may differ depending on the employee’s individual circumstances.
How much will an employee cost the employer?
The employer’s costs are not limited to the employee’s gross salary. The employer also finances its share of ZUS contributions, as well as contributions to the Labour Fund and the Guaranteed Employee Benefits Fund.
Assuming a standard accident insurance rate of 1.67% and excluding PPK, the estimated calculation is as follows:
The total cost of employing one person receiving the minimum wage will increase by approximately PLN 173 per month, or around PLN 2,077 per year.
Actual costs may differ, for example, due to a different accident insurance rate, the employee’s participation in PPK or the employer’s exemption from certain contributions.
Minimum hourly rate under a mandate contract in 2027
From 1 January 2027, the minimum hourly rate for mandate contracts (umowa zlecenie) and certain service agreements will amount to:
PLN 32.30 gross per hour.
This is a gross, not net, amount. The amount received by the contractor depends, among other things, on their age, student status, other social insurance titles and applicable tax reliefs.
The minimum hourly rate applies not only when an hourly payment is explicitly stated in the contract. If the parties agree on a monthly or fixed amount, the payment divided by the number of hours worked must also not be lower than PLN 32.30 gross per hour.
A mandate contract must specify how the number of hours worked will be confirmed. This may include:
- an electronic time record;
- a timesheet;
- a contractor’s report;
- another method specified in the contract.
If the contract is concluded for a period longer than one month, remuneration calculated in accordance with the minimum hourly rate must be paid at least once a month.
The minimum hourly rate may also apply to certain sole proprietors if they perform the services personally and do not employ workers or engage other contractors.
Exceptions apply to certain contracts. For example, the minimum hourly rate may not apply if the contractor independently decides where and when the service is provided and receives remuneration based exclusively on commission. All statutory conditions must be met simultaneously for the exception to apply.
What employers should check before 1 January 2027
Employers and clients engaging contractors should take the following steps in advance:
- Identify employees whose current salary is lower than PLN 4,950 gross.
- Review mandate contracts and other agreements covered by the minimum hourly rate.
- Check whether working hours under mandate contracts are recorded correctly.
- Prepare written amendments to contracts where necessary.
- Update payroll system settings and HR documentation.
- Include the increased costs in the company’s 2027 budget.
- Check which bonuses and allowances may be included in the minimum wage and which must be paid separately.
- Provide updated information to the accountant or payroll and HR specialist.
If a contract specifies a fixed amount below the new statutory minimum, a written amendment to the remuneration terms will generally be required.
If the contract instead provides for payment of the current statutory minimum wage without specifying a fixed amount, the salary will change automatically together with the rate established by law. Nevertheless, the company’s payroll system and documentation should still be reviewed.
How the increase will affect business owners
The minimum wage affects more than employee salaries. It also determines certain contributions and limits applicable to business owners.
Preferential ZUS contributions
Business owners using preferential social insurance contributions during their first 24 months calculate them based on an amount not lower than 30% of the minimum wage.
In 2027, the minimum contribution base will amount to:
PLN 4,950 × 30% = PLN 1,485.
At the currently applicable rates, the estimated amount of social insurance contributions, including voluntary sickness insurance, will be approximately PLN 469.85 per month, excluding the health insurance contribution.
The final contribution amounts for 2027 should be checked again after ZUS publishes its official tables.
The minimum contribution base of PLN 1,485 will also be relevant when determining the lower contribution threshold under the Mały ZUS Plus scheme.
Standard ZUS social insurance contributions without reliefs are calculated using a different basis — the projected average salary. Their amount therefore cannot be determined solely on the basis of the new minimum wage.
Minimum health insurance contribution
Under the rules applicable on the publication date of this article, the minimum health insurance contribution for business owners taxed under the progressive tax scale or flat-rate income tax is calculated as 9% of the minimum wage.
If the rules remain unchanged, from the beginning of the new contribution year in February 2027, the minimum health insurance contribution will amount to:
PLN 4,950 × 9% = PLN 445.50 per month.
For businesses using the lump-sum tax on registered revenue (ryczałt), the health insurance contribution is calculated according to different rules and depends on annual revenue and the average salary in the enterprise sector.
Unregistered business activity
The quarterly revenue limit for unregistered business activity (działalność nierejestrowana) is equal to 225% of the minimum wage.
With a minimum wage of PLN 4,950, the limit in 2027 will amount to:
PLN 11,137.50 in revenue per quarter.
Once the applicable limit is exceeded, the business must be registered in CEIDG within the statutory deadline.
What other amounts will change together with the minimum wage?
The increase in the minimum wage will also affect other calculations, including:
- the night work allowance;
- the portion of salary protected from certain deductions;
- minimum compensation in certain employment law disputes;
- the lower threshold for certain insurance contributions;
- the maximum severance payment in the event of termination for reasons not attributable to the employee.
For example, the maximum severance payment calculated as 15 times the minimum wage will amount to PLN 74,250 in 2027.
The exact night work allowance depends on the number of working hours in a particular month and must therefore be calculated separately for each month.
Frequently asked questions
Does an employee’s salary need to be increased if they already earn more than PLN 4,950 gross?
No. The new amount establishes the minimum level of remuneration but does not require employers to increase every salary in the company automatically.
However, employers should review their internal remuneration system if other rates, bonuses or allowances are linked to the minimum wage.
Is the PLN 32.30 rate under a mandate contract gross or net?
It is a gross rate. The net amount depends on the contractor’s social insurance contributions and tax status.
For example, the calculation will differ for a student under the age of 26 and for a person whose mandate contract is their only title to social insurance.
Can a fixed monthly amount be paid under a mandate contract?
Yes, but after dividing it by the actual number of hours worked, the remuneration cannot be lower than the statutory minimum hourly rate.
Will there be another increase in July 2027?
No. The approved regulation introduces the new amounts from 1 January 2027 and does not provide for a second increase during the year.
Does the minimum wage also apply to foreign nationals?
Yes. A foreign national legally employed in Poland is entitled to the minimum wage on the same terms as a Polish citizen.
In addition, the salary specified in documents related to the employment of a foreign national cannot violate the applicable minimum remuneration requirements.
Prepare for the new rates in advance
Although the increase amounts to only 3%, it will affect more than the amount paid directly to employees. Employers must also account for ZUS contributions, hourly rates under mandate contracts and limits linked to the minimum wage.
If you employ staff or work with contractors under mandate contracts, ELP Office can help you verify the calculations, prepare a payroll budget and correctly account for remuneration and contributions in 2027.
Contact us to prepare your company for the new rates in advance.
This material is provided for informational purposes only and does not constitute individual legal, tax or accounting advice. We recommend consulting an appropriate specialist regarding your specific circumstances.
e-Doręczenia for Business in Poland: Who Needs an Electronic Address and How to Set It Up
What is e-Doręczenia?
e-Doręczenia is the electronic equivalent of a registered letter with proof of delivery. The system can be used to submit applications, receive decisions from public authorities, and retain official proof that documents have been sent and delivered.
An e-Doręczenia address cannot be replaced with a standard company email address. It is a unique technical address registered in the official Electronic Address Database — Baza Adresów Elektronicznych, or BAE.
It may look like this:
AE:PL-12345-67890-ABCDE-12
The address makes it possible to identify the sender and recipient and confirm the date and time when correspondence was transmitted.
Personal and business correspondence use separate addresses. Therefore, even if someone already has a personal e-Doręczenia inbox, they must create a separate business address for their activity registered in CEIDG.
ePUAP has not disappeared completely. However, since 1 January 2026, e-Doręczenia has been the main channel for official electronic correspondence. Other communication methods may still be used where special regulations or a specific electronic service allow them.
Who must have an e-Doręczenia address?
The registration deadline depends on the register in which the business is entered and the date of registration.
Sole traders registered in CEIDG before the end of 2024 must therefore activate their address no later than 30 September 2026.
However, it is not always possible to wait until that date. If an entrepreneur changes their CEIDG details after 30 June 2025, the information required to create an e-Doręczenia address becomes a mandatory part of the application.
This may apply, for example, when:
- changing the business address;
- suspending or resuming business activity;
- changing PKD activity codes;
- adding or changing an authorised representative;
- making other updates to the CEIDG entry.
Why the inbox must be checked regularly
The e-Doręczenia system applies the principle of deemed delivery — fikcja doręczenia.
If correspondence from a public authority is delivered to the inbox of a company or entrepreneur but is not received earlier, it is considered legally delivered on the day following the end of the 14-day period calculated from the date of receipt indicated in the delivery confirmation.
That date is treated as the official date of service. Deadlines for responding, submitting documents, or filing an appeal are calculated according to the rules applicable to the relevant procedure.
As a rule, the absence of an email notification, the owner’s holiday, or irregular inbox checks do not suspend statutory deadlines.
What may happen if the inbox is not created or checked
The e-Doręczenia Act does not impose a separate automatic fine solely for failing to have an address. The main risk is missing legally significant correspondence and the deadlines connected with it.
If the recipient does not have an active e-Doręczenia address, a public authority may, where permitted by law, use the Public Hybrid Service — Publiczna Usługa Hybrydowa, or PUH.
The document is transferred electronically to the operator, printed, and delivered to the recipient in paper form.
Once the address has been activated, it is particularly important to monitor incoming messages regularly. Missing a deadline may mean that the entrepreneur does not have enough time to submit documents, respond to a request, or appeal a decision.
In tax proceedings, an authority may impose a kara porządkowa, or procedural fine, in the circumstances listed in Article 262 of the Polish Tax Ordinance. In 2026, the maximum amount is PLN 3,800.
This is not a fine for simply having or not having an e-Doręczenia inbox. It may be imposed for a specific procedural violation, such as failing to comply with a properly delivered request where tax law allows such a penalty.
How to create an e-Doręczenia address for a sole trader
For a sole trader registered in CEIDG, creating an e-Doręczenia address usually takes little time. Most information is retrieved automatically, and the application can be signed using Profil Zaufany.
The process is similar to creating a personal e-Doręczenia inbox. However, the applicant must select registration of an address specifically for business activity.
Important: a personal e-Doręczenia address and a sole trader’s business address are two separate addresses. Official correspondence relating to an activity registered in CEIDG requires a separate business address.
What to prepare before you start
You will need:
- Profil Zaufany, e-dowód, or a qualified electronic signature;
- a current email address;
- access to your account on Biznes.gov.pl;
- the administrator’s details if another person will manage the inbox.
A sole trader may manage the inbox personally. An accountant or another user can be added later, after the address has been activated.
Step 1. Open the address creation service
Log in to Konto Przedsiębiorcy on Biznes.gov.pl and open the service for creating an e-Doręczenia address.

On the start screen, click:
Złóż wniosek — Submit an application.

Step 2. Select the public service provider
The system will ask how you want to create the address. Select:
Utworzenie adresu u publicznego dostawcy usługi — Create an address with the public service provider.
This is the free option intended for official correspondence with public authorities.
Click Dalej — Next.
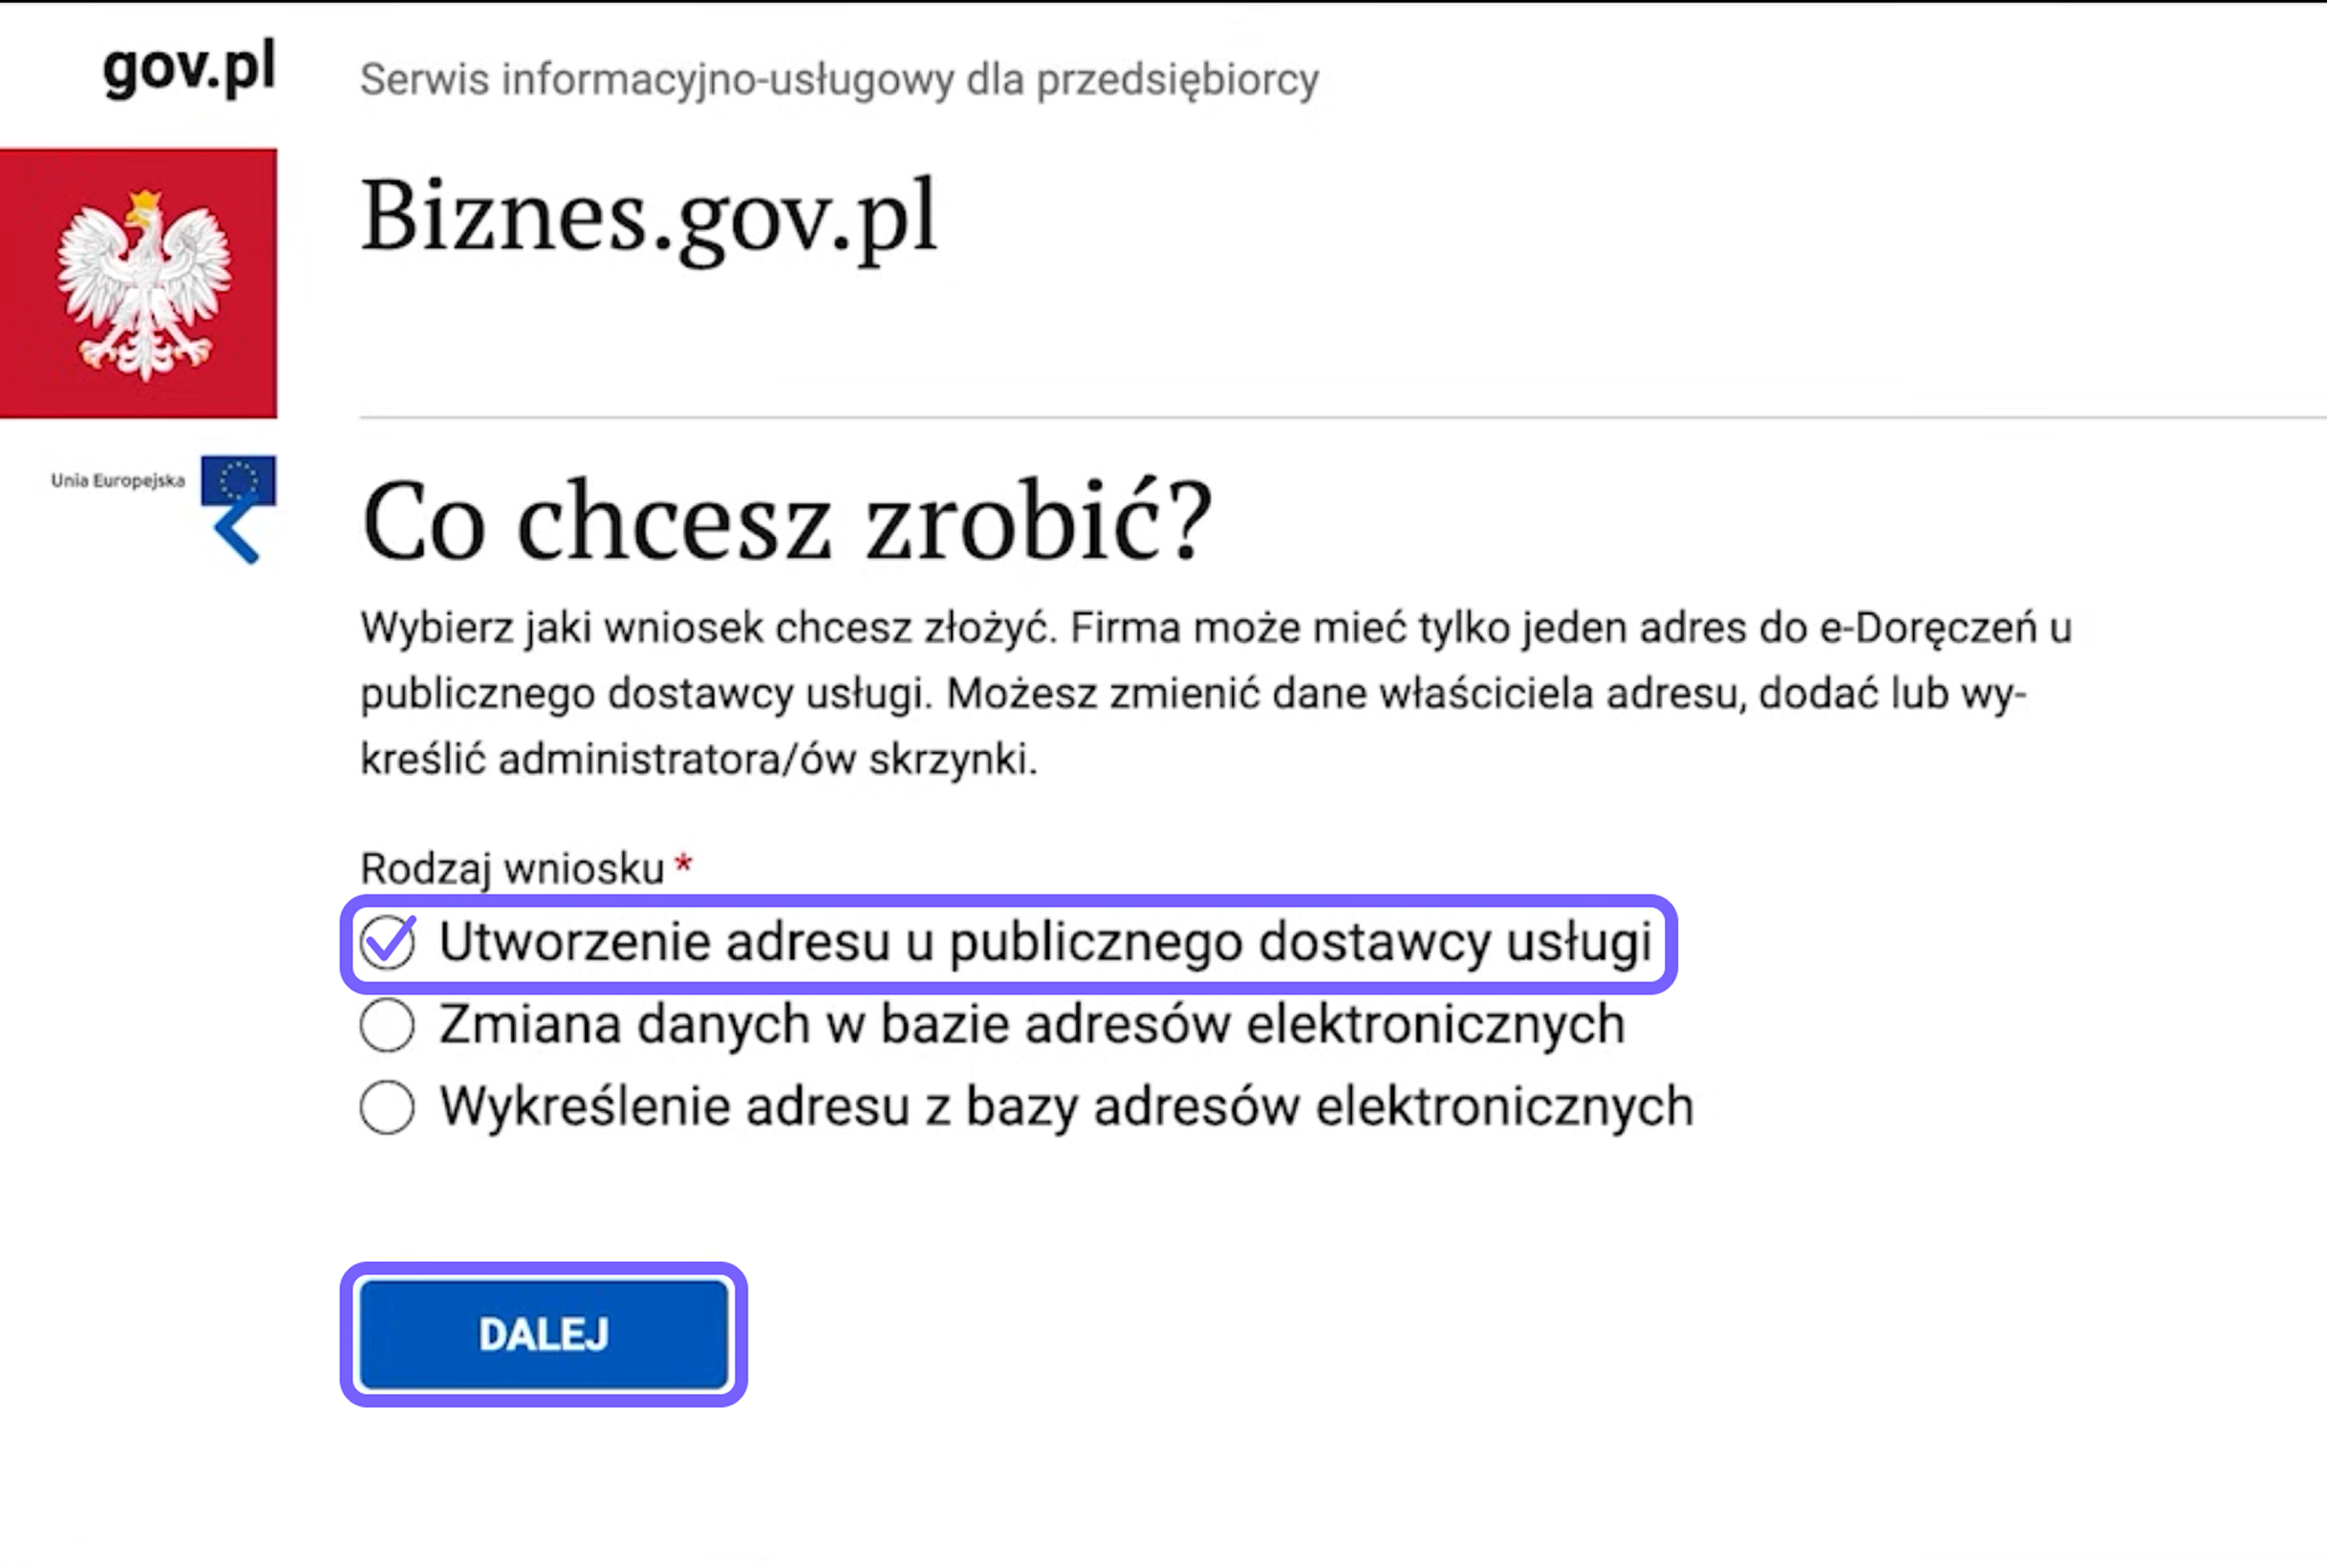
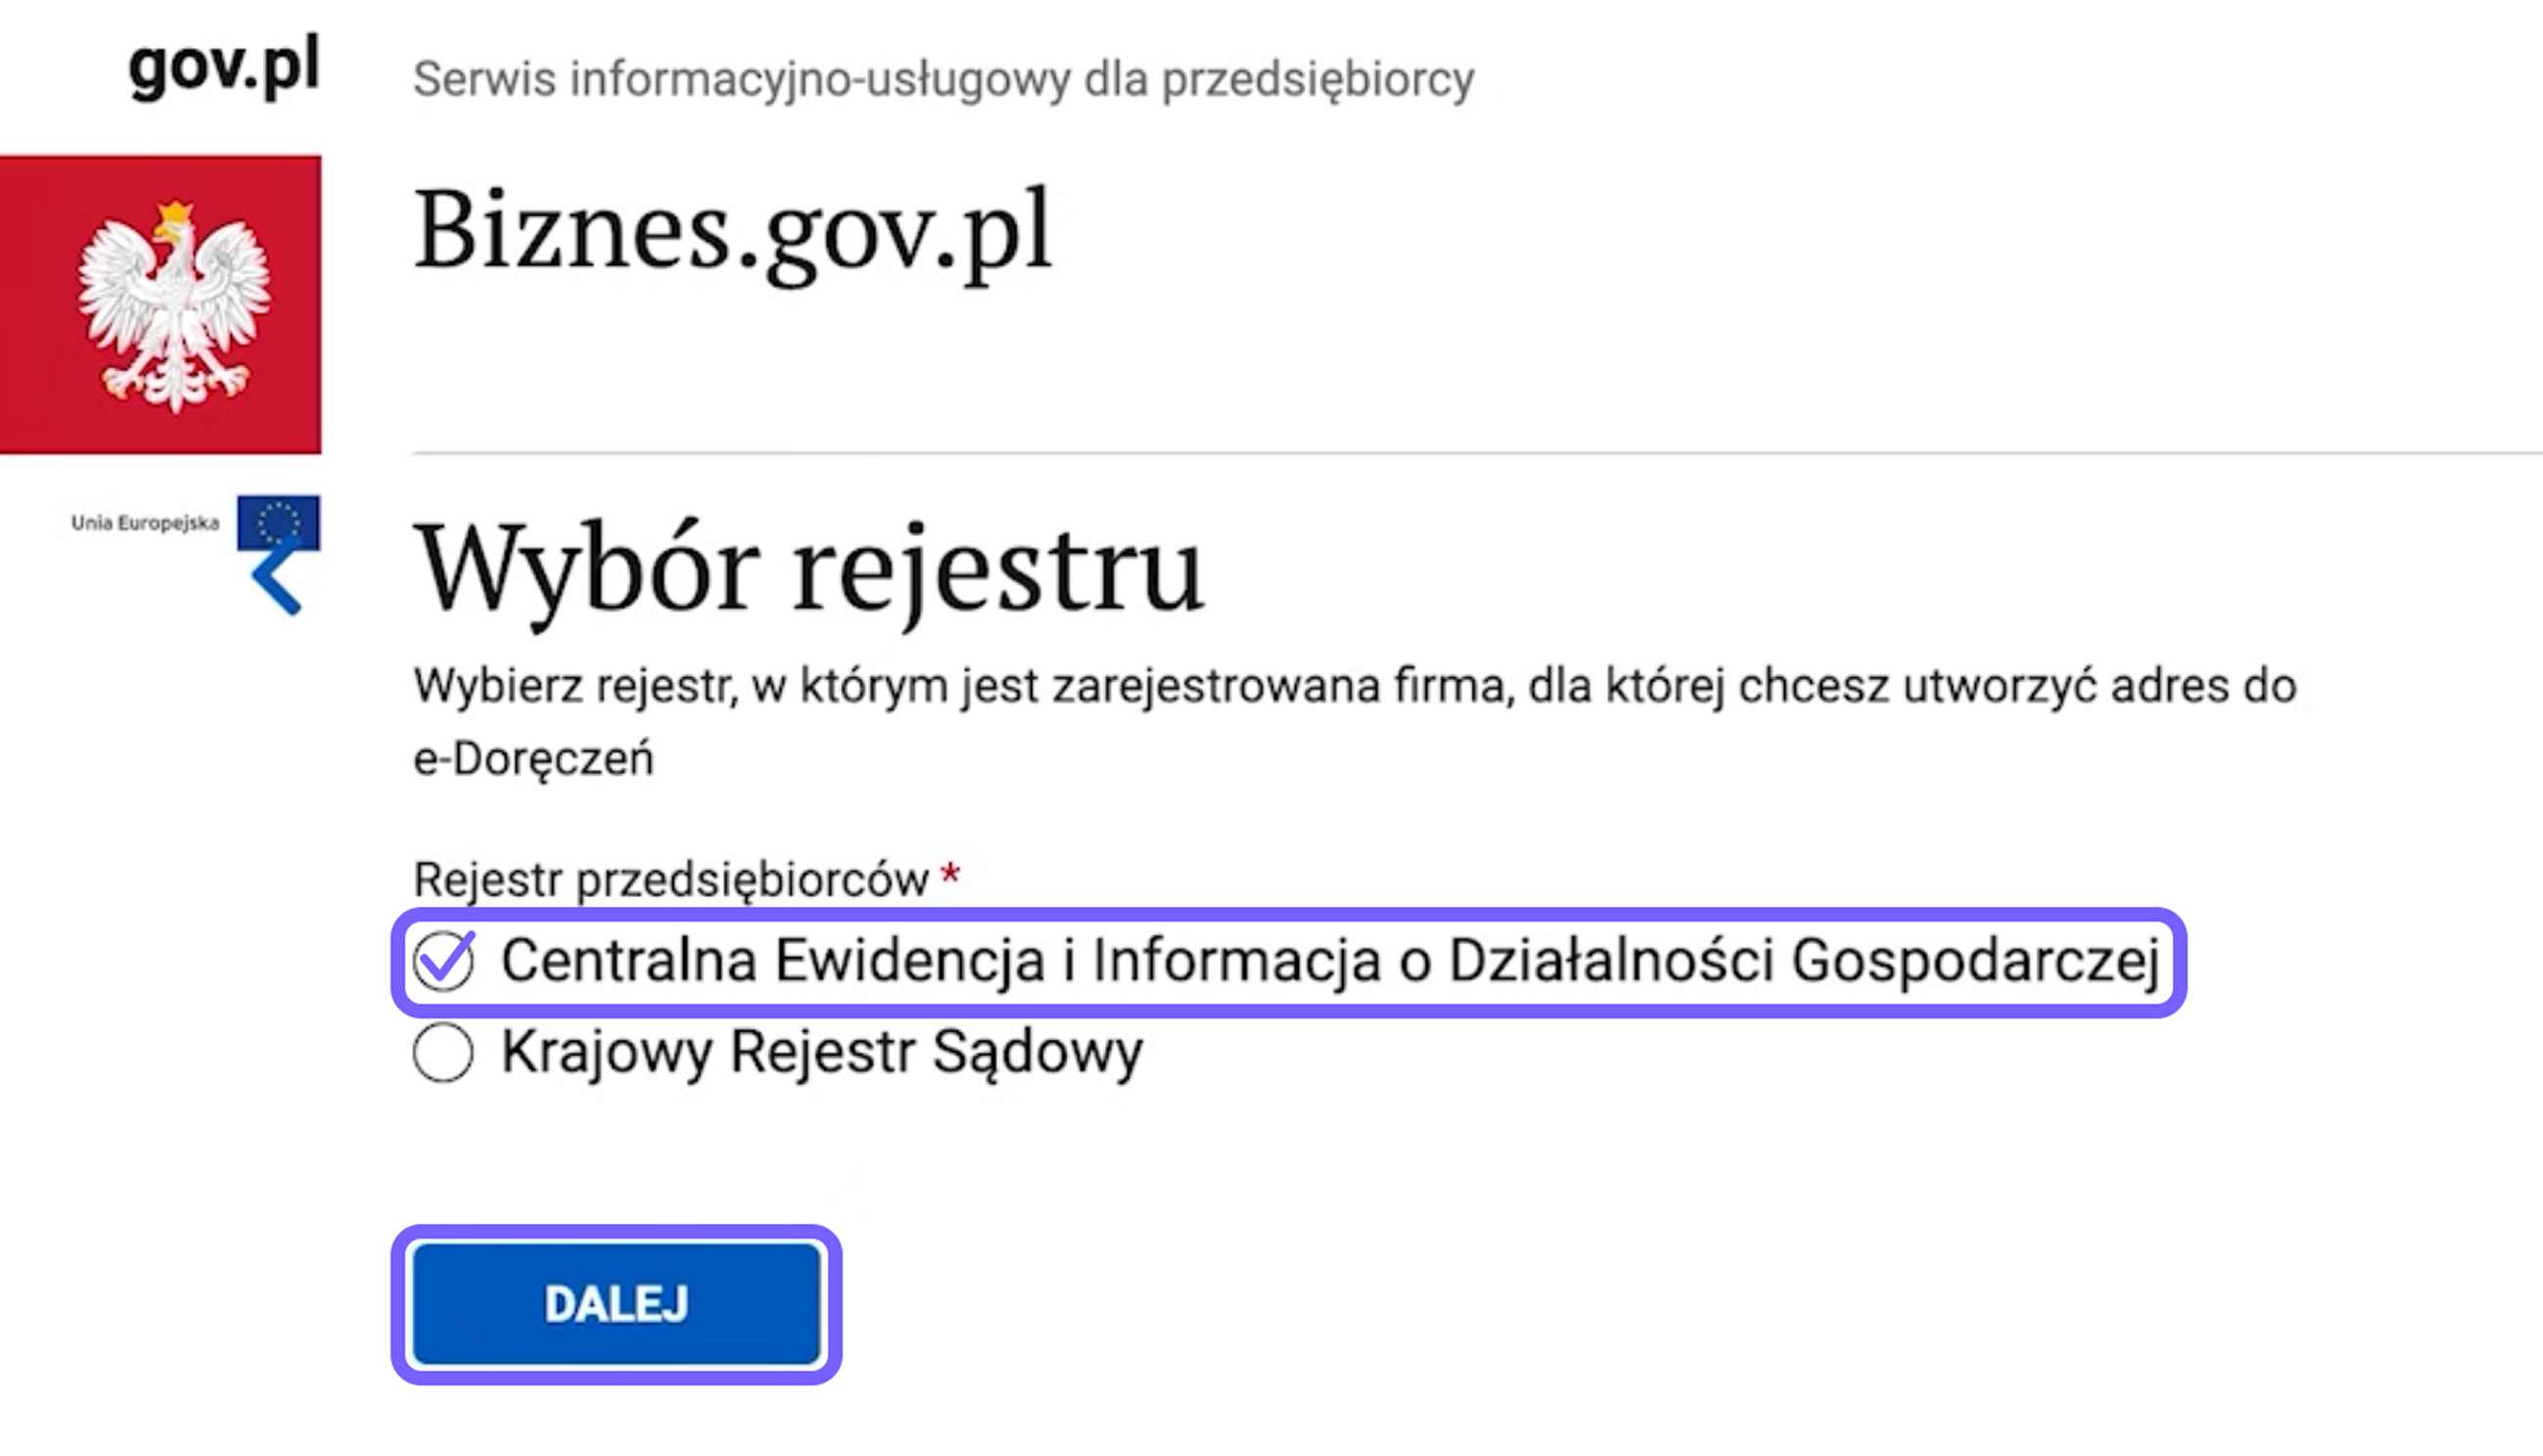
Step 3. Select the business register
On the next screen, select:
Centralna Ewidencja i Informacja o Działalności Gospodarczej — Central Register and Information on Economic Activity, CEIDG.
This option is intended for sole traders operating as a jednoosobowa działalność gospodarcza, or JDG.
Click Dalej — Next.
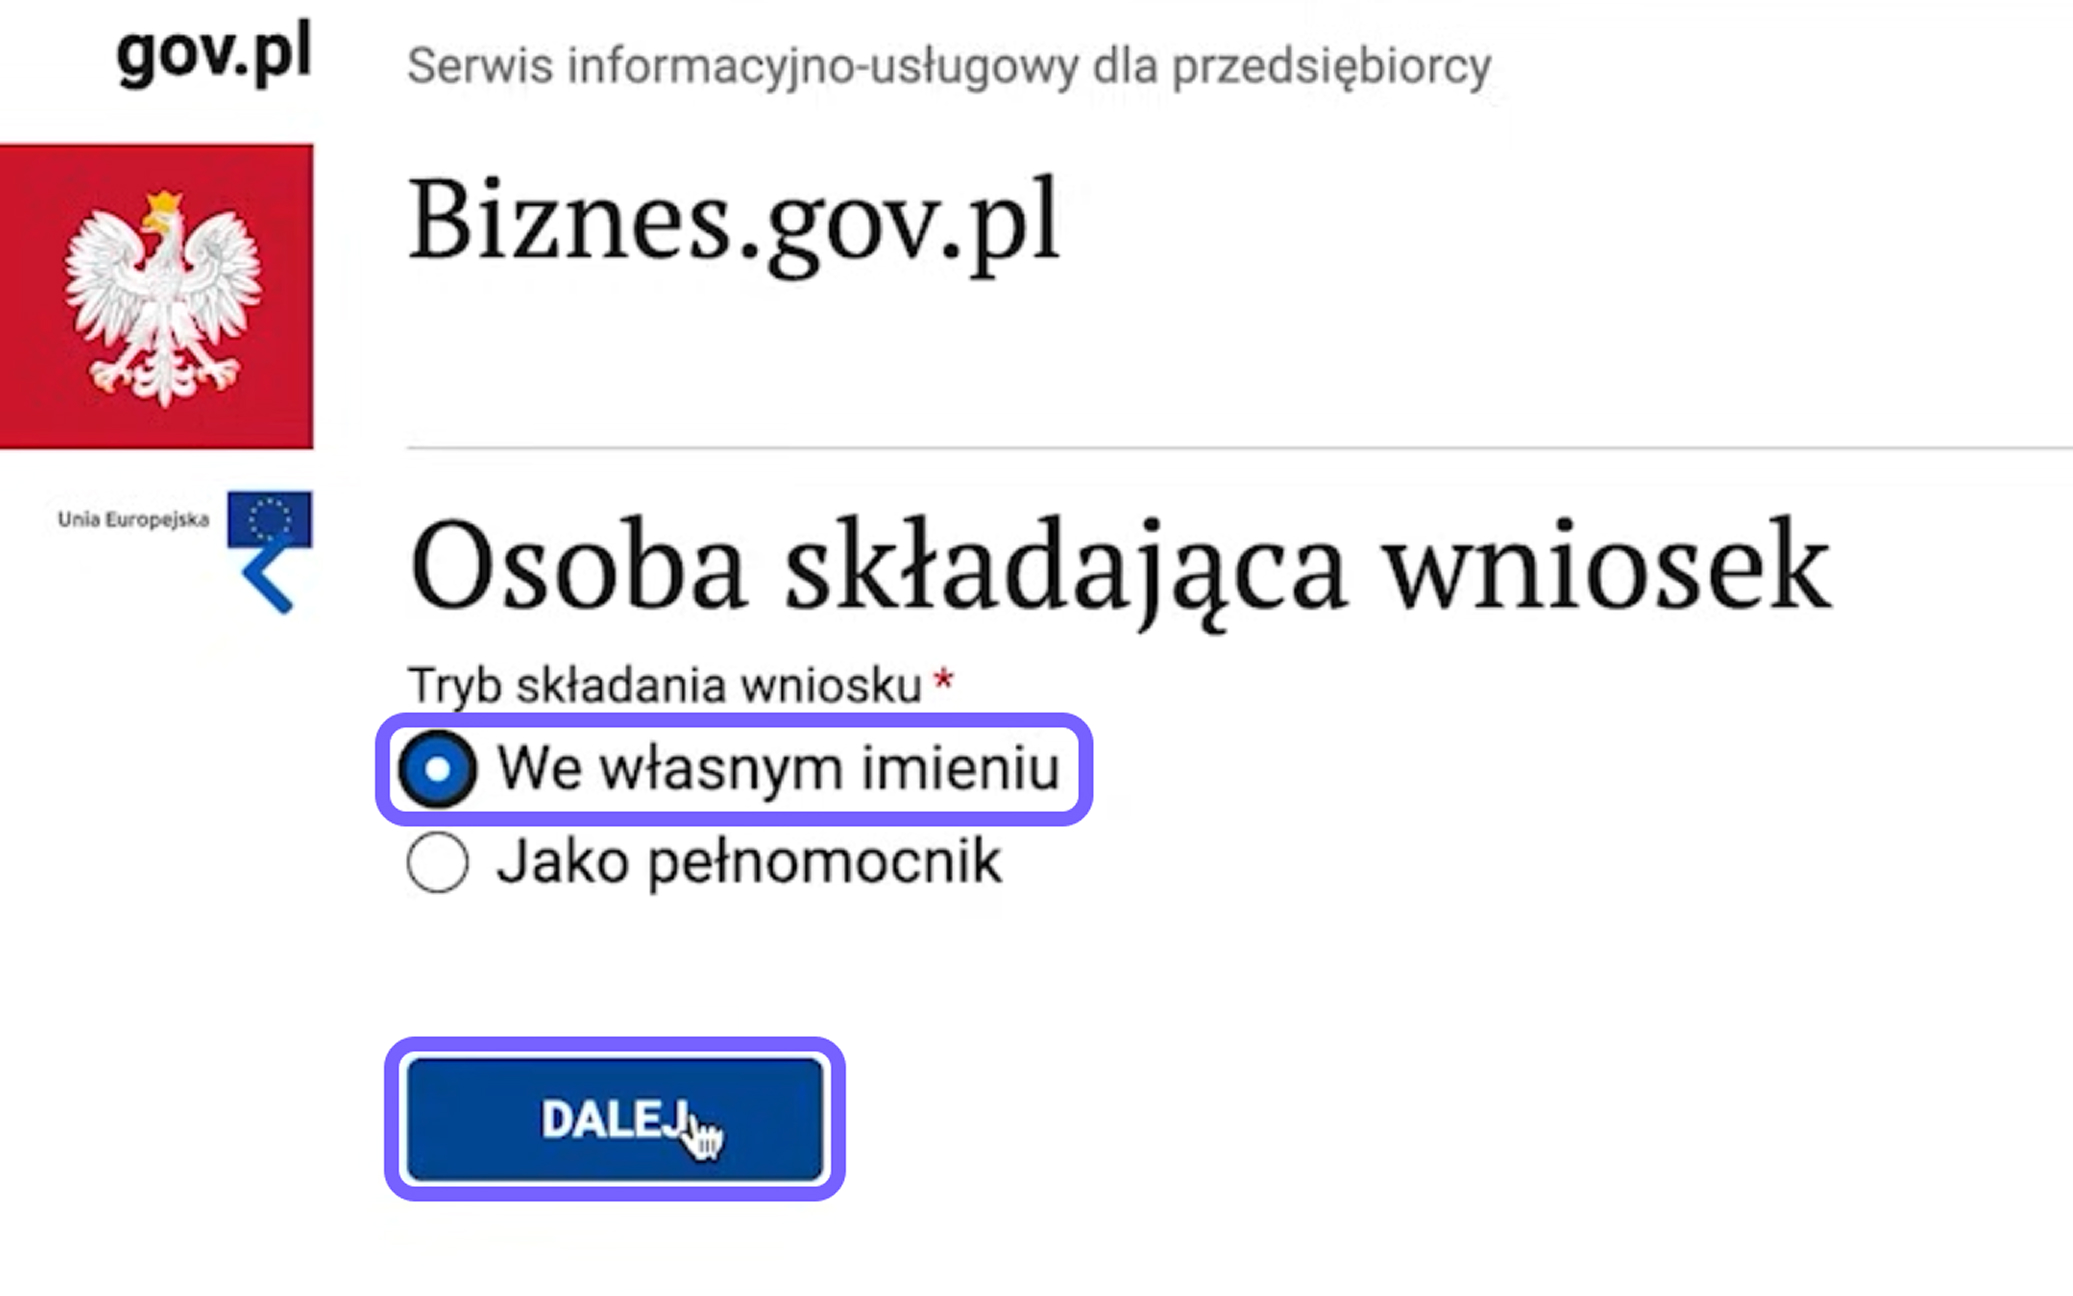
Step 4. Specify on whose behalf the application is being submitted
When creating an address for your own business activity, select:
We własnym imieniu — On my own behalf.
Then click Dalej — Next.
If the application is being submitted by an authorised representative, the process and required documents may be different.
Step 5. Check and complete your details
Some information will be retrieved automatically from CEIDG. Check that the entrepreneur’s details are correct and complete any missing fields.
In particular, verify:
- first name and surname;
- PESEL number;
- NIP and REGON numbers;
- registered business name;
- contact details;
- regular email address.
Technical notifications will be sent to the email address provided, including information about the application status and instructions for activating the inbox.
A regular email address does not replace e-Doręczenia. It is used only for notifications.
After checking the information, click Dalej — Next.
Step 6. Decide whether a separate administrator is needed
The system will ask whether you want to appoint an inbox administrator.
If the entrepreneur intends to manage the inbox personally, they may select the option without appointing a separate administrator.
If another person will manage access and settings, their details must be provided. The administrator may, among other things:
- manage users;
- grant and withdraw access;
- configure permissions;
- work with correspondence within the scope of their permissions.
A separate administrator is not mandatory for a standard JDG. An accountant can be added as a user after the inbox has been activated.
Click Dalej — Next.
Step 7. Accept the terms and conditions
Read the terms governing the service and confirm your acceptance.
Select the relevant box next to Regulamin — Terms and Conditions, then click Dalej — Next.
Step 8. Confirm the declarations
The next screen will display the required declarations — oświadczenia.
Read them and select the necessary boxes to confirm that the information provided is correct.
Then click Dalej — Next.
Step 9. Check the public authority
The system will automatically display the authority responsible for processing the application.
Check the information and click Dalej — Next. In most cases, you do not need to search for or select the authority manually.
Step 10. Sign the application
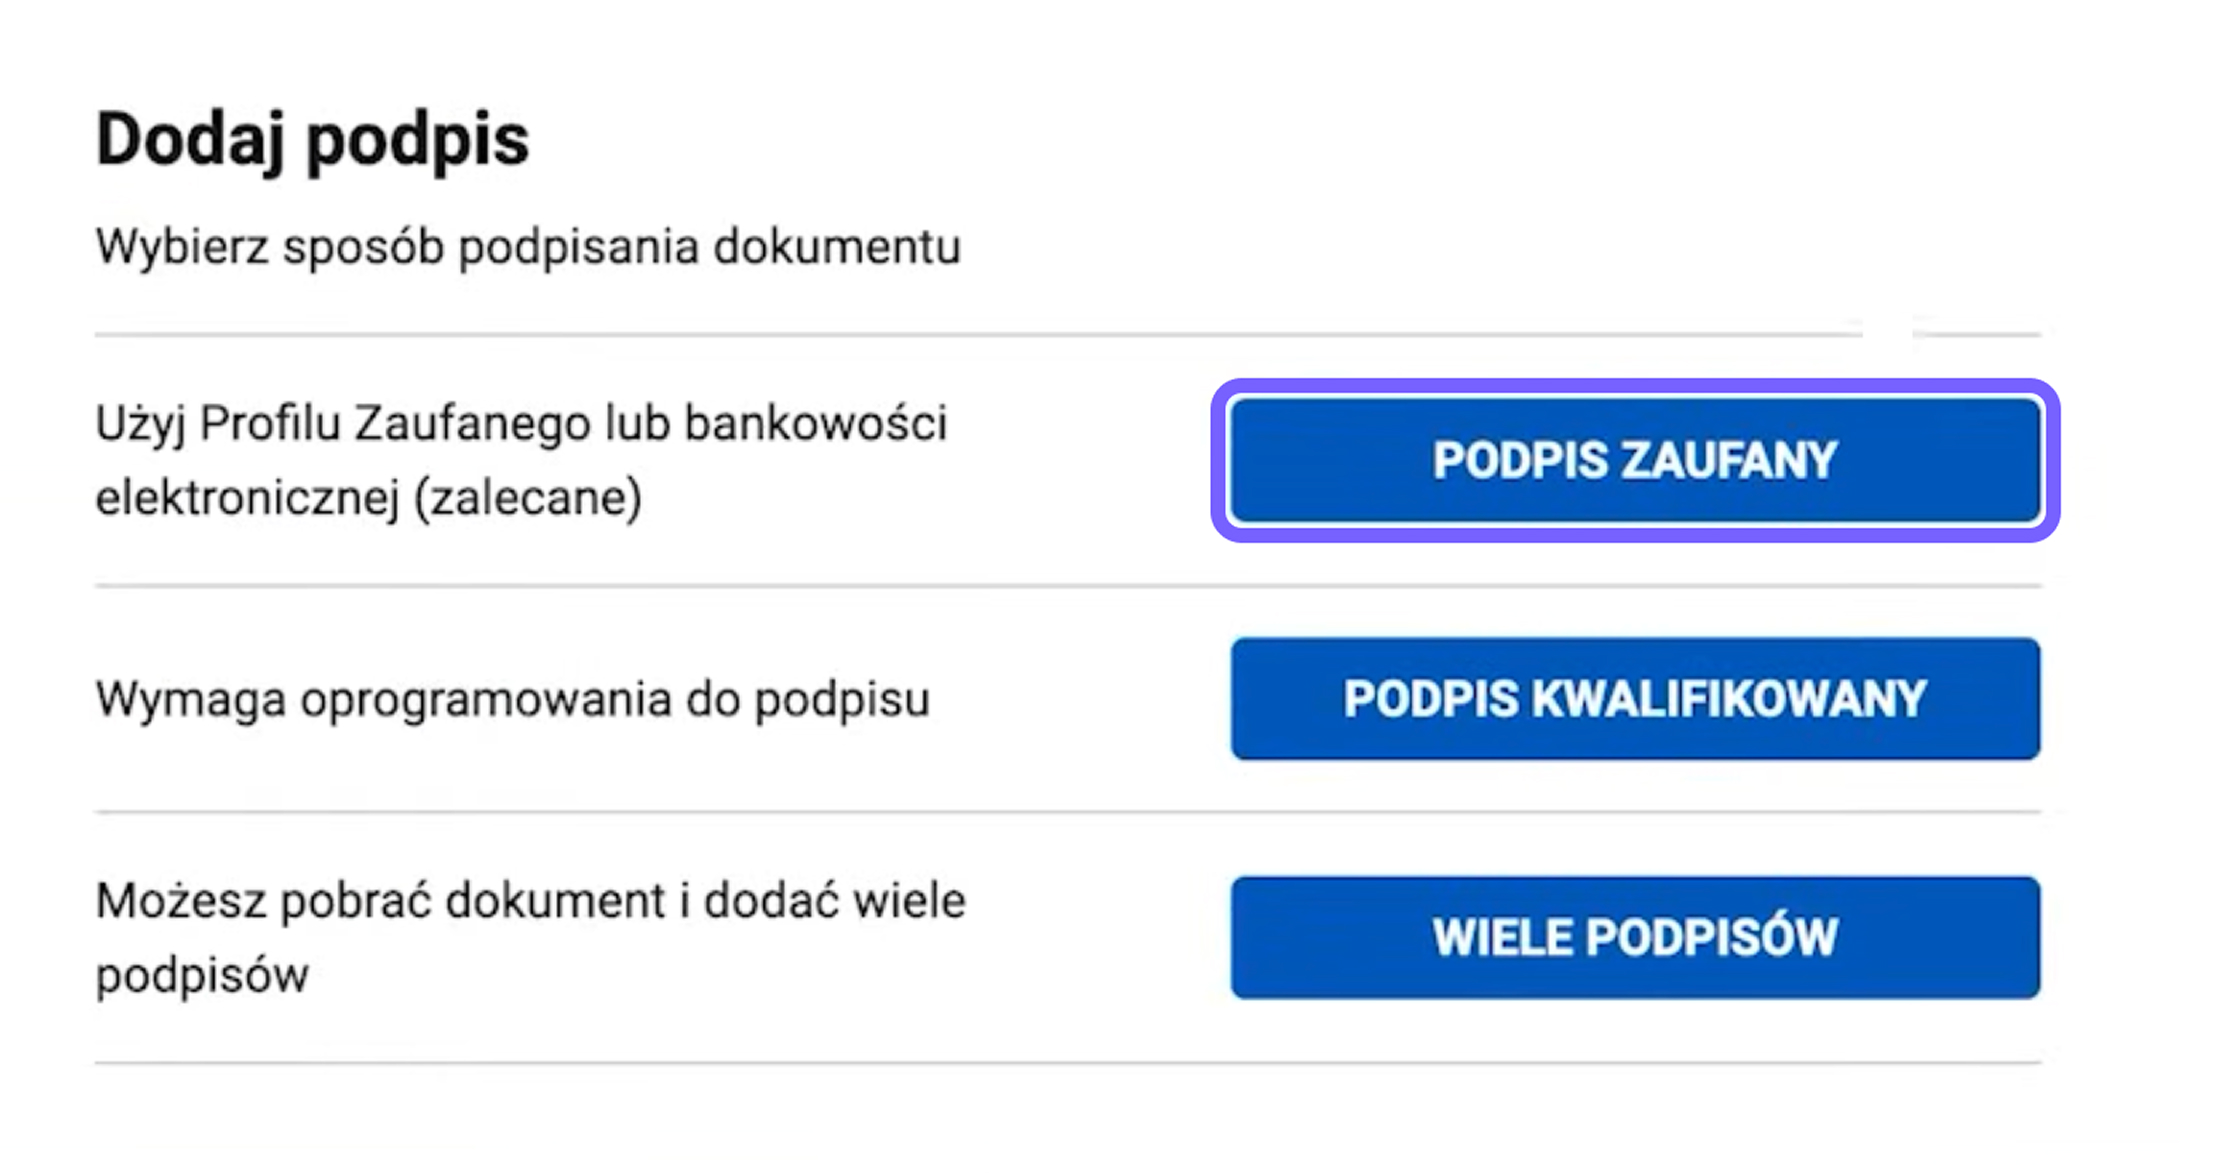
After reviewing the application, select your electronic signature method.
When using Profil Zaufany, click:
Podpis zaufany — Trusted signature
and then:
Podpisz podpisem zaufanym — Sign with a trusted signature.
The system will redirect you to the identity confirmation page. Log in and confirm the signature.
After returning to the application, make sure that the signature has been added.
Step 11. Submit the application
After signing, click Wyślij — Send.
A submission confirmation will appear on the screen. The document will also be available in the entrepreneur’s account.
It is advisable to save the confirmation or application reference number until the registration process has been completed.

Step 12. Wait for the instruction email
Once the application has been processed, an email confirming the creation of the e-Doręczenia address will be sent to the address provided earlier.
The email will explain what must be done to activate the inbox.
Important: submitting the application does not mean that the inbox is already active. You must follow the instructions in the email and complete the activation process.
Step 13. Activate the inbox
Follow the instructions in the email or log in again to Konto Przedsiębiorcy on Biznes.gov.pl.
Then:
- open the e-Doręczenia section;
- select the newly created address;
- proceed to activation;
- check the notification email address;
- accept the operator’s terms and conditions if required;
- click Aktywuj skrzynkę — Activate the inbox.
After activation, the address will be entered into the Electronic Address Database, BAE. From that point, public authorities will be able to send official correspondence to it.
What to do after activation
After logging in for the first time, it is advisable to:
- check the notification email address;
- confirm that the inbox status is active;
- arrange regular monitoring of incoming messages;
- give the accountant access if they will handle correspondence;
- appoint an additional administrator if necessary;
- establish a procedure for storing messages and delivery confirmations.
Do not rely only on notifications sent to a regular email account. The responsible person should also log in to the e-Doręczenia inbox regularly.
How to give an accountant access
A business owner or sole trader does not have to process every incoming message personally. Access can be granted to an accountant, lawyer, or another responsible employee.
Only the inbox administrator can add users and manage their permissions.
The system includes several standard roles:
- Właściciel — Owner: the inbox owner;
- Administrator: manages users, roles, and settings;
- Uprawniony — Authorised user: can work with correspondence within the permissions granted;
- Obserwator — Observer: has limited access, for example read-only access.
The administrator can also create additional roles with a selected set of permissions.
To add an accountant, the administrator should:
- log in to the business inbox;
- open the user management section;
- select the option to add a new user;
- enter the user’s details and email address;
- assign the appropriate role;
- send the invitation.
The invitation is valid for 14 days. Once it has been accepted, the user’s status changes to active, and they receive access to the inbox according to the assigned role.
Access is always granted to a specific individual. If an employee leaves the company or cooperation with an accounting firm ends, their permissions must be withdrawn.
Businesses may also appoint several administrators to reduce operational risk. This helps preserve access to inbox management if the main administrator is absent or no longer works with the organisation.
How to organise e-Doręczenia within a business
After activating the inbox, it is advisable to establish an internal procedure for handling official correspondence.
A basic procedure may include:
- checking incoming messages every working day;
- notifying the manager or client about a new document;
- recording the date of receipt and response deadline;
- appointing the person responsible for preparing the reply;
- saving proof of sending and receipt;
- regularly archiving correspondence;
- reviewing the list of users and their permissions.
The inbox provided by the public service provider has a guaranteed capacity of 3 GB for non-public entities. A received message remains available in the system for 180 days from the date of delivery.
Messages, attachments, and proof of sending and receipt should therefore be saved regularly in the company’s internal archive.
For a standard message sent to no more than 15 recipients, the maximum total size, including attachments, is 500 MB.
How much does e-Doręczenia cost?
Creating an address and using the public inbox to communicate with public authorities is free of charge for the entrepreneur.
Sending documents from a company or individual to a public authority through the public PURDE service costs PLN 0. The public authority covers the cost of correspondence it sends.
Legally valid correspondence between companies uses paid e-Doręczenia services. It may be provided by a qualified service provider or as an additional service offered by the selected operator.
Availability and pricing depend on the provider’s terms.
Frequently asked questions
Are notifications sent to a regular email address?
Yes. An email address can be added in the settings to receive notifications about new messages.
However, a regular email account is used only for notifications. The official document must be opened in the e-Doręczenia inbox.
Can a personal inbox be used for sole trader activity?
No. A separate business address must be created for activity registered in CEIDG.
Should messages be saved separately?
Yes. Inbox storage is limited, and some documents may be needed several years later.
It is advisable to save the message together with proof of sending and receipt.
Can the entire inbox be managed by an accountant?
An accountant can be granted access and the necessary permissions. However, the business owner remains responsible for controlling who has access and how deadlines are monitored within the business.
What should be done now?
Entrepreneurs registered in CEIDG before the end of 2024 do not have to wait until September 2026. The inbox can be created earlier, giving the business time to test the system and establish a clear procedure for handling correspondence.
Before implementation, check:
- whether the entrepreneur or company has an active address in BAE;
- who has been appointed as administrator;
- whether the notification email address is current;
- whether the accountant has the required access;
- whether correspondence is archived regularly;
- who is responsible for monitoring response deadlines.
Need help organising e-Doręczenia?
The ELP Office team will help you understand the necessary steps, arrange access for the responsible accountant, and establish a clear process for handling official correspondence.
This material is provided for informational purposes only. Individual legal and tax matters should be discussed with a qualified specialist.

Maternity and Paternity Leave for Sole Proprietorships (JDG) in Poland in 2026: A Complete Guide
Key Rules for Entrepreneurs
While salaried employees are automatically insured against all risks, for a sole proprietor (JDG), sickness insurance (dobrowolne ubezpieczenie chorobowe) is strictly voluntary. The entrepreneur must independently submit an application to ZUS to be included in this insurance system. It is these contributions that give you the right to receive maternity and paternity benefits.
Key leave rules for sole proprietors (applicable to all types of leave):
- No waiting period (0 days): Unlike regular sick leave, which requires paying contributions for 90 days, the right to maternity benefits arises literally from the first day of paying the chorobowe contribution. If you manage to activate the insurance before giving birth, you are entitled to the benefit.
- You can continue running your business: The legislation does not restrict your freedom of action. You can legally manage the company, issue invoices (faktury), and generate revenue right while receiving the benefit.
- Alternative: official suspension (Zawieszenie): If you do not plan to issue invoices and work in the first months after childbirth, the business can be officially suspended. A crucial legal nuance: if the company was active and contributions were paid at the time of birth, subsequent suspension of activities will not interrupt the cash flow from ZUS. The right to the benefit is already secured for you, and the suspension will reduce the administrative burden and even the payment of health insurance to zero.
- Micro-debts are allowed: On the day the insured event occurs (childbirth), your total debt to ZUS must not exceed 1% of the minimum wage (in 2026, this limit is 48.06 PLN). If the debt is less than this amount, payments will begin as usual. If the debt exceeds the limit, the right to payment is suspended, but you will have exactly 6 months to pay it off in full, after which ZUS will pay the benefit retroactively.
The Universal Minimum Rule (Kosiniakowe)
Even if you paid minimum contributions, the state will back you up. The Kosiniakowe rule applies: if, after all calculations, the benefit of the insured entrepreneur is below 1,000 PLN net per month, ZUS automatically guarantees a top-up to this amount.
Example: If you paid contributions from the preferential base (Preferencyjny ZUS) for a short time, the calculated benefit amount may be low (e.g., 350 PLN net). In this case, ZUS automatically compensates the difference (650 PLN) from the state budget. This state top-up is completely exempt from income tax (PIT).
Important clarification: This rule applies only to maternity and parental leave and does not apply to paternity leave (urlop ojcowski). You also need to consider taxes: ZUS first calculates the base amount, deducts the tax advance (PIT), and only if the net amount is less than 1,000 PLN does it compensate the difference.
Timeline: 3 Types of Leave for Parents
To maximize financial benefits and time with the child, parents can flexibly combine three types of leave. The state system works as a single mechanism: even if one parent is employed (Umowa o pracę) and the other runs a JDG, you can still share the total quotas between yourselves.
- Maternity Leave (Urlop macierzyński): The primary, basic leave for the mother. It lasts 20 weeks (for the birth of one child) and is granted immediately after the baby is born.
- Parental Leave (Urlop rodzicielski): A shared pool of time (up to 41 weeks) that can be flexibly divided between parents. The exception is the 9 "non-transferable" weeks, which are strictly reserved for the second parent (most often the father).
- Paternity Leave (Urlop ojcowski): A short 14-day leave exclusively for the father. It is paid at a 100% rate and expires when the child turns 1 year old.
Let's take a closer look at each one.
Maternity Leave (Urlop macierzyński)
Maternity leave is the first and mandatory stage of support. Its basic duration depends on the number of children born:
- 1 child: 20 weeks (140 days).
- 2 children (twins): 31 weeks (217 days).
Recommendation: Although the law allows you to start maternity leave 6 weeks before childbirth, financially, this is not the most advantageous decision. It is much more effective to take regular pregnancy sick leave (Zwolnienie lekarskie — code B) prior to the birth. It is paid at a rate of 100% of the base, and all your legal 20 weeks of maternity leave will be preserved for use after the baby is born!
How Benefits Are Calculated: Two Strategies
Payouts are calculated based on your ZUS base for the last 12 months. You have two paths, and the choice depends on how quickly you submit your application to ZUS. To understand the real numbers, it is important to know the current ZUS bases for 2026:
It is from these amounts that the payout percentages will be calculated depending on the strategy you choose:
- Stability Strategy (81.5% rate): If you submit one general application for both leaves (maternity + parental) within 21 days after childbirth, ZUS will pay you 81.5% of your calculated base throughout the year. This is the most popular option, ensuring a steady cash flow.
- Stepped Strategy (100% / 70% rate): If you miss the 21-day deadline or submit applications separately (first for maternity, and half a year later for parental), the first 20 weeks will be paid at a 100% rate, and the subsequent parental leave at a 70% rate.
Parental Leave (Urlop rodzicielski) and the Father's Quota
The right to take parental leave (urlop rodzicielski) arises immediately after the end of maternity leave (or from the moment of the child's birth if the mother does not have insurance). This is a logical continuation of support, but with one fundamental difference: this leave is intended for both parents.
The basic total duration of this leave for the birth of one child in 2026 is 41 weeks (for twins — 43 weeks). According to Work-Life Balance rules, neither parent can claim this entire duration for themselves.
Leave Architecture:
- Maximum for one parent: 32 weeks (this is the absolute maximum a mother or father can take individually).
- Non-transferable quota: 9 weeks. Exclusively reserved for the second parent (most often the father). These weeks cannot be transferred to the mother — if the father declines the leave, they are simply canceled.
- The remaining weeks can be divided between the parents in any proportion or used simultaneously.
Key Conditions of Parental Leave
The mechanics of this leave give entrepreneurs maximum flexibility in planning their time and finances. The following accommodating conditions apply to JDG payers:
- Freedom of timing: The leave does not necessarily have to be taken immediately after maternity leave ends. You can use it at any time up until the end of the calendar year in which the child turns 6.
- Can be split: You are not obligated to take all the weeks in one block. The leave can be divided into a maximum of 5 parts.
- Simultaneous use: Mom and dad can be on parental leave at the same time. For example, you can take a portion of the shared quota and spend a month at home together.
- Legal work: As with maternity leave, while receiving the benefit, you can continue to conduct business operations, manage the company, and issue invoices.
Benefit Amount: The payout amount during parental leave directly depends on the strategy you chose when submitting documents right after childbirth (detailed in the section above).
Special Conditions for an Entrepreneur Father (Dodatkowy rodzicielski)
Returning to the 9 weeks strictly reserved for the father. If the father is also an entrepreneur, the following payout rules apply to him:
- Cannot be transferred to the mother: If the father opts not to take the leave, this period is simply nullified.
- Separate calculation base: The benefit for this period is calculated based on the father's individual ZUS base and amounts to 70% of this base.
- Immediate payouts: There is no need to wait 3 months after setting up voluntary chorobowe insurance; the right is established immediately provided the insurance is active.
- Deadlines: These 9 weeks can be used (in a single block or several parts) until the end of the calendar year in which the child turns 6.
- And yes, the father can continue running his business and issuing invoices during this leave!
Addition: If the mother is insured with ZUS but for some reason did not use her share of the parental leave, the father can claim the main portion for himself (up to 32 weeks). This requires a written statement (oświadczenie) from the mother. Important: If the spouse does not have insurance and receives state aid for mothers (świadczenie rodzicielskie) through MOPS or Urząd, the entrepreneur father will not be able to claim these shared 32 weeks from ZUS. However, his personal non-transferable quota of 9 weeks remains securely his under any circumstances!
Paternity Leave (Urlop ojcowski)
This is a separate entitlement, independent of the mother's maternity leave. Entrepreneur fathers have the right to 14 calendar days of leave, financed at 100% of the father's individual ZUS base.
Key features:
- Strict deadlines: The leave must be utilized strictly before the child reaches 1 year of age (12 months). It can be taken entirely as one block (14 days) or split into two equal halves (7 days each).
- Double benefit: You have the legal right to reduce your ZUS social contribution obligations proportionally to the days of your leave. For "Duży ZUS" payers in 2026, the savings for 14 days will amount to approximately 899 PLN.
- Business doesn't stop: You can continue to sign contracts and issue invoices directly during this leave.
- Taxation (PIT) and exemptions: By default, the paternity leave benefit is subject to standard tax (12% advance), just like other ZUS disbursements. However, you have the opportunity to achieve absolute PIT-0 if you qualify for one of 4 targeted reliefs: you are under 26 (Ulga dla młodych), you have 4 or more children, you qualify for the return relief (repatriation), or you are a working pensioner. In these scenarios, the payout is tax-exempt.
Instructions: Paperwork and ZUS Contribution Optimization
Here we have consolidated all the bureaucratic steps required to properly formalize your payouts.
When transitioning into any of the listed leaves, the state assumes the payment of your social contributions (pension and disability). However, ZUS does not update this data automatically! You must independently update your status within 7 days from the start date of the specific leave. During the benefit period, the entrepreneur is only obligated to pay health insurance (ubezpieczenie zdrowotne).
What to do in ZUS (via the PUE/eZUS platform):
- Temporarily deregister from full social insurances (form ZUS ZWUA).
- Register exclusively for zdrowotne by changing the registration code (form ZUS ZZA).
Legal contribution optimization: Typically, when switching to zdrowotne via the ZZA form, the standard code 05 10 00 is used. But if your benefit is small and the state tops it up to 1,000 PLN under the Kosiniakowe rule, use the special code 05 80 00 (or 05 81 00). This grants you the legal right to skip paying even the health insurance.
What documents to submit for the benefit:
Regardless of who is taking the leave or what kind of leave it is, you will always need:
- ZUS Z-3b (a special income certificate for entrepreneurs (JDG), which serves as the basis for calculating the benefit amount).
- Akt urodzenia dziecka (a copy of the child's birth certificate).
Additionally, append the following depending on the specific leave you are applying for:
- Maternity + Parental (Single application): ZUS ZAM — The unified universal form for maternity benefit applications. This form is used if the mother wishes to declare her intent to take both maternity and parental leave as a single continuous block within 21 days of birth (to lock in the 81.5% rate).
- Maternity Leave only: ZUS ZAM — standard application for urlop macierzyński.
- Parental Leave (for mom or dad): ZUS ZUR — application for urlop rodzicielski. Additionally: if one parent claims the shared portion of the leave (e.g., the father takes 32 weeks instead of the mother), you must attach an Oświadczenie drugiego rodzica (a declaration from the second parent confirming they are not utilizing their share).
- Paternity Leave (14 days): ZUS ZAO — the exclusive application for dads for urlop ojcowski.
Returning to Work
After the leave concludes, the procedure must be repeated in reverse: you need to deregister from zdrowotne (ZWUA) once again and submit form ZUS ZUA to restore your full insurance package. During this process, you have the legal right to proportionally reduce your social contributions for the month in which you were on leave (for instance, for those 14 days of paternity leave).
When you commence maternity leave, your voluntary sickness insurance is canceled automatically. Therefore, when submitting the ZUA form upon returning to work, you are strictly obliged to check the box again to confirm your desire to rejoin the voluntary sickness insurance scheme (dobrowolne ubezpieczenie chorobowe) within 7 days. If you neglect to check this box, your continuity of insurance will be broken, and you will forfeit the right to paid sick leave (L4) in the future.
Contribution Holidays (Wakacje składkowe)
When mapping out maternity leaves, do not overlook the current support mechanism available for micro-entrepreneurs. Once per calendar year, you have the right to select one month of complete exemption from paying social contributions. In 2026, for Duży ZUS payers, this translates to savings of 1,926.76 PLN for the month.
You cannot utilize these contribution holidays during the same month you receive maternity benefits. However, it serves as an ideal strategic asset that can be activated immediately before heading into maternity leave or directly after returning to work. Furthermore, an entrepreneur father can take his 14 days of paternity leave in one month and the contribution holidays in a subsequent month, thereby maximizing the overall financial support extracted from the state.
Disclaimer: This article is for informational purposes only and relies on current ZUS data for 2026. Every entrepreneur's situation is unique, and legal interpretations may evolve. For precise benefit calculations and tailored tax strategy planning, we strongly recommend booking an individual consultation with an accountant.
